

Guiding and Establishing National Innovation for U.S. Stablecoins Act or the GENIUS Act This act establishes a regulatory framework for payment stablecoins (digital assets which an issuer must redeem for a fixed value). Under the act, only permitted issuers may issue a payment stablecoin for use by U.S. persons, subject to certain exceptions and safe harbors. Permitted issuers must be a subsidiary of an insured depository institution, a federal-qualified nonbank payment stablecoin issuer, or a state-qualified payment stablecoin issuer. Permitted issuers must be regulated by the appropriate federal or state regulator. Permitted issuers may choose federal or state regulation; however, state regulation is limited to those with a stablecoin issuance of $10 billion or less. Permitted issuers must maintain reserves backing the stablecoin on a one-to-one basis using U.S. currency or other similarly liquid assets, as specified. Permitted issuers must also publicly disclose their redemption policy and publish monthly the details of their reserves. The act specifies requirements for (1) reusing reserves; (2) providing safekeeping services for stablecoins; and (3) supervisory, examination, and enforcement authority over federal-qualified issuers. The act allows foreign issuers of stablecoins to offer, sell, or make available in the United States stablecoins using digital asset service providers, subject to requirements, including a determination by the Department of Treasury that they are subject to comparable foreign regulations. Under the act, permitted payment stablecoins are not considered securities or commodities under law. However, permitted issuers are subject to the Bank Secrecy Act for anti-money laundering and related purposes. (Sec. 3) This section establishes that only payment stablecoin issuers permitted under this act are allowed to issue a payment stablecoin in the United States. Knowing violations of this requirement shall be subject to a fine of up to $1 million for each violation, up to 5 years imprisonment, or both. Treasury may issue regulations establishing limited safe harbors from this requirement that are consistent with the act's purposes, limited in scope, and apply to a de minimus volume of transactions. Three years after the date of enactment, digital asset service providers are prohibited from offering or selling stablecoins that are not issued by permitted issuers. Providers are also prohibited from offering, selling, or otherwise making available in the United States a foreign-issued payment stablecoin, unless it complies with requirements provided in section 18 of the act. (Sec. 4) This section establishes requirements for permitted issuers. Issuers must maintain reserves on a one-to-one basis. Reserves must be comprised of U.S. coins and currency; demand deposits or shares at an insured depository institution; certain Treasury acts, notes, or bonds; money received under certain repurchase agreements or reverse repurchase agreements; certain investment company securities and money market funds invested in certain approved assets on this list; similarly liquid federal assets approved by regulators; or certain listed reserves in tokenized forms. Issuers must comply with redemption requirements, such as establishing timely redemption procedures and disclosing such procedures and associated fees. Issuers must also report on the monthly composition of the issuer's reserves. These reports must be examined by a registered public accounting firm and certified by the chief executive officer and chief financial officer of the issuer. The section prohibits the rehypothecation, or reuse, of reserves with limited exceptions. Primary federal payment stablecoin regulators (federal regulators) and state payment stablecoin regulators (state regulators), where applicable, must issue regulations to implement capital requirements, liquidity reserve standards, reserve asset diversification standards, and risk management standards. Issuers are subject to the anti-money laundering and counterterrorism requirements that are applicable to financial institutions. The section sets forth requirements regarding activities of a permitted issuer, including by prohibiting issuers from providing services on the condition that a customer obtains an additional paid product or service from the issuer or a subsidiary. Large issuers (those with more than $50 billion in consolidated total outstanding issuance) must publish an audited annual financial statement in accordance with generally accepted accounting principles. The section prohibits a public nonfinancial services company from issuing payment stablecoins unless the company obtains unanimous approval from the Stablecoin Certification Review Committee. A state qualified payment stablecoin issuer with a consolidated total outstanding issuance of not more than $10 billion may opt for state regulation if such regulation is substantially similar to the federal regulatory framework under this act. If the issuance exceeds that amount, the issuer must transition to federal regulation, receive a waiver from the federal regulator to remain under state regulation, or stop issuing stablecoins until the issuance is under the threshold. (Sec. 5) This section establishes requirements for stablecoins issued by subsidiaries of insured depository institutions and certain entities chartered by the Office of the Comptroller of the Currency (OCC) to issue payment stablecoins. Federal regulators must establish an application process and a supervision framework for such entities. The section sets forth requirements for the review of applications, explanations for denials, and an appeals process. (Sec. 6) This section sets forth supervision, examination, and enforcement requirements for payment stablecoin issuers under federal supervision. The provisions include reporting on financial conditions, risk management, compliance with the act, and compliance with sanctions and anti-money laundering requirements. The section specifies that payment stablecoin issuers with less than $10 billion in consolidated total outstanding issuance are subject to federal supervision if they are not state qualified payment stablecoin issuers. The section establishes civil penalties for violations of this act that are committed by those subject to federal supervision. (Sec. 7) This section establishes state regulatory authority over issuers that qualify for and elect state regulation. The Federal Reserve Board may exercise enforcement authority over state issuers in unusual and exigent circumstances. The OCC must exercise enforcement authority over nonbank state issuers in these circumstances. (Sec. 8) This section requires foreign issuers to comply with the terms of lawful orders to be allowed to offer, sell, or make available for trading a payment stablecoin in the United States. The section sets forth enforcement and appeal provisions. Treasury may waive the prohibition against the secondary trading of foreign payment stablecoins in the United States from noncompliant foreign issuers on a case-by-case basis if certain criteria are met. (Sec. 9) Treasury must seek public comment regarding methods, techniques, or strategies for financial institutions to detect illicit activities involving digital assets and perform research and risk assessments on such methods, techniques, or strategies. Treasury must report their legislative recommendations to Congress and the Financial Crimes Enforcement Network must issue rules based on the results. (Sec. 10) This section establishes requirements for custodial or safekeeping services for payment stablecoin reserves, collateral, and the private keys used to issue stablecoins. Among other requirements, such property must be separately accounted for and not comingled with other assets of the custodian. (Sec. 11) This section addresses the treatment of payment stablecoins and stablecoin issuers in bankruptcy and insolvency proceedings, including their claim priority, conditions for an automatic stay, and the treatment of reserves as property of the estate. Federal regulators must also report on topics regarding potential insolvency proceedings of issuers. (Sec. 12) Federal regulators may, if determined necessary after an assessment, prescribe technical standards for issuers to promote compatibility and interoperability with other issuers and the broader digital finance system. (Sec. 13) This section requires regulators to issue regulations to carry out the act, with federal and state regulators and Treasury coordinating as appropriate. (Sec. 14) This section requires Treasury to study and report on nonpayment stablecoins, including endogenously collateralized payment stablecoins (a digital asset the originator of which has represented will be converted, redeemed, or repurchased for a fixed amount of monetary value and that relies solely on the value of another digital asset created or maintained by the same originator to maintain the fixed price). (Sec. 15) This section requires federal regulators to annually report on payment stablecoin activity trends, the number of payment stablecoin issuer applicants, and the potential financial stability risks to the safety and soundness of the broader financial system posed by payment stablecoin activities. (Sec. 16) This section defines authorities related to the act, such as by providing that the act does not limit the authority of a depository institution, credit union, national bank, or trust company to issue digital assets to represent deposits or shares. Federal financial regulators may not require a financial institution to include certain digital assets held in its custody as a liability on financial statements or balance sheets. (Sec. 17) This section establishes that payment stablecoins issued by permitted issuers are not securities or commodities under federal law. (Sec. 18) This section provides an exception to the act's prohibition on foreign-issued payment stablecoins. For the exception to apply, foreign issuers must be subject to regulation and supervision by a foreign country that is comparable to the requirements under this act, as determined by Treasury. The foreign issuer must also be registered with the OCC, hold sufficient reserves in a U.S. financial institution (subject to exceptions), and the country where the issuer is domiciled must not be subject to U.S. sanctions. The section sets forth requirements for Treasury's determination as to whether a foreign country has comparable regulatory and supervisory requirements, including the process of requesting a determination, the deadline for Treasury to render a decision, and the process by which Treasury may rescind a previous determination. The section also sets forth OCC registration requirements. Treasury may implement reciprocal or bilateral agreements between the United States and jurisdictions with comparable regulatory requirements. (Sec. 19) This section requires certain federal employees to disclose holdings over $5,000 of permitted payment stablecoins as part of required financial disclosures. (Sec. 20) The act takes effect on the earlier of (1) 18 months after the date of enactment, or (2) 120 days after federal regulators issue final regulations implementing the act.
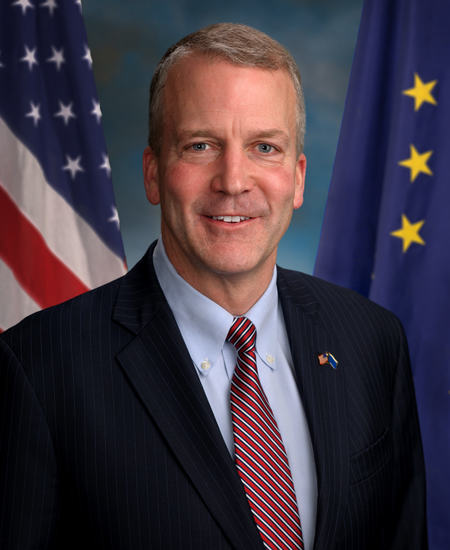
Sen. Dan Sullivan
Sponsored bills
Maddy summaryS 2316, the Cooper Davis and Devin Norring Act, requires electronic communication service providers and remote computing services to report to the Attorney General when they have actual knowledge of certain drug-related crimes involving fentanyl, methamphetamine, counterfeit prescription drugs, or unauthorized prescription medications. Providers must submit detailed reports within 60 days, including account information and relevant data about the crime, but not the content of communications. The bill imposes civil penalties of up to $190,000 for failing to report and $100,000 for submitting false reports, while protecting providers from being required to monitor content or scan for violations. It exempts broadband internet and text messaging service providers from these requirements and mandates annual reports from the Attorney General on the number and outcomes of submitted reports. The law aims to improve law enforcement's ability to address drug trafficking while maintaining privacy protections for users.
Halt All Lethal Trafficking of Fentanyl Act or the HALT Fentanyl Act This act permanently places fentanyl-related substances as a class into schedule I of the Controlled Substances Act. A schedule I controlled substance is a drug, substance, or chemical that has a high potential for abuse; has no currently accepted medical value; and is subject to regulatory controls and administrative, civil, and criminal penalties under the Controlled Substances Act. Under the act, offenses involving fentanyl-related substances are triggered by the same quantity thresholds and subject to the same penalties as offenses involving fentanyl analogues (e.g., offenses involving 100 grams or more trigger a 10-year mandatory minimum prison term). Additionally, the act establishes a new, alternative registration process for certain schedule I research. The act also makes several other changes to registration requirements for conducting research with controlled substances, including permitting a single registration for related research sites in certain circumstances, waiving the requirement for a new inspection in certain situations, and allowing a registered researcher to perform certain manufacturing activities with small quantities of a substance without obtaining a manufacturing registration. Finally, the act expresses the sense that Congress agrees with the interpretation of the Controlled Substances Act in United States v. McCray , a 2018 case decided by the U.S. District Court for the Western District of New York. In that case, the court held that butyryl fentanyl, a controlled substance, can be considered an analogue of fentanyl even though, under the Controlled Substances Act, the term controlled substance analogue specifically excludes a controlled substance.
Maddy summarySRES 322 designates June 2025 as "National Post-Traumatic Stress Awareness Month" and June 27, 2025, as "National Post-Traumatic Stress Awareness Day" to raise public awareness about post-traumatic stress, particularly among veterans and military personnel. The resolution supports efforts by the Department of Veterans Affairs and Department of Defense to educate about symptoms, treatment, and stigma reduction, while encouraging cultural change and appropriate care. This symbolic gesture has no legal effect or funding implications but aims to reduce stigma and promote mental health support for those affected.
Maddy summaryThis Senate resolution (SRES 283) designates July 6, 2025 - the 90th birthday of the 14th Dalai Lama - as "A Day of Compassion." It affirms U.S. support for the Tibetan people’s human rights, including their distinct religious, cultural, linguistic, and historical identity. The resolution references the 2020 Tibetan Policy and Support Act, emphasizing that decisions about Tibetan Buddhist leadership (including future Dalai Lamas) must be determined by religious authorities within Tibetan Buddhism, not by the Chinese government. As a ceremonial resolution, it expresses symbolic support but does not create new legal obligations.
Maddy summaryThis bill authorizes the minting of commemorative coins for the 2028 Los Angeles Olympic and Paralympic Games and the 2034 Salt Lake City Olympic and Paralympic Winter Games. It specifies four coin types ($5 gold, $1 silver, half-dollar, and proof silver $1) with defined quantities and designs reflecting U.S. athletic participation. A surcharge on each coin sale (e.g., $35 for $5 coins) funds the respective Olympic committees' legacy programs, including youth sports initiatives. The coins are legal tender but intended solely for commemoration, with surcharges directed to the organizing committees after covering minting costs.
Maddy summaryThis resolution expresses the U.S. Senate's support for designating July 10, 2025, as Journeyman Lineworkers Recognition Day. It honors journeyman lineworkers who maintain the nation’s power grid 24/7, restore electricity during disasters, and work in hazardous conditions. The resolution specifically recognizes the 129th anniversary of Henry Miller, the first president of the International Brotherhood of Electrical Workers, who died while restoring power in 1901. The Senate encourages the public to observe this day to reflect on lineworkers’ contributions and sacrifices. (Note: This is a symbolic resolution with no legal force or funding impact.)
Maddy summaryS 2229, the United States Foreign Service Commemorative Coin Act, authorizes the minting of three commemorative coins to honor the 100th anniversary of the U.S. Foreign Service (established by the 1924 Rogers Act). It specifies $5 gold coins (max 50,000), $1 silver coins (max 400,000), and half-dollar coins (max 750,000) to be issued in 2029, featuring designs symbolizing U.S. diplomacy. A surcharge from each coin sale ($35 for gold, $10 for silver, $5 for half-dollar) will fund the Association for Diplomatic Studies and Training to preserve diplomatic history through oral histories and other programs. The coins are legal tender and will be sold at face value plus surcharge and production costs, with all funds going directly to support the Association's work.
Maddy summaryThis bill reauthorizes two existing federal diabetes programs through 2027. It provides $160 million annually for fiscal years 2026 and 2027 for the Special Diabetes Program for Type I Diabetes (serving people with Type I diabetes) and the Special Diabetes Program for Indians (serving Native American communities through Indian Health Services). A final $40 million is allocated for October-December 2027 for both programs, with all funds remaining available until expended. The bill extends current funding levels without changing program eligibility or structure.
Maddy summaryThis bill requires military counselors at U.S. installations to receive training on state foster care rules and resources, designating them as "foster care liaisons" to assist military families. It mandates that Military OneSource, a support service for military families, include a dedicated feature for accessing foster care information and resources by state. The Defense Secretary must also collaborate with the Administration for Children and Families to develop training materials and gather foster care resources for military families. These changes directly affect military families stationed at U.S. bases who may need foster care support, aiming to simplify access to state-specific foster care systems.