

Issue · Budget & Taxes
Budget & Taxes (Tax Incentives)
Every budget & taxes bill, vote, and legislator stance in Pennsylvania, automatically classified by Maddy, our AI policy reader.
Total bills
75
2025-2026 Regular Session
Top supporter
Dan Frankel
100% support rate
Top opponent
Charity Krupa
0% support rate
Ranked legislators
10
5 support · 5 oppose
Key legislators
Who's moving tax incentives in Pennsylvania
| Legislator | Party | Stance | Support rate | Votes |
|---|---|---|---|---|
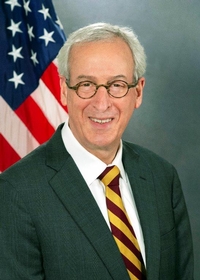
Dan Frankel
House · District 23
|
D |
Strong +
|
100% | 8 |
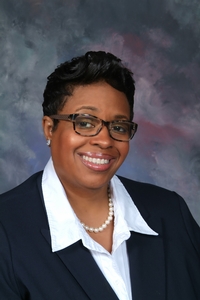
Darisha Parker
House · District 198
|
D |
Strong +
|
100% | 8 |
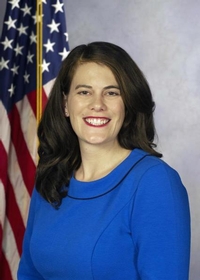
Elizabeth Fiedler
House · District 184
|
D |
Strong +
|
100% | 8 |
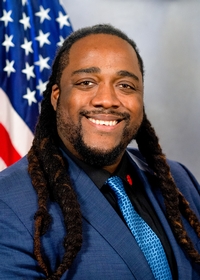
Izzy Smith-Wade-El
House · District 49
|
D |
Strong +
|
100% | 8 |
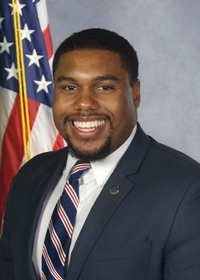
Jason Dawkins
House · District 179
|
D |
Strong +
|
100% | 8 |

Charity Krupa
House · District 51
|
R |
Strong −
|
0% | 7 |
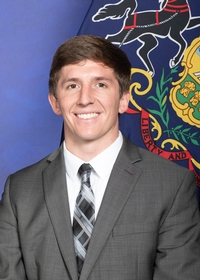
Dallas Kephart
House · District 73
|
R |
Strong −
|
0% | 7 |
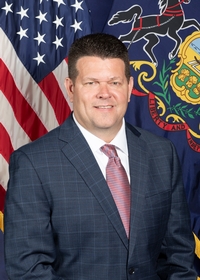
Jamie Walsh
House · District 117
|
R |
Strong −
|
0% | 6 |
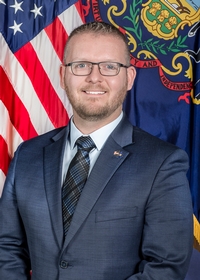
Josh Bashline
House · District 63
|
R |
Strong −
|
0% | 6 |
Ryan Warner
House · District 52
|
R |
Strong −
|
0% | 6 |
Showing 71–75 of 75
bills
All budget & taxes bills
HB 1960: An Act providing for an exemption to a business income and receipts tax imposed by a city of the first class.
HB 1214: An Act amending the act of May 22, 1933 (P.L.853, No.155), known as The General County Assessment Law, in subjects of taxation and exemptions, further providing for temporary tax exemption for residential construction.
Topics
✓ Budget & TaxesSupports Budget & TaxesBill provides temporary tax exemption for new residential construction, reducing property tax burden per summary. Aligns with tax relief indicator for Budget & Taxes.
✓ HousingSupports HousingTax exemption for new residential construction incentivizes housing development, increasing supply which alignates with affordable housing goals by lowering development costs for builders.
HB 1667: An Act amending the act of March 4, 1971 (P.L.6, No.2), known as the Tax Reform Code of 1971, in sales and use tax, further providing for exclusions from tax; in corporate net income tax, further providing for definitions, for determination of net loss deduction, for imposition of tax, for reports and payment of tax, for timely mailing treated as timely filing and payment and for additional withholding requirements, repealing provisions relating to consolidated reports, further providing for extension of time to file reports, for changes made by Federal Government, for limitations on assessments, for definitions, for manufacturing innovation and reinvestment deduction, for enforcement, rules and regulations and inquisitorial powers of the department, for retention of records and for penalties; in gross receipts tax, further providing for imposition of tax and providing for definitions; in tax credit and tax benefit administration, providing for application of tax credits or tax benefits to a unitary business; providing for educational tax credits and for education options tax credits; in manufacturing and investment tax credit, further providing for business firms and for tax credit certificates; providing for return on equity and for service and facilities; repealing provisions relating to Computer Data Center Equipment Incentive Program; providing for additional property tax rebate; in general provisions, providing for data centers; and, in general provisions, further providing for estimated tax, for underpayment of estimated tax and for restatement of tax liability under treaties and providing for data centers.
HB 244: An Act amending the act of March 4, 1971 (P.L.6, No.2), known as the Tax Reform Code of 1971, in sales and use tax, further providing for exclusions from tax.
Topics
✓ Budget & TaxesSupports Budget & TaxesExempts alternative fuel/hybrid vehicles from sales tax (2026-2027), providing targeted tax relief to consumers purchasing qualifying vehicles per Tax Reform Code.
✓ EnergySupports EnergyExempts alternative fuel/hybrid vehicles from sales tax to promote cleaner transportation adoption and reduce fossil fuel dependence per 2026-2027 tax break.
✓ EnvironmentSupports EnvironmentExempts alternative fuel/hybrid vehicles from sales tax to incentivize cleaner transportation, reducing emissions and aligning with environmental protection goals.
✓ TransportationSupports TransportationExempts alternative fuel/hybrid vehicles from sales tax to promote sustainable transportation adoption, aligning with 'promotes sustainable transportation' indicator.