Maddy summaryS 364, titled the "Hearing Protection Act" (though it regulates firearm silencers, not hearing protection), changes federal law to treat firearm silencers like firearms for tax and regulatory purposes. It imposes a 10% federal tax on silencers (similar to firearms), preempts state laws that tax or regulate silencers beyond federal rules, and requires the destruction of existing silencer registration records within one year. The bill clarifies definitions of "firearm silencer" in federal law and modifies licensing requirements for these devices. This directly affects silencer owners, manufacturers, and state governments that previously imposed additional restrictions or taxes.
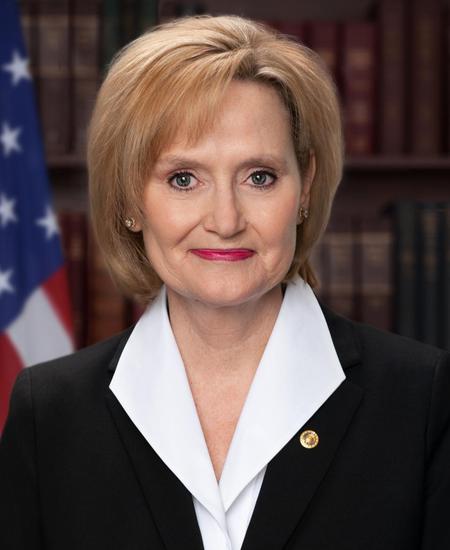
Sen. Cindy Hyde-Smith
Sponsored bills
Nancy Gardner Sewell Medicare Multi-Cancer Early Detection Screening Coverage Act This bill allows, beginning in 2028, for Medicare coverage and payment for multi-cancer early detection screening tests that are approved by the Food and Drug Administration and that are used to screen for cancer across many cancer types, if the Centers for Medicare & Medicaid Services determines such coverage is appropriate. Coverage is limited to those under a certain age (age 68 in 2028, increased by one year every year thereafter) and to one test every 11 months.
Maddy summaryThis bill modifies Medicare payment calculations for rural hospitals to provide increased funding. It directly affects "sole community hospitals" and "Medicare-dependent hospitals" by rebasing their payment formulas using a 2016 cost reporting period as the new base, effective October 1, 2025. The key mechanism replaces the previous base period with 2016 data, potentially increasing payments if this change results in higher reimbursement. The bill also extends existing payment programs for these hospitals through future fiscal years and prohibits certain payment adjustments for rebased amounts. This is a technical adjustment to Medicare reimbursement rules, not a new eligibility program.
Maddy summaryThis bill establishes tax credits for individuals and corporations who contribute to scholarship granting organizations that provide educational scholarships for eligible students. The individual tax credit is limited to 10% of adjusted gross income or $5,000, while corporate credits are capped at 5% of taxable income. The bill defines "eligible students" as those from households with income not exceeding 300% of the area median gross income, and specifies that scholarships can cover tuition, materials, tutoring, and educational therapies. The bill includes a $10 billion annual cap on tax credits, with a first-come, first-served allocation system, and requires scholarship organizations to meet specific financial and operational standards.
Laken Riley Act This act requires the Department of Homeland Security (DHS) to detain certain non-U.S. nationals ( aliens under federal law) who have been arrested for burglary, theft, larceny, shoplifting, assault of a law enforcement officer, or any crime that results in death or serious bodily injury to another person. The act also authorizes states to sue the federal government for decisions or alleged failures related to immigration enforcement. Under this act, DHS must detain an individual who (1) is unlawfully present in the United States or did not possess the necessary documents when applying for admission; and (2) has been charged with, arrested for, convicted of, or admits to having committed acts that constitute the essential elements of the above crimes. The act also authorizes state governments to sue for injunctive relief over certain immigration-related decisions or alleged failures by the federal government if the decision or failure caused the state or its residents harm, including financial harm of more than $100. Specifically, the state government may sue the federal government over a decision to release a non-U.S. national from custody; failure to fulfill requirements relating to inspecting individuals seeking admission into the United States, including requirements related to asylum interviews; failure to fulfill a requirement to stop issuing visas to nationals of a country that unreasonably denies or delays acceptance of nationals of that country; violation of limitations on immigration parole, such as the requirement that parole be granted only on a case-by-case basis; or failure to detain an individual who has been ordered removed from the United States.
Maddy summaryThis bill amends U.S. law to make the American Community Survey (ACS) truly voluntary. It removes penalties for households that refuse to answer ACS questions and requires the Census Bureau to include a clear statement on the survey itself stating participation is voluntary. The bill directly affects all households receiving the ACS, which collects detailed demographic data for communities. Key changes are: (1) eliminating civil penalties for non-response, and (2) mandating a voluntary participation notice on the survey form. These changes apply to the current ACS and any future successor survey.
Maddy summaryThe Saving American Workers’ Benefits Act of 2025 requires taxpayers claiming the Child Tax Credit or Earned Income Credit to provide Social Security Numbers (SSNs) that confirm the individual is authorized to work in the United States. Specifically, the SSN must be issued to a U.S. citizen or under specific Social Security Act provisions indicating work eligibility, and must be issued before the tax return deadline. The bill updates tax code references to replace "TIN" (Taxpayer Identification Number) with "SSN" in certain procedures and removes an exception for SSNs that do not indicate work authorization. These changes apply to tax returns for taxable years beginning after December 31, 2025, directly affecting individuals seeking these federal tax credits.
Maddy summaryS 271, the "Stop Illegal Reentry Act," increases penalties for immigrants who re-enter the U.S. after being denied entry, deported, or removed without authorization. It directly affects individuals previously removed or excluded from the U.S. who return without prior consent from the Secretary of Homeland Security. Key provisions include raising maximum prison terms to 10 years for re-entry after prior removals linked to drug crimes, violent offenses, or multiple removals, and mandating a minimum 5-year sentence for those convicted twice of re-entry or of serious crimes before removal. The bill also clarifies that "removal" includes agreements made during criminal trials, expanding the scope of affected individuals.
Maddy summaryThis bill changes U.S. tax law by removing abortion expenses from the list of medical costs taxpayers can deduct. It specifically states that amounts paid for abortions cannot be counted toward medical expense deductions on federal tax returns, affecting individuals who pay for abortions and might have claimed them as deductible medical expenses. Exceptions apply for abortions needed to treat life-endangering physical conditions related to pregnancy, or in cases of rape or incest, as certified by a physician. The law would take effect for tax years beginning after its enactment. This is a tax policy change, not a restriction on abortion access.
Maddy summaryThis bill restricts health savings accounts (HSAs), Archer MSAs, health flexible spending accounts, and health reimbursement arrangements from covering most abortion expenses. It allows exceptions only for abortions resulting from rape or incest, or when a pregnancy poses a life-endangering risk to the woman (as certified by a physician). The law amends tax code provisions to exclude non-exempt abortion costs from being treated as qualified medical expenses for tax purposes. These changes take effect for taxable years beginning after December 31, 2025, directly affecting individuals using these specific tax-advantaged health accounts.