Issue · Budget & Taxes

Budget & Taxes (Sales Tax)

Every budget & taxes bill, vote, and legislator stance in Connecticut, automatically classified by Maddy, our AI policy reader.

Total bills
52
2026 Regular Session
Top supporter
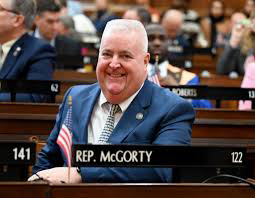
Ben McGorty
100% support rate
Top opponent
Aimee Berger-Girvalo
33% support rate
Ranked legislators
10
5 support · 5 oppose
Key legislators

Who's moving sales tax in Connecticut

Legislators moving sales tax in Connecticut
Legislator Party Stance Support rate Votes
Ben McGorty
Ben McGorty House · District 122
R
Strong +
100% 3
Bill Pizzuto
Bill Pizzuto House · District 71
R
Strong +
100% 3
Billy Buckbee
Billy Buckbee House · District 67
R
Strong +
100% 3
Brian Lanoue
Brian Lanoue House · District 45
R
Strong +
100% 3
Carol Hall
Carol Hall House · District 59
R
Strong +
100% 3
Aimee Berger-Girvalo
Aimee Berger-Girvalo House · District 111
D
Oppose
33% 3
Al Paolillo
Al Paolillo House · District 97
D
Oppose
33% 3
Amy Morrin Bello
Amy Morrin Bello House · District 28
D
Oppose
33% 3
Andre Baker
Andre Baker House · District 124
D
Oppose
33% 3
Anne Hughes
Anne Hughes House · District 135
D
Oppose
33% 3
Showing 21–30 of 52 bills

All budget & taxes bills

in committee · Connecticut · Senate Feb 4, 2026

SB 70: AN ACT EXEMPTING SOCIAL SECURITY BENEFITS AND PENSION OR ANNUITY INCOME FROM THE PERSONAL INCOME TAX.

SB 70 would exempt all Social Security benefits and pension or annuity income from state personal income tax for every taxpayer. This policy change directly affects residents receiving these income types, removing them from the taxable base. The bill amends Section 12-701 of the general statutes to implement this universal exemption. It creates a concrete tax relief measure without altering other income tax provisions.
signed · Connecticut · Senate May 26, 2026

SB 1: AN ACT MAKING ADJUSTMENTS TO THE STATE BUDGET FOR THE BIENNIUM ENDING JUNE 30, 2027, MAKING DEFICIENCY APPROPRIATIONS FOR THE FISCAL YEAR ENDING JUNE 30, 2026, AUTHORIZING AND ADJUSTING BONDS OF THE STATE AND CONCERNING PROVISIONS RELATING TO REVENUE, SCHOOL CONSTRUCTION AND OTHER ITEMS TO IMPLEMENT THE STATE BUDGET.

This bill removes sales tax on clothing under $100, school supplies, and appliances, and eliminates a 1% tax on meals sold by grocery stores. It creates new tax credits for homeowners (increasing the existing credit), caregivers of elderly or disabled family members, and renters earning $75,000 or less for primary residence costs. These changes directly lower tax burdens for Connecticut residents, particularly lower- and middle-income households. The bill modifies sales tax rules and expands income tax credits to improve affordability.
in committee · Connecticut · Senate Feb 17, 2026

SB 206: AN ACT EXEMPTING THE COST OF HEADSTONES UP TO A CERTAIN AMOUNT FROM THE SALES AND USE TAXES.

SB 206 exempts up to $2,500 of the cost of a headstone from state sales and use taxes. This directly affects individuals purchasing headstones for gravesites, reducing their out-of-pocket expenses. The bill amends tax law to exclude the first $2,500 spent on headstones from taxable sales, applying to all eligible headstone purchases. It creates a specific sales tax exemption for this item without altering broader tax policies.
in committee · Connecticut · House Feb 10, 2026

HB 5116: AN ACT REDUCING THE RATE OF THE SALES AND USE TAXES.

HB 5116 would reduce the state's sales and use tax rate from its current level to 6% by amending Chapter 219 of the general statutes. This change would directly affect all consumers purchasing taxable goods and services, as well as businesses collecting and remitting these taxes. The bill's key provision is the specific rate reduction to 6%, replacing the existing tax rate in the law. This is a straightforward policy change to lower the tax burden for everyday transactions.
in committee · Connecticut · House Feb 9, 2026

HB 5095: AN ACT EXEMPTING PET GROOMING SERVICES FROM THE SALES AND USE TAXES.

HB 5095 would remove sales tax from pet grooming services, directly affecting pet groomers and pet owners who pay for these services. The bill amends the state tax code (chapter 219) to exempt pet grooming as a taxable service, meaning businesses would no longer collect sales tax on this specific service. This change would lower costs for customers seeking pet grooming and simplify tax compliance for service providers. The bill focuses solely on the tax treatment of pet grooming, with no other policy changes or broader implications outlined.
in committee · Connecticut · Senate Feb 10, 2026

SB 106: AN ACT EXEMPTING DOG GROOMING SERVICES FROM THE SALES AND USE TAXES.

SB 106 would remove the sales and use tax from dog grooming services in the state. This change directly affects dog groomers (who would pay less tax on their services) and pet owners (who would pay less for grooming). The bill achieves this by amending the state tax code to specifically exempt dog grooming services from the standard sales tax.
in committee · Connecticut · House Feb 10, 2026

HB 5129: AN ACT ESTABLISHING A SURCHARGE ON HIGH-VALUE RECREATIONAL VESSELS AND CONCERNING THE USE OF THE REVENUE GENERATED.

HB 5129 would require owners of high-value recreational vessels (such as expensive boats and yachts) to pay an additional surcharge. The revenue generated from this surcharge would be dedicated to reducing and eliminating the property tax on motor vehicles, including cars and trucks. This bill directly affects vessel owners through a new fee and vehicle owners through potential tax relief, creating a funding mechanism to lower vehicle taxes by taxing a specific category of recreational boats.
in committee · Connecticut · Senate Feb 4, 2026

SB 73: AN ACT ESTABLISHING A NONREFUNDABLE PERSONAL INCOME TAX CREDIT FOR THE PURCHASE OF A GUN SAFE.

This bill establishes a nonrefundable personal income tax credit of up to $150 for individuals who purchase a gun safe for personal use. The credit reduces the amount of state income tax owed but cannot result in a refund if the credit exceeds the tax liability. It directly affects individual taxpayers who buy gun safes, providing a tax benefit for this specific purchase. The policy change creates a new tax incentive without altering firearm regulations or safety standards.
in committee · Connecticut · Senate Feb 4, 2026

SB 74: AN ACT ESTABLISHING A TAX CREDIT FOR DAIRY FARMERS.

SB 74 would create a $20 million state tax credit for dairy farmers to help offset income losses during periods when milk prices drop. The credit directly affects dairy farmers in the state who experience cyclical price fluctuations in milk sales. The bill establishes this tax credit as a fixed pool, meaning it would provide financial relief to eligible farmers when milk prices fall below certain levels. This is a direct policy change to support dairy farm revenue stability, not a procedural measure.
Sub-Topics Business Taxes Sales Tax Tax Credits Tags Agriculture
in committee · Connecticut · Senate Feb 4, 2026

SB 60: AN ACT CONCERNING THE SALES AND USE TAXES RATE.

This bill would lower Connecticut's general sales tax rate from 7% to 6% and eliminate a separate 1% tax on meals sold at restaurants, caterers, and grocery stores. It directly affects businesses selling taxable goods and meals, as well as consumers who pay these taxes. The key changes are reducing the overall sales tax rate and removing the additional tax specifically for food purchases. The bill aims to decrease the tax burden for these transactions.
Showing 21 to 30 of 52 bills
Previous 1 2 3 4 6 Next