

Issue · Budget & Taxes
Budget & Taxes (Sales Tax)
Every budget & taxes bill, vote, and legislator stance in Washington, automatically classified by Maddy, our AI policy reader.
Total bills
146
2025-2026 Regular Session
Top supporter
Andrew Engell
87% support rate
Top opponent
Zach Hall
11% support rate
Ranked legislators
10
5 support · 5 oppose
Key legislators
Who's moving sales tax in Washington
| Legislator | Party | Stance | Support rate | Votes |
|---|---|---|---|---|
Andrew Engell
House · District 7
|
R |
Strong +
|
87% | 79 |
Dave Stuebe
House · District 17
|
R |
Strong +
|
87% | 79 |
Gloria Mendoza
House · District 14
|
R |
Strong +
|
87% | 78 |
Mike Volz
House · District 6
|
R |
Strong +
|
87% | 52 |
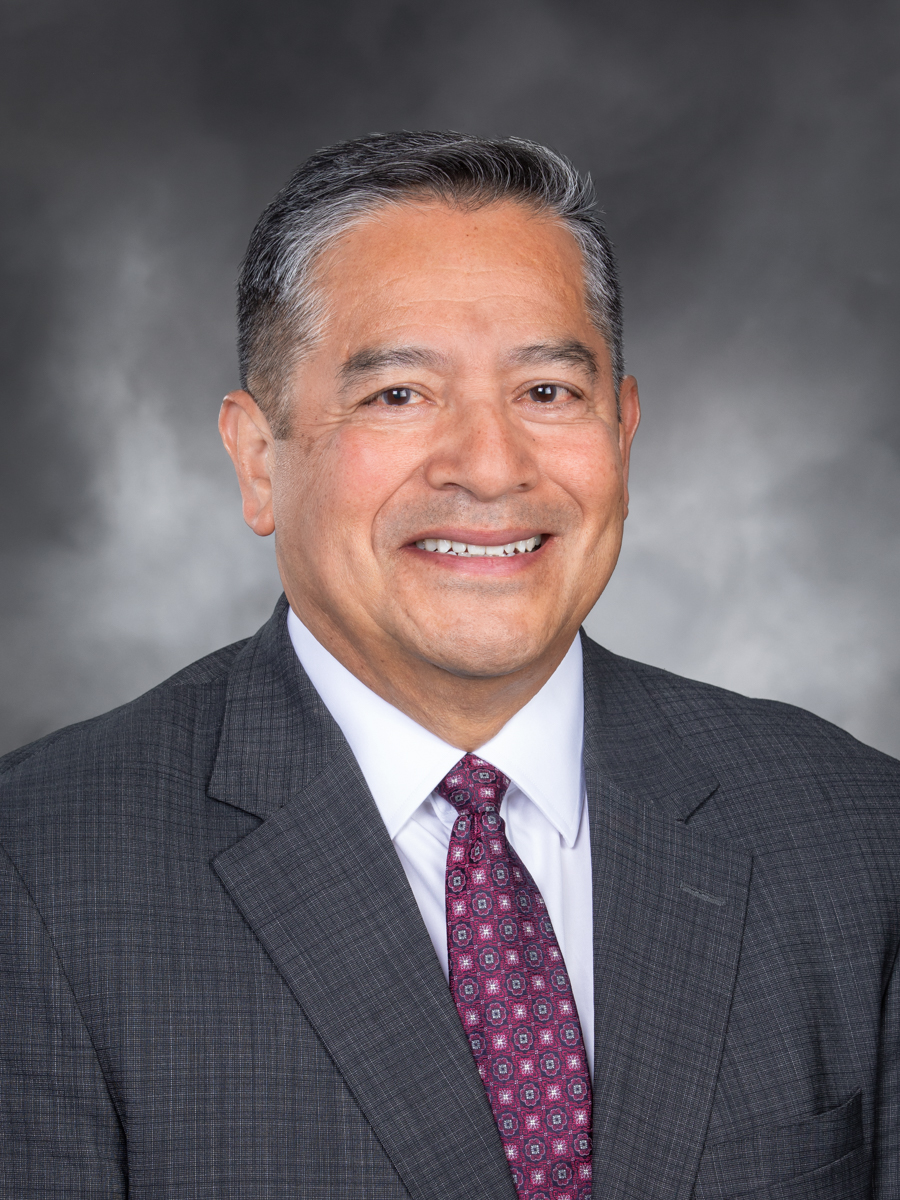
Alex Ybarra
House · District 13
|
R |
Strong +
|
86% | 79 |

Zach Hall
House · District 5
|
D |
Strong −
|
11% | 74 |
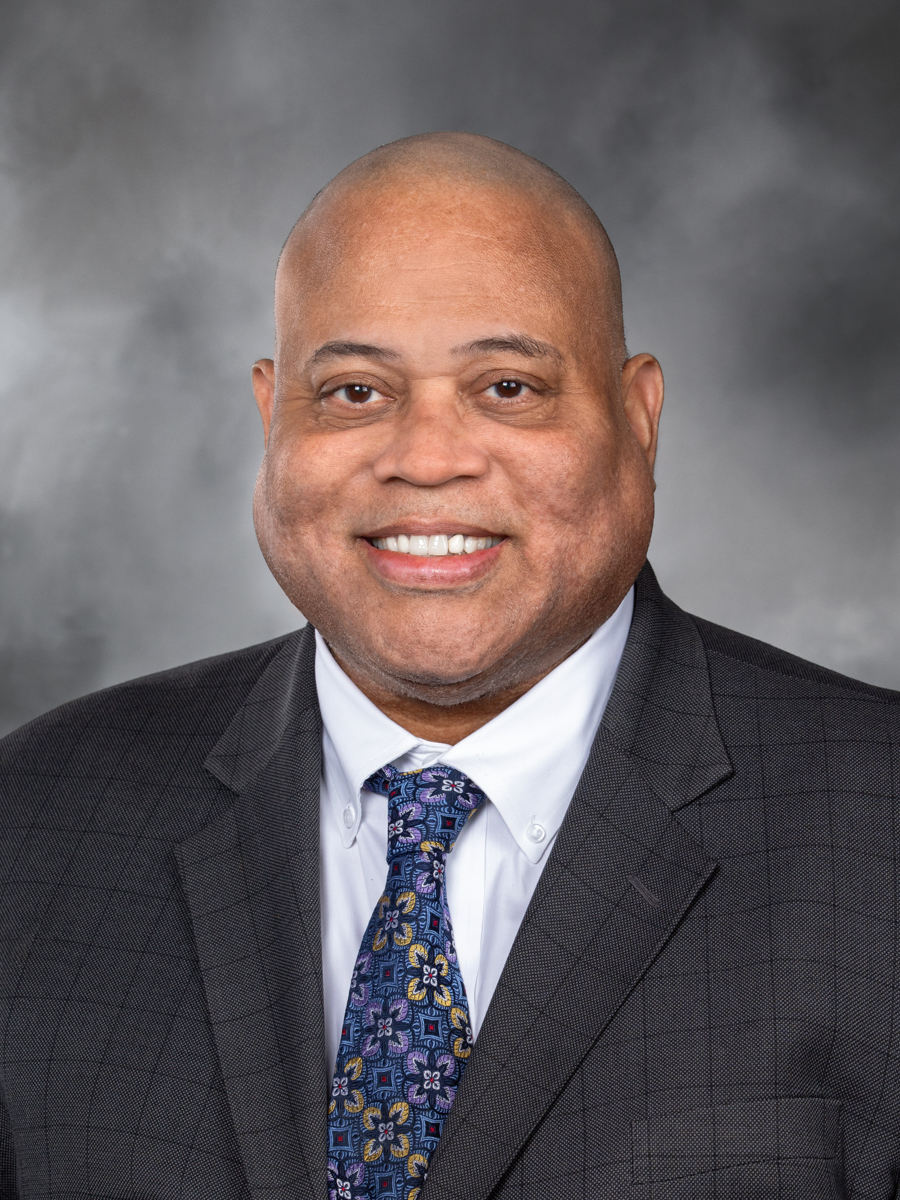
David Hackney
House · District 11
|
D |
Strong −
|
14% | 74 |
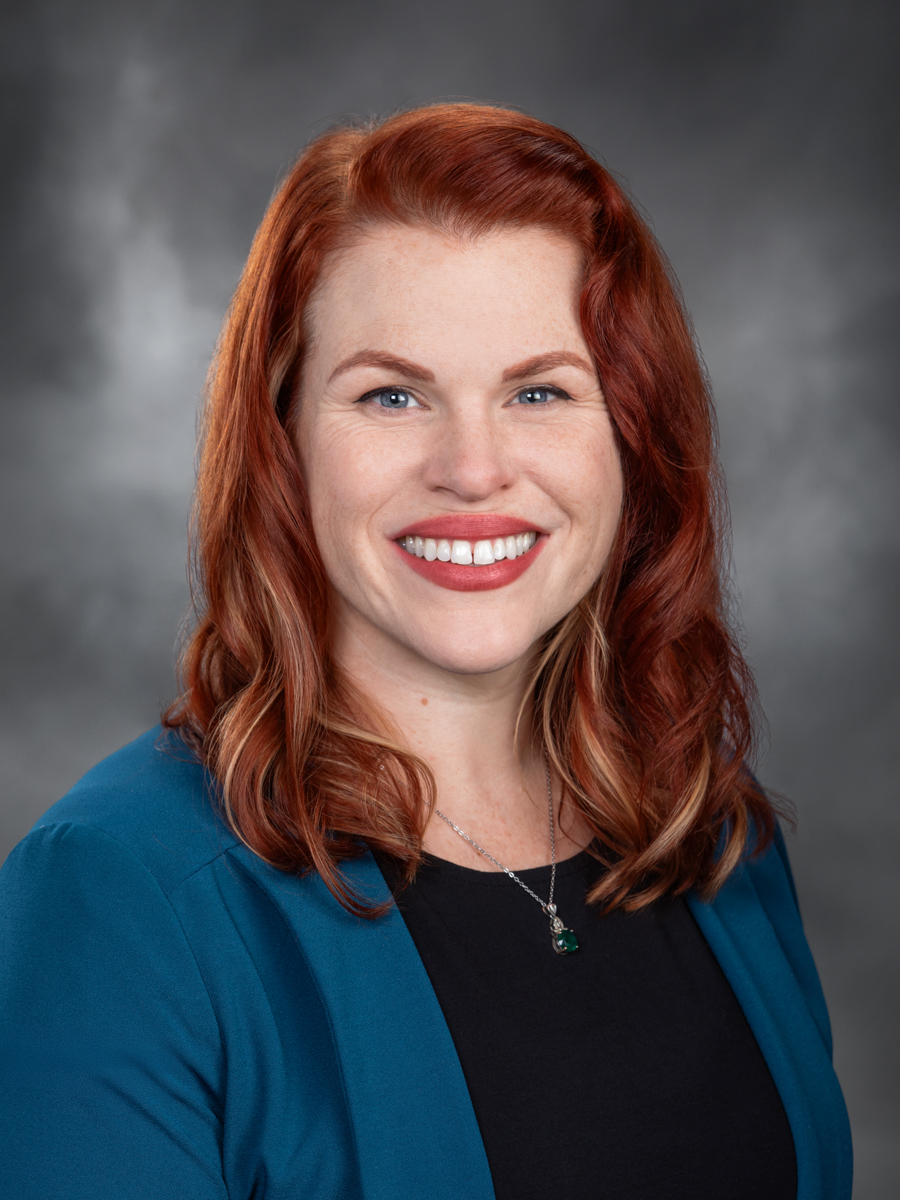
Mary Fosse
House · District 38
|
D |
Strong −
|
14% | 78 |
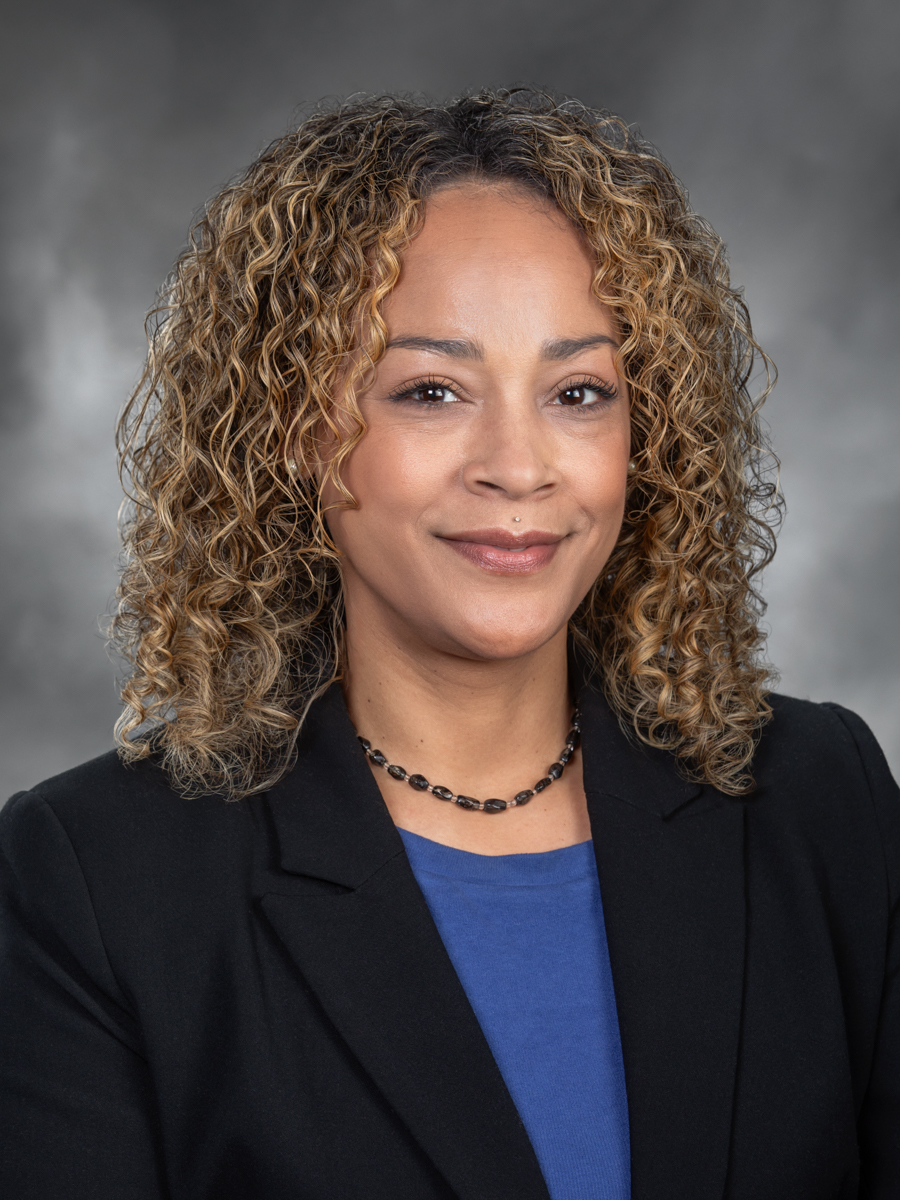
Natasha Hill
House · District 3
|
D |
Strong −
|
14% | 78 |
Timm Ormsby
House · District 3
|
D |
Strong −
|
14% | 77 |
Showing 31–40 of 146
bills
All budget & taxes bills
SB 6283: Providing a sales and use tax exemption for qualifying farm machinery and equipment.
SB 6280: Concerning the taxation of smoking cessation products.
Topics
✓ Budget & TaxesSupports Budget & TaxesExpands tax scope to include nicotine pouches, closing a loophole to increase state revenue through clearer tax collection on previously uncovered products.
✗ HealthcareOpposes HealthcareTaxing nicotine pouches (used for smoking cessation) increases cost of healthcare tools, potentially reducing access to cessation products, opposing healthcare goals of improving smoking cessation access.
SB 6297: Making temporary staffing services provided to nonprofit behavioral health entities exempt from retail sales tax.
Topics
✓ Budget & TaxesSupports Budget & TaxesBill exempts nonprofit behavioral health staffing from sales tax, reducing operational costs for essential mental health services. This tax relief supports public service funding and aligns with fiscal responsibility for community health programs.
✓ HealthcareSupports HealthcareExempts staffing costs for mental health nonprofits from sales tax, reducing operational costs and directly supporting behavioral health service delivery.
HB 2290: Exempting schools and school districts from retail sales and use tax.
Topics
✓ Budget & TaxesSupports Budget & TaxesExempts schools from sales/use taxes, providing direct tax relief and preserving district funds for educational purposes.
✓ EducationSupports EducationExempting schools from sales/use taxes directly increases available funds for educational programs and operations by removing a financial burden.
HB 2655: Providing a retail sales and use tax exemption for the construction and equipping of new data centers located in a county east of the Cascades that borders another state and has a population of at least 500,000.
Topics
✗ Budget & TaxesOpposes Budget & TaxesBill grants sales tax exemption for data centers, reducing state tax revenue. This weakens tax collection, aligning with 'oppose' indicators for tax reduction.
✓ Labor & EmploymentSupports Labor & EmploymentBill mandates family-wage job creation (35+ or 3 per 20k sq ft) as a condition for tax exemption, directly advancing employment standards and job quality.
✓ TechnologySupports TechnologyTax exemption directly incentivizes data center construction and infrastructure, advancing tech infrastructure development per bill's purpose.
SB 6211: Creating uniformity for the process by which cities planning under the growth management act implement real estate excise taxes.
Topics
✓ Budget & TaxesSupports Budget & TaxesStandardizes 0.25% real estate tax for capital projects (streets, parks, affordable housing), directing funds to public infrastructure per bill's explicit mandate.
✓ HousingSupports HousingBill mandates tax revenue use for affordable housing/homeless facilities per specific capital project requirements, directly funding housing initiatives.
HB 2359: Modifying requirements and allowed uses for certain funding related to providing and maintaining affordable housing and related services.
Topics
✓ Budget & TaxesSupports Budget & TaxesRedirects 0.1% sales tax revenue to fund affordable housing for low-income groups, mandating 60% allocation for housing/services and 15% reserved locally, strengthening fiscal support for housing programs.
✓ HealthcareSupports HealthcareBill requires 60% of funds for behavioral health facilities, explicitly supporting mental health services as part of healthcare policy.
✓ HousingSupports HousingRequires 60% of funds for low-income housing (≤60% AMI) including homeless/veterans/disabled, mandates 15% units for nearby residents, directly advancing affordable housing access.
✓ VeteransSupports VeteransBill requires 60% of funds for housing including veterans as eligible beneficiaries among low-income groups, explicitly targeting veteran housing needs.
HB 2126: Providing an exemption for taxes on fuel used in school buses.
Topics
✓ Budget & TaxesSupports Budget & TaxesExempts school districts from fuel tax, reducing public school operating costs - direct tax relief for essential public services per tax policy indicators.
✓ EducationSupports EducationExempts school districts from fuel tax, reducing operational costs and increasing available funds for education infrastructure and programs.
✓ TransportationSupports TransportationExempts school bus fuel tax, reducing operational costs for public school transportation services, directly supporting transportation infrastructure funding.
HB 2101: Exempting live presentations from retail sales and use tax.
Sub-Topics
Sales Tax