Issue · Budget & Taxes

Budget & Taxes (Revenue)

Every budget & taxes bill, vote, and legislator stance in Montana, automatically classified by Maddy, our AI policy reader.

Total bills
15
2025 Regular Session
Top supporter
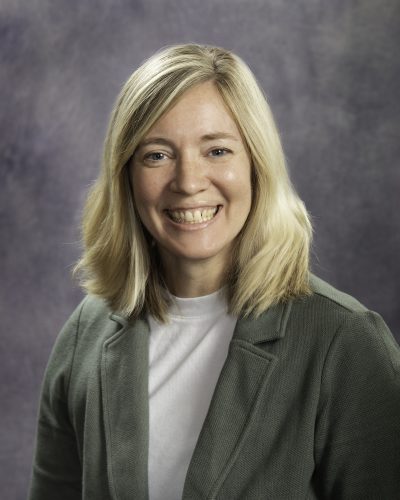
Becky Edwards
92% support rate
Top opponent
Steve Fitzpatrick
25% support rate
Ranked legislators
10
5 support · 5 oppose
Key legislators

Who's moving revenue in Montana

Legislators moving revenue in Montana
Legislator Party Stance Support rate Decisive votes
Becky Edwards
Becky Edwards House · District 61
D
Strong +
92% 13
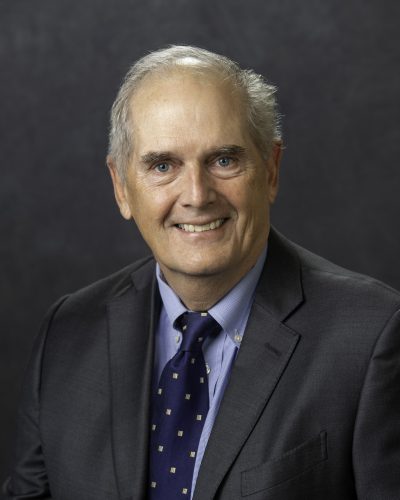
Chris Pope
Chris Pope Senate · District 33
D
Strong +
88% 25
Eric Matthews
Eric Matthews House · District 66
D
Strong +
88% 16
Derek Harvey
Derek Harvey Senate · District 37
D
Strong +
87% 23
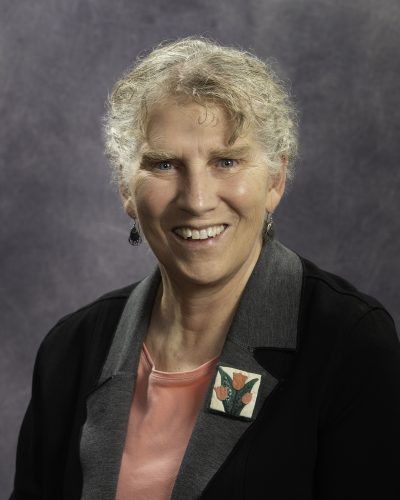
Janet Ellis
Janet Ellis Senate · District 41
D
Strong +
87% 23
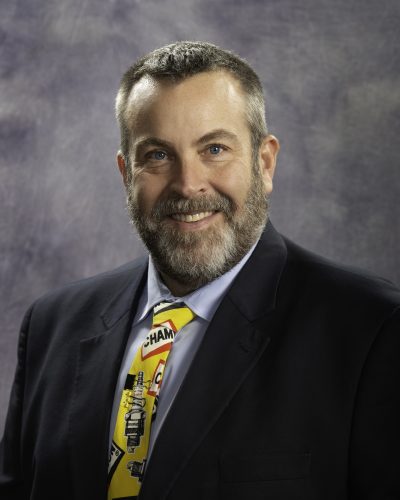
Steve Fitzpatrick
Steve Fitzpatrick House · District 24
R
Oppose
25% 16
Daniel Emrich
Daniel Emrich Senate · District 11
R
Oppose
30% 20
Brad Barker
Brad Barker House · District 55
R
Oppose
31% 16
Eric Albus
Eric Albus House · District 28
R
Oppose
31% 16
Kathy Love
Kathy Love House · District 85
R
Oppose
38% 13
Showing 1–10 of 15 bills

All budget & taxes bills

signed · Montana · House May 19, 2025

HB 876: Sawmill revitalization act

HB 876, the Sawmill Revitalization Act, creates a special state revenue account to support the reopening of closed sawmills. It transfers $6 million from the big sky economic development fund into this account. The Board of Investments will administer these funds, offering loans at an interest rate not exceeding 3% to parties with the capacity to return closed sawmills to commercial operation. Priority for these loans is given to sawmills that closed most recently. This act is effective July 1, 2025, and terminates on December 30, 2026.
Sub-Topics Revenue
signed · Montana · Senate Apr 4, 2025

SB 172: Revise resort tax eligibility and allow use for workforce housing

SB 172 allows Montana resort communities and areas (designated under state law with populations under 3,500 that rely heavily on tourism) to use an additional 1% resort tax - previously restricted to infrastructure - specifically for workforce housing. The bill amends tax code sections to explicitly permit this new allocation, alongside existing infrastructure uses, for communities that qualify under the defined criteria. It does not create new taxes but changes how existing resort tax revenue may be spent, directly affecting designated resort districts and communities. The policy shift aims to address housing needs for local workers in tourism-dependent areas.
vetoed · Montana · Senate Jul 11, 2025

SB 537: Generally revise marijuana tax laws

SB 537 revises Montana's marijuana tax revenue distribution, directing funds from the marijuana state special revenue account to new and existing state accounts. It requires transferring excess funds annually to specific accounts, including 12% to the HEART account for addiction treatment and mental health programs, 20% to wildlife habitat projects, and 14% to behavioral health initiatives. The bill also allocates funds for law enforcement canine training, sexual assault evidence kits, and homeless shelter support, while modifying existing transfer rules for agencies like the Department of Fish, Wildlife, and Parks. These changes apply to all state agencies receiving marijuana tax revenue under Montana law.
vetoed · Montana · House May 13, 2025

HB 880: Establish a stabilization fund for medicaid

HB 880 establishes the Medicaid Stabilization Reserve Account, a state special revenue fund designed to help maintain Medicaid benefits during state revenue shortfalls. The account would be primarily funded by transferring any unused state general fund appropriations for Medicaid at the end of a fiscal year. Funds from this account could only be appropriated by the legislature for state Medicaid matching funds after the budget director certifies a projected general fund deficit. This mechanism aims to mitigate expenditure reductions in the Medicaid program, directly affecting the stability of services for beneficiaries. The bill also includes an initial appropriation of $50,000 for state Medicaid matching funds.
died · Montana · Senate May 23, 2025

SB 171: Transfer a portion of ending fund balance into the coal trust fund

SB 171 requires that 10% of excess state general fund revenue, after meeting budget stability and capital projects fund thresholds, be transferred to the Montana coal severance tax permanent fund (coal trust fund). This bill amends Montana's budget law to direct a portion of surplus funds - specifically, funds exceeding established reserve levels - to the coal trust fund instead of remaining in the general fund. The transfer applies when the budget stabilization reserve fund and capital projects fund exceed 16% and 12% of general revenue appropriations, respectively. The coal trust fund, which supports coal-related programs, would receive this additional funding without altering the state's primary budget processes.
died · Montana · House May 20, 2025

HB 841: Constitutional amendment to use sales tax revenue for education

HB 841 proposed a constitutional amendment in Montana to change the allocation of state sales or use tax revenue. It would have required that revenue from a statewide sales tax, capped at 4%, be used primarily to reduce property taxes funding public schools and the Montana University System. The bill allowed for this revenue to be appropriated for other purposes if three-fourths of the legislature voted to do so. If approved by voters in November 2026, the amendment would have taken effect on July 1, 2027.
died · Montana · House Feb 27, 2025

HB 507: Constitutional amendment for sales tax to fund K-12 education

HB 507 is a proposed constitutional amendment that would allow Montana to implement a 4% statewide sales tax (and use tax) specifically to reduce property taxes funding K-12 public schools. If approved by voters, this tax revenue would replace some local property tax funding for schools, directly affecting Montana taxpayers and public school districts. The bill requires a two-thirds legislative vote for passage and voter approval in the November 2026 election, with an effective date of July 1, 2027 if adopted. The bill was withdrawn by the House on February 27, 2025, per procedural rules, and did not advance further.
Sub-Topics Revenue Sales Tax
signed · Montana · House Apr 7, 2025

HB 18: Deposit non-levy revenue in school equalization and property tax relief account

HB 18 redirects all revenue from bentonite mining taxes (collected after December 31, 2014) to a dedicated "school equalization and property tax relief account" instead of previous distribution rules. Specifically, 20.75% of this tax revenue must now fund school districts and reduce local property taxes, as amended in sections 15-39-110 and 20-9-331 of Montana law. The bill directly affects mineral producers who pay the tax and school districts that receive funding through the new account. This change applies to all bentonite mining revenue collected after 2014, shifting funds from prior county and state allocations to the equalization account.
Sub-Topics Revenue
died · Montana · Senate May 23, 2025

SB 307: Reallocate Montana marijuana tax revenue

SB 307 redirects Montana's marijuana tax revenue to fund prevention programs, law enforcement, and local grants. It creates a new marijuana prevention account to support primary substance misuse prevention and youth suicide prevention programs through community-based services. The bill establishes a marijuana tax revenue accountability council to advise on fund allocation and requires annual impact reports on public health metrics like youth access and hospitalizations. These funds, previously distributed differently, will now specifically target prevention services and law enforcement operations under new reporting rules.
Sub-Topics Revenue
died · Montana · Senate May 23, 2025

SB 90: Redistribute certain state tax revenue to primary residence property tax relief

SB 90 would provide property tax relief to Montana homeowners with primary residences by using lodging and rental car tax revenue. Homeowners would need to apply for certification by March 1, proving they live in the home at least 7 months yearly and that the property value is under $1 million. Counties would apply the credit directly to property tax bills using annual funding based on certified residences, with penalties for false applications. The bill specifies that assistance won’t affect local mill rates and requires Department of Revenue certification of eligible primary residences.
Showing 1 to 10 of 15 bills
1 2 Next