

To amend the Internal Revenue Code of 1986 to establish a refundable tax credit for individuals for amounts paid for gas and electricity for primary residences.
HR 615 creates a refundable tax credit for individuals covering up to $350 of gas and electricity costs paid directly to utilities for their primary residence. It applies to taxpayers with modified adjusted gross income under $400,000 for joint filers or $200,000 for single filers, excluding dependents and costs already covered by other credits. The bill requires landlords including utility costs in rent to provide annual receipts to tenants and the IRS. This credit directly affects homeowners and renters paying utility bills for their main residence, with the credit amount capped at $350 per year. It does not apply to secondary homes or utility costs covered elsewhere in tax law.
Bill status
in committee
1 of 4 stages cleared
Introduction
Jan 2025
Committee Review
Floor Vote
President
Introduced Jan 22, 2025
Last action Jan 22, 2025
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
2
Key actions
0
Committee
1
Jan 22, 2025
Committee
Referred to the House Committee on Ways and Means.
lower
Jan 22, 2025
Introduced
Introduced in House
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
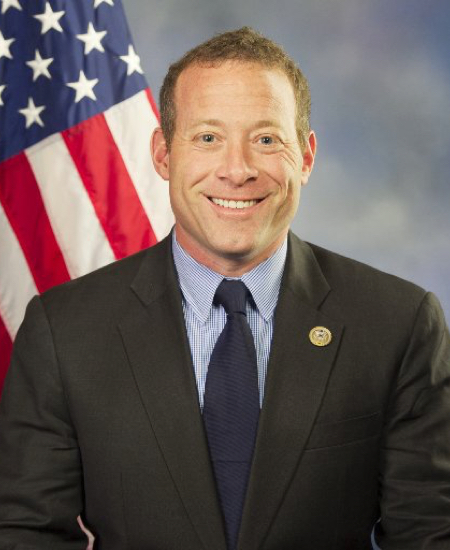
Josh Gottheimer
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about HR 615
Scope: US
Hi! I can help you understand HR 615. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline