

To amend the Internal Revenue Code of 1986 to increase the amount of the adoption credit and to establish the in vitro fertilization expenses credit.
HR 1427 increases the federal adoption tax credit from $10,000 to $25,000 per child for both general adoptions and adoptions of children with special needs, effective for tax years beginning after December 31, 2024. It also creates a new tax credit for qualified in vitro fertilization (IVF) medical expenses, allowing taxpayers to claim a credit for IVF-related costs paid during the tax year. The bill includes a new inflation adjustment mechanism for the adoption credit starting in 2025 and specifies that IVF credit expenses cannot be claimed for other deductions or credits. This legislation directly affects individuals adopting children or undergoing IVF treatments who itemize deductions on their federal tax returns.
Bill status
in committee
1 of 4 stages cleared
Introduction
Feb 2025
Committee Review
Floor Vote
President
Introduced Feb 18, 2025
Last action Feb 18, 2025
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
2
Key actions
0
Committee
1
Feb 18, 2025
Committee
Referred to the House Committee on Ways and Means.
lower
Feb 18, 2025
Introduced
Introduced in House
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
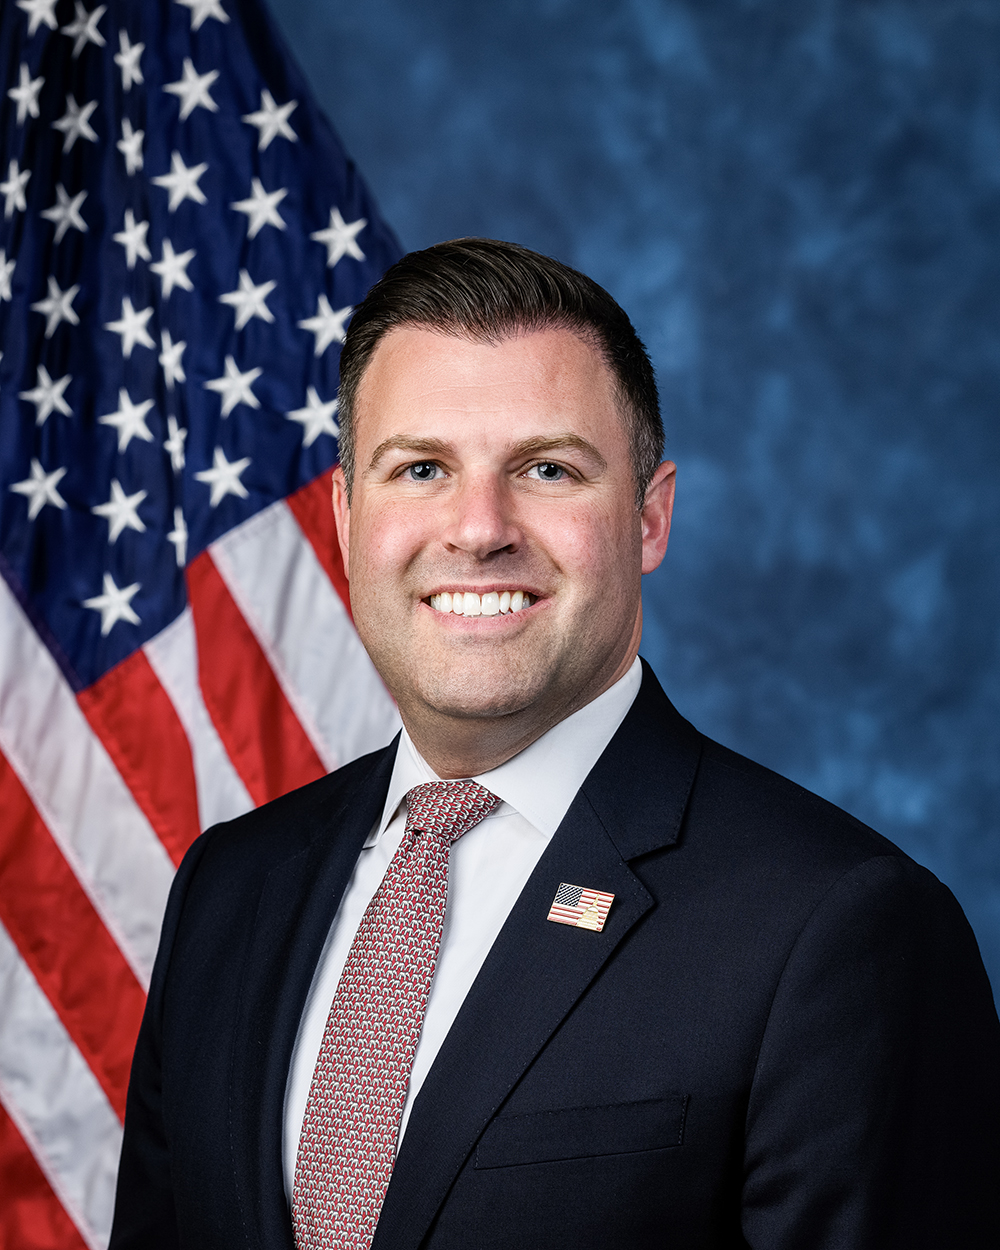
Ryan Mackenzie
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about HR 1427
Scope: US
Hi! I can help you understand HR 1427. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline