

Small Business Investment Act of 2025
This bill modifies tax rules for investors in qualified small business stock. It reduces the required holding period from 5 years to 3 years and creates a phased exclusion scale: 50% of gains excluded after 3 years, 75% after 4 years, and 100% after 5+ years. The changes directly affect investors who buy stock in qualifying small businesses, making capital gains tax exclusion more accessible. Key mechanisms include updating Internal Revenue Code Section 1202 to reflect the shorter holding period and revised exclusion percentages, while also clarifying rules for S corporations and convertible debt instruments. These adjustments aim to incentivize investment in small businesses by lowering the tax barrier for holding qualifying stock.
Bill status
in committee
1 of 4 stages cleared
Introduction
Feb 2025
Committee Review
Floor Vote
President
Introduced Feb 11, 2025
Last action Feb 11, 2025
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
2
Key actions
0
Committee
1
Feb 11, 2025
Committee
Referred to the House Committee on Ways and Means.
lower
Feb 11, 2025
Introduced
Introduced in House
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
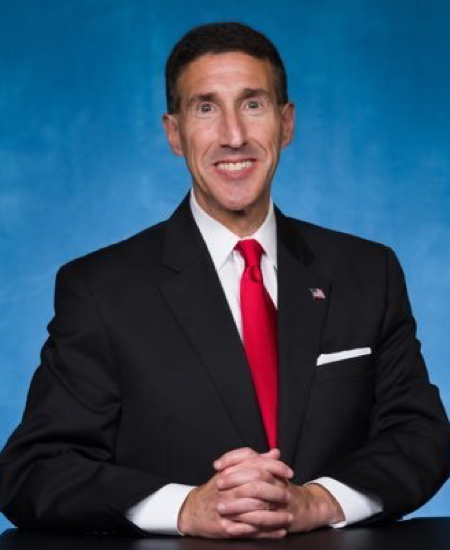
David Kustoff
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about HR 1199
Scope: US
Hi! I can help you understand HR 1199. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline