

Personal Income Tax Law: deferred compensation: exclusions: long-term qualified tuition program.
Summary
The Personal Income Tax Law, in conformity with federal income tax law, generally defines "gross income" as income from whatever source derived, except as specifically excluded, and provides various exclusions from gross income. Existing law, known as the Golden State Scholarshare Trust Act, establishes the Golden State Scholarshare College Savings Trust (Scholarshare trust) , under the administration of the Scholarshare Investment Board, to provide financial aid for postsecondary education costs of participating students. Existing state and federal law generally includes in gross income distributions from a qualified tuition program, as defined to include the Scholarshare trust, except as provided. Existing federal law, the Consolidated Appropriations Act, 2023, excludes from gross income, for federal income tax purposes, distributions from a qualified tuition program that are made after December 31, 2023, and are paid in a direct trustee-to-trustee transfer to a Roth IRA, as described. This bill would exempt from gross income distribution made from a long-term qualified tuition program during the taxable years beginning on or after January 1, 2025, and before January 1, 2030, that are paid in a direct trustee-to-trustee transfer to a Roth IRA, and would conform state tax law to those changes relating to federal law, as described above. Existing law requires a bill authorizing a new tax expenditure to contain, among other things, specific goals, purposes, and objectives the tax expenditure will achieve, detailed performance indicators, and data collection requirements. This bill would include additional information required for any bill authorizing a new tax expenditure. This bill would take effect immediately as a tax levy.
Bill status
failed
1 of 4 stages cleared
Introduction
Feb 2025
Committee Review
Floor Vote
Governor
Introduced Feb 20, 2025
Last action Feb 2, 2026
Maddy AI version diff · 2 comparisons
What changed between versions
02/20/25 - Introduced
→
04/29/25 - Amended Senate
·
2 edits
·
Apr 29, 2025
MINOR
SB 657 was amended in the Senate primarily to add coauthors and include a statement that no data will be collected or reported for the tax expenditure analysis of the Roth IRA rollover exclusion. The core policy - exempting from California gross income distributions from long-term qualified tuition programs (529 plans) transferred directly to Roth IRAs during taxable years 2025 through 2029 - remains unchanged. The amendment is largely technical and administrative.
TECHNICAL
Added a statement in both Section 17140(g)(3) and Section 17140.3(e)(3) that 'there is no available data to collect or report with respect to the exclusion,' addressing the Section 41 tax expenditure analysis requirement by clarifying the state will not track usage of this exclusion.
Added Senate coauthors (Choi, Jones, Ochoa Bogh, Strickland, Valladares) and Assembly coauthors (Alanis, Chen, Hadwick, Wilson), indicating broader legislative support for the bill.
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
11
Key actions
3
Committee
3
Amendments
1
May 23, 2025
Upper · Passed
May 23 hearing: Held in committee and under submission.
upper
May 14, 2025
Upper · Passed
From committee: Do pass and re-refer to Com. on APPR. (Ayes 4. Noes 0. Page 1083.) (May 14). Re-referred to Com. on APPR.
upper
Apr 29, 2025
Upper · Passed
From committee with author's amendments. Read second time and amended. Re-referred to Com. on REV. & TAX.
upper
Mar 5, 2025
Committee
Referred to Com. on REV. & TAX.
upper
Feb 20, 2025
Introduced
Introduced. Read first time. To Com. on RLS. for assignment. To print.
upper
1 primary · 10 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
Roger Niello
RRepublican
Co

Brian Jones
RRepublican
Co
Greg Wallis
RRepublican
Co
Heather Hadwick
RRepublican
Co
Juan Alanis
RRepublican
Co
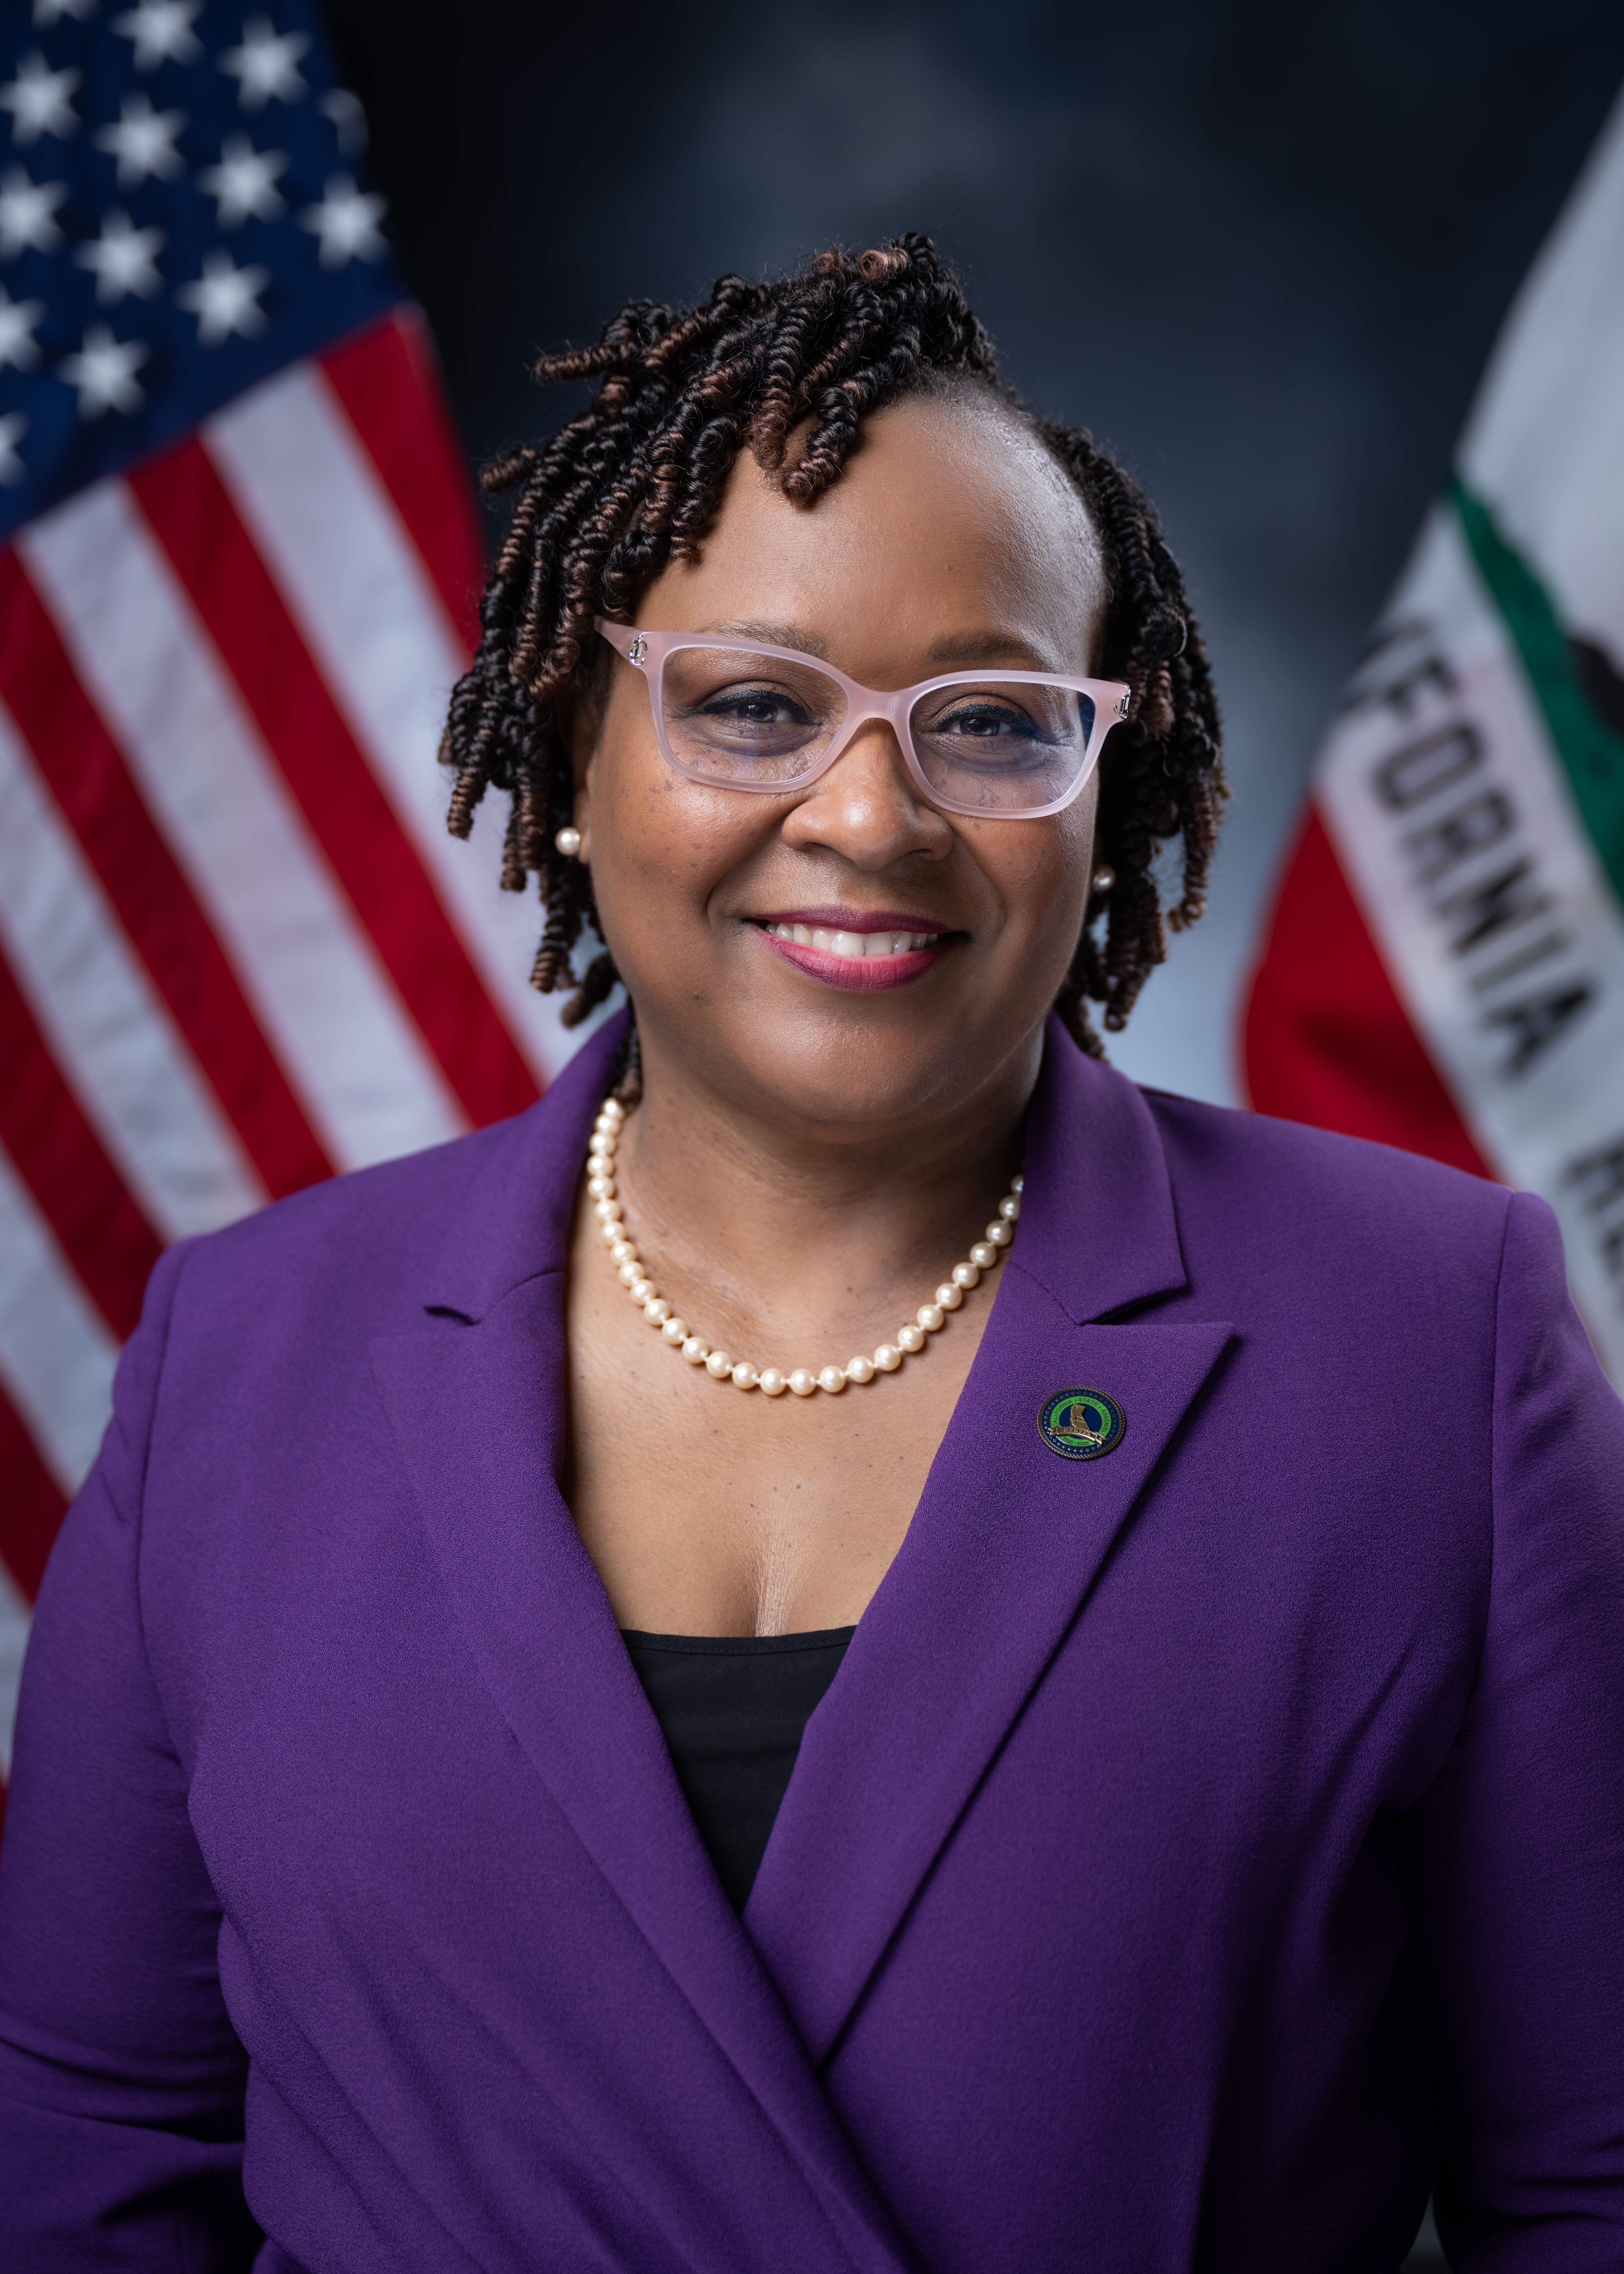
Lori Wilson
DDemocratic
Co
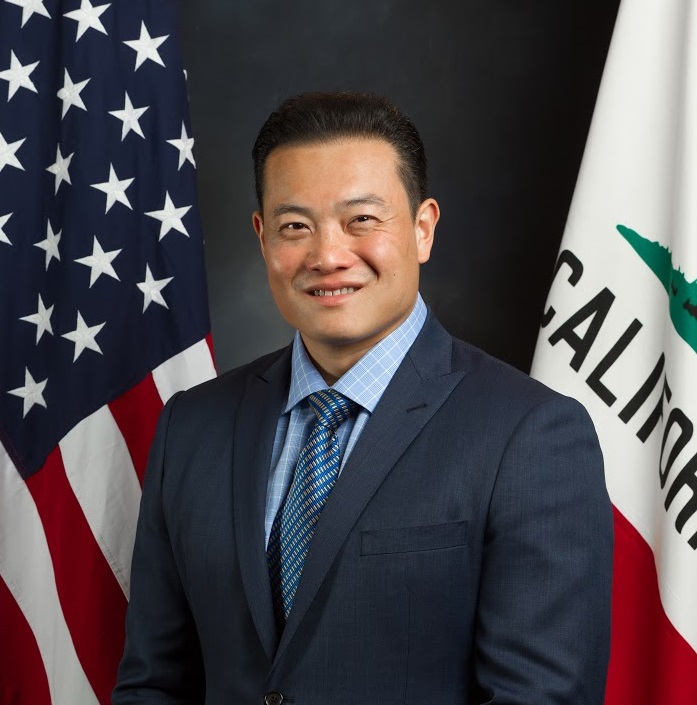
Phillip Chen
RRepublican
Co
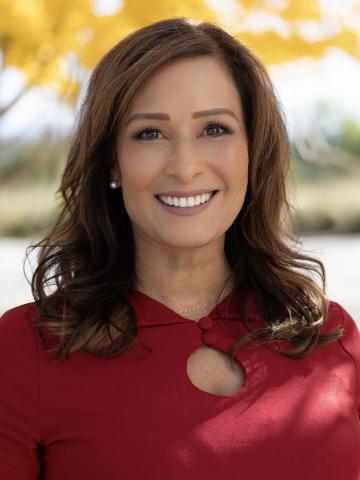
Rosilicie Ochoa Bogh
RRepublican
Co
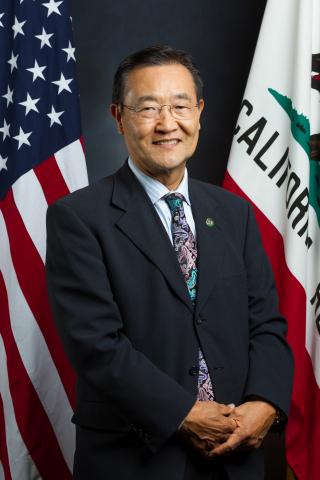
Steve Choi
RRepublican
Co
Suzette Valladares
RRepublican
Co
Tony Strickland
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about SB 657
Scope: CA
Hi! I can help you understand SB 657. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline