

Income taxes: credits: rehabilitation of certified historic structures.
Summary
The Personal Income Tax Law and the Corporation Tax Law allow a credit against the taxes imposed by those laws, for taxable years beginning on or after January 1, 2021, and before January 1, 2027, for rehabilitation of certified historic structures, as defined, and, under the Personal Income Tax Law, for a qualified residence, as defined. Existing law allows an increased credit of 25% of the qualified rehabilitation expenditures with respect to a certified historic structure meeting any of certain criteria, including a rehabilitated structure that includes affordable housing for lower income households. Existing law requires a taxpayer to receive an allocation from the California Tax Credit Allocation Committee (CTCAC) to be eligible for the credit. Existing law limits the aggregate amount of money that can be allocated for these credits per calendar year. Existing law requires, on an annual basis beginning January 1, 2021, until January 1, 2027, the Legislative Analyst to collaborate with the CTCAC and the State Office of Historic Preservation to review the effectiveness of these tax credits, as described. This bill would require the Legislative Analyst to submit a review of the effectiveness of the tax credits for taxable years beginning on or after January 1, 2025, and before January 1, 2027, to the Legislature, as specified. This bill, for taxable years beginning on or after January 1, 2027, and before January 1, 2032, would enact a similar credit against the taxes imposed by the Personal Income Tax Law and the Corporation Tax Law for the rehabilitation of certified historic structures, as provided. The bill, for tax credits allocated for those taxable years, would remove the above-described increased credit of 25% and would remove the credit for a qualified residence. The bill would also remove the limit on the amount of money that can be allocated per calendar year, and would instead require the limit to be set by the Legislature in the annual Budget Act or another measure. The bill would provide additional requirements relating to the manner in which the credits are allocated. Existing law requires any bill authorizing a new tax expenditure, as defined, to include exclusions from income, to contain, among other things, specific goals, purposes, and objectives that the tax credit will achieve, detailed performance indicators, and data collection requirements. This bill would include findings and reporting requirements in compliance with this requirement. This bill would take effect immediately as a tax levy.
Bill status
passed both
4 of 5 stages cleared
Introduction
Feb 2025
Committee Review
Aug 2026
Assembly Passage
Jan 2026
Senate Passage
Aug 2026
Governor
Introduced Feb 21, 2025
Last action Aug 25, 2026
Maddy AI version diff · 6 comparisons
What changed between versions
08/27/26 - Enrolled
→
AB1265
·
3 edits
MINOR
The diff reflects a change from the formal enrolled bill document format to a web page rendering of the same bill text on the California Legislature's website. No substantive policy changes were made; the statutory language is identical in both versions.
TECHNICAL
The document was reformatted from a formal enrolled legislative document (with page numbers, chapter headings, and 'An act to amend' preamble) into a web page display format with navigation menus, metadata, and status information.
Web page elements were added including navigation links (home, accessibility, FAQ, sitemap, login), bill tracking features, version history, and publication metadata (date published: 08/27/2026).
Formal legislative document elements were removed including page numbers, chapter designations, the 'An act to amend' preamble line, and the Legislative Counsel's Digest header formatting.
Floor votes · Senate Aug 20, 2026 · Assembly Jan 26, 2026
How they voted
39–0
Passed · 1 other
Total votes 40
Aug 20, 2026
D
Democratic30
96% Yea
R
Republican10
100% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
31
Key actions
10
Committee
14
Amendments
8
Aug 25, 2026
Lower · Passed
Senate amendments concurred in. To Engrossing and Enrolling. (Ayes 78. Noes 0.).
lower
Aug 20, 2026
Introduced
In Assembly. Concurrence in Senate amendments pending.
lower
Aug 20, 2026
Upper · Passed
Read third time. Passed. Ordered to the Assembly. (Ayes 39. Noes 0.).
upper
Aug 13, 2026
Upper · Passed
From committee: Do pass. (Ayes 7. Noes 0.) (August 13).
upper
Aug 3, 2026
Committee
In committee: Referred to APPR. suspense file.
upper
Jun 25, 2026
Upper · Passed
Read second time and amended. Re-referred to Com. on APPR.
upper
Jun 24, 2026
Introduced
From committee: Amend, and do pass as amended and re-refer to Com. on APPR. (Ayes 4. Noes 0.) (June 24).
upper
Jun 3, 2026
Upper · Passed
In committee: Set, first hearing. Hearing canceled at the request of author.
upper
May 6, 2026
Committee
Referred to Com. on REV. & TAX.
upper
Jan 26, 2026
Lower · Passed
Read third time. Passed. Ordered to the Senate. (Ayes 73. Noes 0. Page 3836.)
lower
Jan 22, 2026
Lower · Passed
From committee: Do pass. (Ayes 15. Noes 0.) (January 22).
lower
Jan 22, 2026
Committee
In committee: Set, first hearing. Referred to suspense file.
lower
Jan 20, 2026
Committee
Re-referred to Com. on APPR.
lower
Jan 16, 2026
Lower · Passed
Read second time and amended.
lower
Jan 15, 2026
Introduced
From committee: Amend, and do pass as amended and re-refer to Com. on APPR. (Ayes 5. Noes 0.) (January 12).
lower
Jan 6, 2026
Committee
Re-referred to Com. on REV. & TAX.
lower
Jan 5, 2026
Introduced
From committee chair, with author's amendments: Amend, and re-refer to Com. on REV. & TAX. Read second time and amended.
lower
May 5, 2025
Committee
In committee: Set, first hearing. Referred to REV. & TAX. suspense file.
lower
Apr 21, 2025
Committee
Re-referred to Com. on REV. & TAX.
lower
Apr 10, 2025
Introduced
From committee chair, with author's amendments: Amend, and re-refer to Com. on REV. & TAX. Read second time and amended.
lower
Apr 9, 2025
Lower · Passed
From committee: Do pass and re-refer to Com. on REV. & TAX. with recommendation: To Consent Calendar. (Ayes 12. Noes 0.) (April 9). Re-referred to Com. on REV. & TAX.
lower
Mar 17, 2025
Committee
Re-referred to Coms. on H. & C.D. and REV. & TAX. pursuant to Assembly Rule 96.
lower
Mar 13, 2025
Committee
Referred to Coms. on REV. & TAX. and H. & C.D.
lower
Feb 22, 2025
Lower · Passed
From printer. May be heard in committee March 24.
lower
Feb 21, 2025
Introduced
Introduced. To print.
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
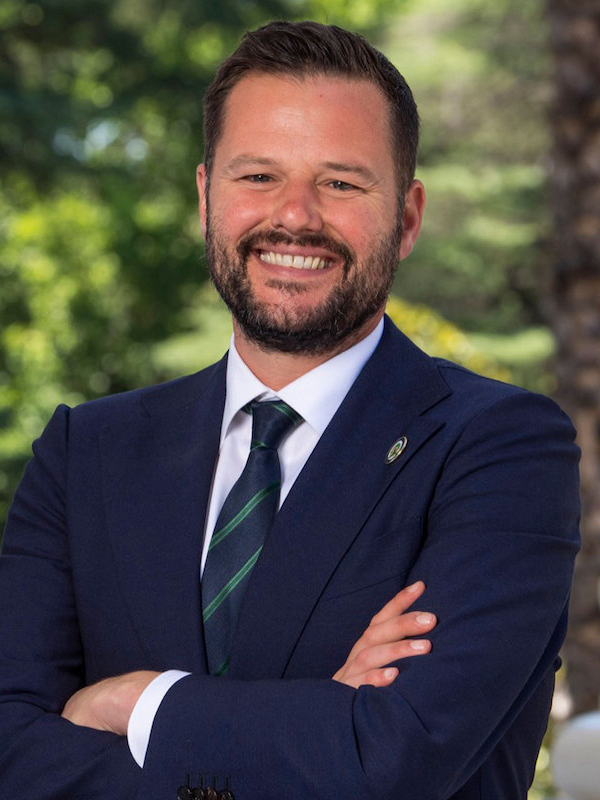
Matt Haney
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about AB 1265
Scope: CA
Hi! I can help you understand AB 1265. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline