

Personal Income Tax Law: Small Business Relief Act: elective tax.
Summary
Existing law, the Small Business Relief Act, for taxable years beginning on or after January 1, 2021, and before January 1, 2026, authorizes a partnership or "S" corporation that meets certain other requirements to elect to pay an elective tax at a rate based on its net income, as specified, for the taxable year. The Personal Income Tax Law allows various credits against the taxes imposed by that law, including a credit against the personal income tax to a taxpayer, other than a partnership, that is a partner, shareholder, or member of an entity that elects to pay the elective tax authorized by the Small Business Relief Act, in an amount equal to a specified percentage of the partner's, shareholder's, or member's pro rata share or distributive share, as applicable, of income subject to the elective tax paid by the entity. The Personal Income Tax Law provides a credit against the taxes imposed by that law, not to exceed the net tax, as defined, payable under that law, to residents for specified taxes paid to another state on income derived from sources within that state. This bill would, for taxable years beginning on or after January 1, 2022, and before January 1, 2026, increase the maximum credit allowed to residents for specified taxes paid to another state by the amount by which their net tax, as defined, is decreased by the credit allowed to a partner, shareholder, or member of an entity that elects to pay the elective tax authorized by the Small Business Relief Act. This bill would also make a nonsubstantive change to the Small Business Relief Act. Existing law requires any bill authorizing a new tax expenditure to contain, among other things, specific goals, purposes, and objectives that the tax expenditure will achieve, detailed performance indicators, and data collection requirements. This bill would state that the requirement for additional information in a bill authorizing a new tax expenditure does not apply in this case. This bill would take effect immediately as a tax levy.
Bill status
signed
all 5 stages cleared
Introduction
Jan 2022
Committee Review
Aug 2022
Senate Passage
May 2022
Assembly Passage
Aug 2022
Signed into Law
Sep 2022
Introduced Jan 18, 2022
Signed Sep 28, 2022
Floor votes · Senate May 26, 2022 · Assembly Sep 1, 2022
How they voted
35–0
Passed · 2 other
Total votes 37
May 26, 2022
D
Democratic29
96% Yea
R
Republican8
87% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
34
Key actions
13
Committee
7
Amendments
6
Sep 28, 2022
Signed into law
Approved by the Governor.
legislature
Sep 1, 2022
Assembly · Passed
Assembly Vote: pass (75-0-2)
assembly
Aug 31, 2022
Upper · Passed
Assembly amendments concurred in. (Ayes 40. Noes 0. Page 5412.) Ordered to engrossing and enrolling.
upper
Aug 31, 2022
Introduced
In Senate. Concurrence in Assembly amendments pending.
upper
Aug 31, 2022
Lower · Passed
Read third time. Passed. Ordered to the Senate.
lower
Aug 30, 2022
Lower · Passed
From committee: Do pass. (Ayes 9. Noes 0.) (August 30).
lower
Aug 25, 2022
Committee
Re-referred to Com. on REV. & TAX. pursuant to Assembly Rule 77.2.
lower
Aug 25, 2022
Lower · Passed
Read third time and amended.
lower
Aug 11, 2022
Lower · Passed
From committee: Do pass. (Ayes 16. Noes 0.) (August 11).
lower
Jun 22, 2022
Lower · Passed
From committee: Do pass and re-refer to Com. on APPR. (Ayes 12. Noes 0.) (June 21). Re-referred to Com. on APPR.
lower
Jun 2, 2022
Committee
Referred to Com. on HIGHER ED.
lower
May 26, 2022
Upper · Passed
Read third time. Passed. (Ayes 38. Noes 0. Page 3983.) Ordered to the Assembly.
upper
May 19, 2022
Upper · Passed
Read second time and amended. Ordered to second reading.
upper
May 19, 2022
Upper · Passed
From committee: Do pass as amended. (Ayes 7. Noes 0. Page 3771.) (May 19).
upper
Mar 9, 2022
Upper · Passed
From committee: Do pass and re-refer to Com. on APPR. (Ayes 7. Noes 0. Page 3060.) (March 9). Re-referred to Com. on APPR.
upper
Feb 23, 2022
Upper · Passed
From committee with author's amendments. Read second time and amended. Re-referred to Com. on ED.
upper
Jan 26, 2022
Committee
Referred to Com. on ED.
upper
Jan 18, 2022
Introduced
Introduced. Read first time. To Com. on RLS. for assignment. To print.
upper
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
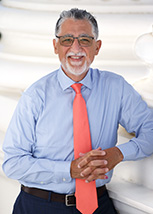
Anthony Portantino
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about SB 851
Scope: CA
Hi! I can help you understand SB 851. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline