

Relating to valuation of farm property
SB 898 modifies how certain agricultural buildings on qualified farmland are taxed. Beginning January 1, 2027, these buildings (like barns, silos, and chicken houses) will be assessed at their salvage value for property tax purposes. Starting January 1, 2029, such buildings will no longer be included in property tax assessments at all. The bill directly affects farmers who own qualifying agricultural structures, reducing their property tax burden over time. This change applies only to buildings used solely for agricultural production or storage, not to residential or commercial properties.
Bill status
in committee
1 of 4 stages cleared
Introduction
Feb 2026
Committee Review
Floor Vote
Governor
Introduced Feb 10, 2026
Last action Feb 25, 2026
Maddy AI version diff · 1 comparison
What changed between versions
Introduced Version
→
Committee Substitute
·
4 edits
MODERATE
The bill was amended to expand its scope by adding a new co-sponsor and updating the legislative history. The core policy change involves shifting the statutory citation from the general real property article to a specific farm property article. The substantive provisions regarding the valuation of agricultural buildings at salvage value and their eventual removal from tax rolls remain consistent in intent, though the specific dates (2027 and 2029) and the definition of salvage value are now embedded within the new farm property article.
Scope change
The bill's scope was technically narrowed and clarified by moving from a general real property assessment article to a dedicated farm property article, while adding a definition of who qualifies as a farmer.
ELIGIBILITY
Added a specific definition stating that a person is not engaged in farming if they are primarily engaged in forestry or growing timber, and clarified rules for corporate farming entities.
TECHNICAL
Changed the statutory citation from Article 4 (Assessment of Real Property) to Article 1A (Appraisal of Property) and updated the section number from 11-4-10 to 11-1A-10.
TIMELINE
Replaced the detailed introductory text about the bill's purpose with a concise note, while retaining the effective dates of January 1, 2027, for salvage valuation and January 1, 2029, for tax removal.
DEFINITION
Added a specific definition of 'salvage value' as the lower of fair market salvage value or five percent of the original cost of the property.
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
6
Key actions
0
Committee
4
Feb 25, 2026
Committee
To Finance
upper
Feb 25, 2026
Committee
Committee substitute reported, but first to Finance
upper
Feb 10, 2026
Committee
To Agriculture
upper
Feb 10, 2026
Introduced
Introduced in Senate
upper
Feb 10, 2026
Committee
To Agriculture then Finance
upper
1 primary · 2 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
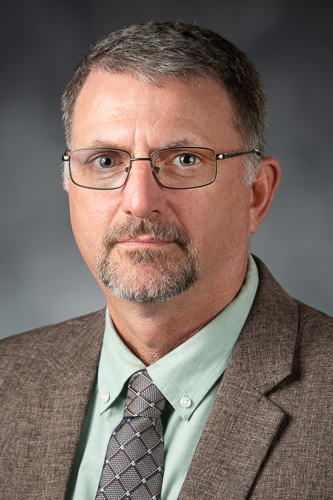
Darren Thorne
RRepublican
Co
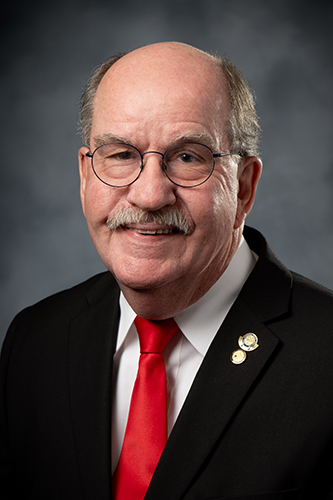
Bill Hamilton
RRepublican
Co
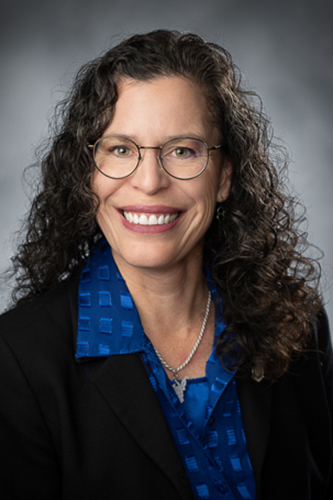
Patricia Rucker
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about SB 898
Scope: WV
Hi! I can help you understand SB 898. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline