

Relating to requirements for disclosures and recordkeeping by persons making mortgage loans
This bill updates West Virginia's mortgage lending laws to strengthen consumer protections and improve transparency for borrowers. It requires lenders and brokers to provide detailed closing statements that clearly show late payment penalty maximums and must include the borrower's signature, ensuring they understand the loan terms before finalizing the agreement. The bill also mandates that loan records be kept for 36 months and allows borrowers to request account statements and payoff information within specific timeframes without fees, except for third-party delivery costs. Additionally, it clarifies that a separate state-specific closing disclosure is not needed if the federal closing disclosure already contains all required information, reducing paperwork while maintaining compliance with state and federal standards.
Bill status
signed
all 5 stages cleared
Introduction
Jan 2026
Committee Review
Mar 2026
Senate Passage
Feb 2026
House of Delegates Passage
Mar 2026
Signed into Law
Jun 2026
Introduced Jan 22, 2026
Signed Jun 25, 2026
Maddy AI version diff · 2 comparisons
What changed between versions
Committee Substitute
→
Enrolled Committee Substitute
·
3 edits
·
Mar 25, 2026
MINOR
The bill was finalized and enacted into law, changing its status from a committee draft to an official enrolled version effective 90 days after passage. A key substantive change simplifies the closing disclosure requirements by removing the specific reference to 'HUD 1 or HUD 1A' forms, relying instead on the broader federal TRID rules. The bill also adds standard legislative certification and signature lines required for a bill to become law.
Scope change
The bill's scope remains focused on mortgage loan disclosures and recordkeeping in West Virginia, but the specific form references for closing statements were broadened to align strictly with federal TRID rules.
REQUIREMENT
Removed the specific requirement to provide a 'HUD 1 or HUD 1A settlement statement,' replacing it with a general reference to the federal TRID closing disclosure to simplify compliance.
TIMELINE
Added the effective date provision, stating the law takes effect 90 days from passage (June 10, 2026).
TECHNICAL
Added standard enrolled bill certification text, signature lines for legislative officers, and the Governor's signature block.
Floor votes · Senate Feb 3, 2026 · House of Delegates Mar 12, 2026
How they voted
33–0
Passed
Total votes 33
Feb 3, 2026
D
Democratic2
100% Yea
R
Republican31
100% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
33
Key actions
7
Committee
5
Mar 25, 2026
Signed into law
Approved by Governor 3/25/2026
upper
Mar 14, 2026
Signed into law
Approved by Governor 3/25/2026 - House Journal
lower
Mar 14, 2026
Signed into law
Approved by Governor 3/25/2026 - Senate Journal
upper
Mar 12, 2026
Lower · Passed
Passed House (Roll No. 426)
lower
Mar 10, 2026
Lower · Passed
Do pass
lower
Feb 4, 2026
Committee
To House Finance
lower
Feb 4, 2026
Committee
To Finance
lower
Feb 4, 2026
Introduced
Introduced in House
lower
Feb 3, 2026
Upper · Passed
Passed Senate (Roll No. 38)
upper
Jan 29, 2026
Upper · Passed
Committee substitute reported
upper
Jan 22, 2026
Introduced
Introduced in Senate
upper
Jan 22, 2026
Committee
To Banking and Insurance
upper
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
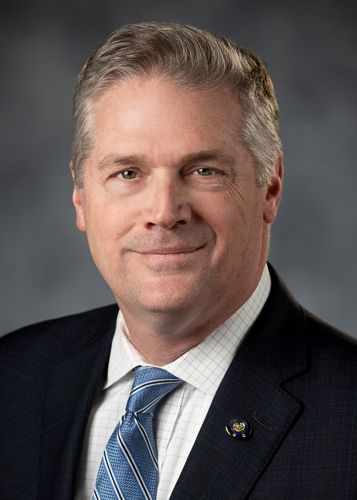
Mike Azinger
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about SB 573
Scope: WV
Hi! I can help you understand SB 573. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline