SB 85 Utah Senate · 2025 General Session

Income Tax Rate Amendments

SB 85 modifies Utah's individual income tax rate structure to automatically adjust based on actual state revenue performance. If actual state revenue exceeds the forecast for a given fiscal year (e.g., 2026-2035), the income tax rate decreases by half the difference between actual and forecast revenue - provided the reduction is at least 0.01%. The State Tax Commission must annually publish the updated rate for the following year. This directly affects Utah residents who pay individual income tax, while also changing the mineral production tax withholding rate to align with the new income tax rate. The bill contains no new spending and takes effect starting in 2026.
Bill status introduced 1 of 4 stages cleared
Introduction
Jan 2025
Committee Review
Floor Vote
Governor
Introduced Jan 21, 2025 Last action Mar 8, 2025
Maddy AI version diff · 1 comparison

What changed between versions

Introduced Substitute #1 · 5 edits
MODERATE
This bill modifies Utah's income tax rate structure to allow for automatic reductions when state revenue exceeds forecasts. It establishes a new formula where the tax rate can decrease by half the difference between actual and forecast revenue, with specific revenue targets set through 2035. The bill also updates the mineral production tax withholding rate from 5% to 4.55% and adjusts various tax credit calculations to align with the new rate. These changes aim to provide tax relief to Utah residents and businesses when the state collects more revenue than anticipated.
Scope change
The bill expands the income tax rate definition to include a dynamic calculation mechanism for years 2026-2035, replacing the fixed 4.55% rate with a formula-based approach that adjusts based on actual revenue performance.
REQUIREMENT

New Section 59-1-1801 and 59-1-1802 establish a consensus process where the Legislative Fiscal Analyst, State Tax Commission, and Governor's Office of Planning and Budget determine if actual revenue exceeds forecasts, triggering automatic tax rate reductions.

TIMELINE

Income tax rate definitions were updated to apply new calculation rules for taxable years beginning on or after January 1, 2026, with the rate potentially changing annually based on revenue performance.

FISCAL

Specific forecast revenue amounts were established for fiscal years 2026-2035, ranging from $13.2 billion to $20.5 billion, which serve as benchmarks for triggering tax rate reductions.

DEFINITION

The mineral production tax withholding rate was changed from 5% to 4.55% to align with the new income tax rate, affecting payments to mineral producers and their contractors.

TECHNICAL

Various tax credit calculations throughout the bill were updated to reference the new income tax rate percentage rather than the hardcoded 4.55% figure.

Floor votes

How they voted

No floor votes recorded yet.
Full legislative history

Actions timeline

Total actions
7
Key actions
0
Committee
0
Jan 21, 2025
Introduced
Senate/ 1st reading (Introduced)
upper
1 primary · 0 co-sponsors

Sponsors

Role
Legislator
Party
State
District
P
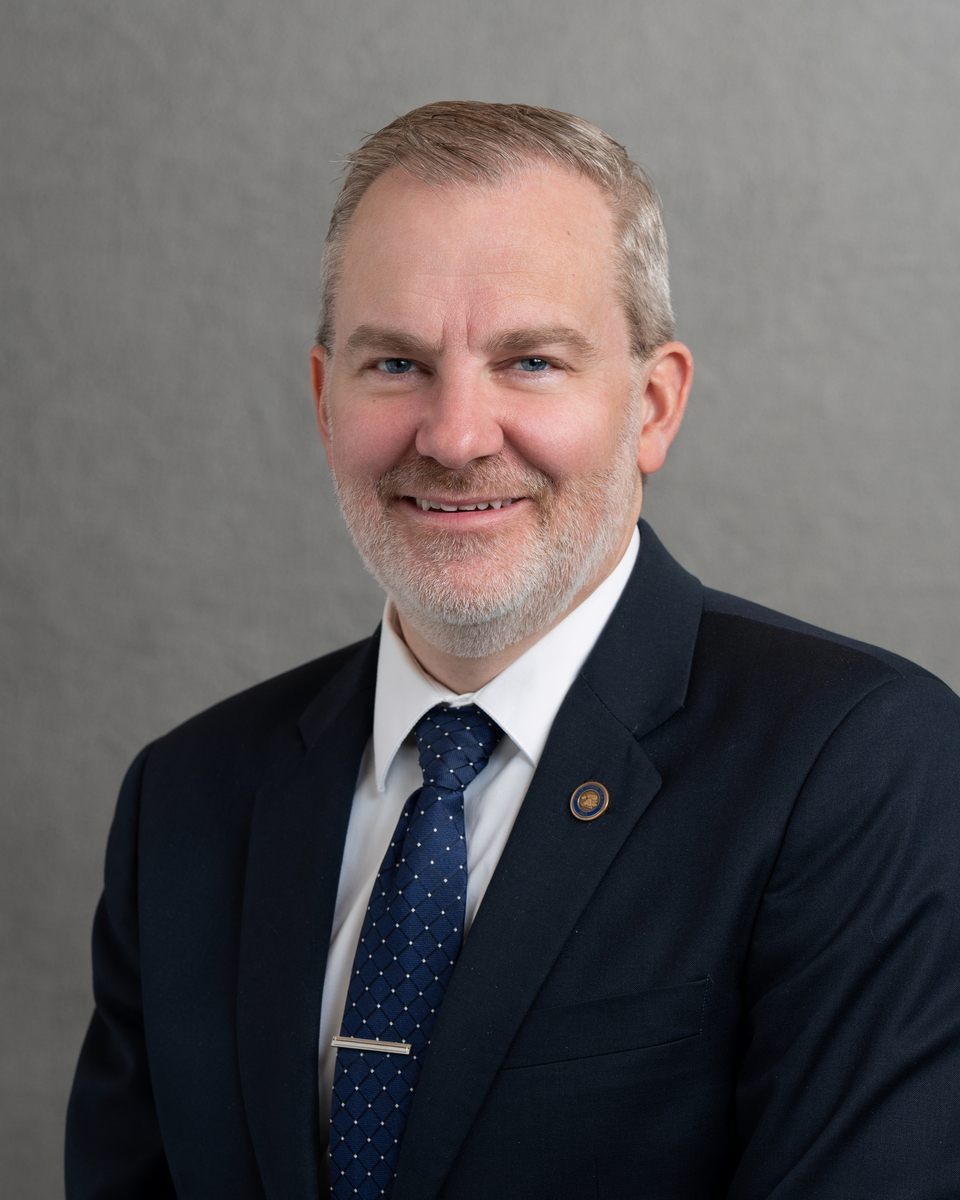
Photo of Lincoln Fillmore
Lincoln Fillmore
RRepublican
UT
17