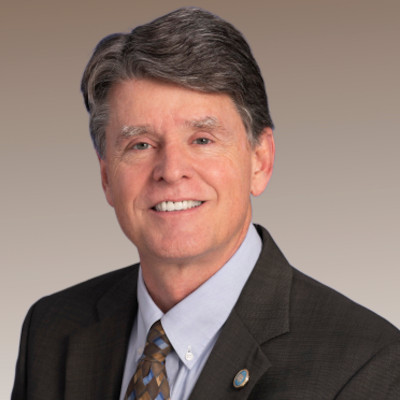
Photo of Tom Leatherwood
R Tennessee House · District 99 On the 2026 ballot

Rep. Tom Leatherwood

Compare
Total votes
19,921
all sessions
Attendance
96%
861 missed
Higher than 75% of chamber peers
With party
99%
of cast votes
Near the chamber average
Bipartisan score
0%
crosses aisle rarely
Near the chamber average
Sponsored
140
bills & resolutions
Near the chamber average
Committees
3
assignments
140 bills and resolutions

Sponsored bills

Total
140
Primary
140
Co-sponsor
0
This page
140
matching current filters
Primary HB 2634
In committee · Tennessee House · Lead sponsor
Millington - Subject to local approval, requires a candidate for the office of mayor to be a resident of the City of Millington for one year preceding the election rather than 60 days to qualify to run for such office. - Amends Chapter 238 of the Acts of 1903; as amended and rewritten.

Maddy summaryHB 2634 would change Millington's residency requirement for mayoral candidates, extending the needed time from 60 days to one full year before an election. This directly affects individuals seeking the mayoral office in Millington, requiring them to have lived in the city continuously for 12 months prior to running. The bill amends existing local law (Chapter 238 of the Acts of 1903) to update this qualification rule. It also requires approval by Millington's local legislative body with a two-thirds vote before taking effect.

In committee Jun 3, 2026 0 co-sponsors
Primary HB 1773
In committee · Tennessee House · Lead sponsor
Open Meetings - As enacted, authorizes emergency communications district boards of directors to participate in board meetings electronically under the open meetings law. - Amends TCA Title 7, Chapter 86, Part 3 and Title 8, Chapter 44, Part 1.

Maddy summaryHB 1773 allows emergency communications district boards of directors in Tennessee to participate in official meetings electronically under the state's open meetings law. This bill amends Tennessee Code Annotated Sections 8-44-108(a)(2) and references related provisions to explicitly include these boards within the definition of "governing body" for open meeting requirements. The change enables remote participation for board members during meetings while maintaining public access to proceedings. This is a procedural update to existing open meetings rules, not a new policy.

In committee May 27, 2026 0 co-sponsors
Primary HJR 1464
Signed into law · Tennessee House · Lead sponsor
Memorials, Sports - Kenneth Walker III, Super Bowl LX MVP -

Maddy summaryThis Tennessee House Joint Resolution honors Kenneth Walker III, a former Arlington High School graduate and Seattle Seahawks running back, for being named the Most Valuable Player of Super Bowl LX. The bill formally recognizes his achievements during the 2025 season, including his performance in the championship game where he led his team to victory. It does not create any new laws or policies but serves as a ceremonial tribute to celebrate his athletic success and personal milestones.

Signed into law May 1, 2026 0 co-sponsors
Primary HB 1777
In committee · Tennessee House · Lead sponsor
Business Organizations - As introduced, requires the comptroller of the treasury to submit a report, on or before December 31, 2026, to the governor, the speaker of the senate, the speaker of the house of representatives, the chair of the state and local government committee of the senate, and the chair of the committee of the house of representatives having jurisdiction over housing containing a summary of certain de-identified information related to real estate investment trusts' purchases and sales of single-family homes in this state in 2025. - Amends TCA Title 4; Title 5; Title 6; Title 7; Title 13; Title 47; Title 48; Title 61; Title 66 and Title 67.

Maddy summaryHB 1777 requires Tennessee's comptroller of the treasury to compile and report de-identified data about real estate investment trusts (REITs) that purchased 10+ single-family homes in the state during 2025. The report, due by December 31, 2026, must include the number of homes bought (with appraised values), homes acquired via foreclosure, homes sold that year, and homes used as rentals. This data will be submitted to the governor, legislative leaders, and committee chairs overseeing housing. The bill directly affects REITs meeting the 2025 purchase threshold, focusing on transparency around their single-family home market activity.

In committee Apr 14, 2026 0 co-sponsors
Primary HB 2266
In committee · Tennessee House · Lead sponsor
Criminal Offenses - As introduced, increases the penalty for vehicular homicide from a Class C felony to a Class B felony if the offense occurred as the proximate result of the driver's extreme and excessive rate of speed; defines "extreme and excessive rate of speed" as traveling at more than 20 miles per hour over the posted speed limit. - Amends TCA Title 39 and Title 55.

Maddy summaryHB 2266 amends Tennessee law to increase the penalty for vehicular homicide from a Class C felony to a Class B felony when the death results from a driver traveling more than 20 miles per hour over the posted speed limit. The bill directly affects drivers whose extreme speeding (defined as exceeding the speed limit by 20+ mph) causes a fatal crash. It creates a specific speed threshold ("extreme and excessive rate of speed") and upgrades the felony classification for such cases. This change applies to prosecutions under Tennessee Code Annotated Sections 39-13-213(a)(5) and (b)(4), effective July 1, 2026.

In committee Mar 25, 2026 0 co-sponsors
Primary HB 1779
In committee · Tennessee House · Lead sponsor
Taxes, Real Property - As introduced, requires a written notice of the intended seizure of personal property given by the county trustee, deputy trustee, or delinquent tax attorney that is mailed to the taxpayer's last known address be provided by certified, registered, or first class mail. - Amends TCA Title 67, Chapter 5.

Maddy summaryHB 1779 requires that notices of intended seizure of personal property to collect delinquent real property taxes must be sent to a taxpayer's last known address via certified, registered, or first-class mail. This directly affects Tennessee property owners with unpaid real property taxes, ensuring they receive verifiable notice before personal property (such as vehicles or belongings) can be seized. The key provision amends Tennessee law to specify these mailing methods, replacing vague requirements with clear delivery standards. The bill does not change tax rates, seizure eligibility, or the underlying tax process - only the method of delivering critical notice to taxpayers.

In committee Mar 18, 2026 0 co-sponsors
Primary HB 2265
In committee · Tennessee House · Lead sponsor
Taxes, Real Property - As introduced, urges the comptroller of the treasury to study the feasibility and potential impacts of establishing the value of all residential property as the most recent price paid for the property in lieu of assessors of property appraising the value through the use of assessment manuals; requires a report, if the study is conducted, to be submitted to the finance, ways and means committee of the senate and the committee of the house of representatives having jurisdiction over finance matters. - Amends TCA Title 67, Chapter 5.

Maddy summaryHB 2265 urges Tennessee's comptroller of the treasury to study replacing current property assessment methods with using the most recent sale price for all residential properties. If the study occurs, the comptroller must report findings and recommendations to the Senate Finance Committee and the House Finance Committee. The bill does not change tax rates or assessments but requests a feasibility review of this valuation approach, which would directly affect residential property owners. This is a procedural study request, not a tax law change, and remains pending in committee.

In committee Feb 5, 2026 0 co-sponsors
Primary HB 1776
Introduced · Tennessee House · Lead sponsor
Education, Dept. of - As introduced, changes, beginning in 2027, the deadline for the department to submit its annual report on the school safety alert grant pilot fund from February 1 to January 15. - Amends TCA Title 49.

Maddy summaryHB 1776 changes the deadline for the Tennessee Department of Education to submit its annual report on the school safety alert grant pilot fund, moving it from February 1 to January 15 each year, effective beginning with reports due in 2027. This procedural adjustment affects the department’s reporting schedule without altering the content or requirements of the report. The bill amends Tennessee Code Annotated, Title 49, Section 49-1-225(f), to implement this timing change. It does not impact the grant program’s funding, eligibility, or other operational details.

Introduced Jan 22, 2026 0 co-sponsors
Primary HB 1781
Introduced · Tennessee House · Lead sponsor
Adoption - As introduced, changes from 100 years to 90 years the amount of time that must elapse from the date the adoption was finalized before confidential adoption records become public records open to inspection. - Amends TCA Title 18; Title 36, Chapter 1; Title 37; Title 49, Chapter 4, Part 9; Title 49, Chapter 5, Part 7 and Section 49-6-1304.

Maddy summaryHB 1781 shortens Tennessee's adoption record confidentiality period from 100 years to 90 years after an adoption is finalized. This change allows adoptees and birth family members to access sealed adoption records 10 years earlier than under current law. The bill amends multiple sections of Tennessee Code (including Titles 18, 36, 37, and 49) to update the waiting period for making these records public. It directly affects individuals seeking their adoption history and the state's process for handling record requests.

Introduced Jan 22, 2026 0 co-sponsors
Primary HB 1778
In committee · Tennessee House · Lead sponsor
Taxes, Sales - As introduced, urges the department of revenue to study the amount of revenue derived during the previous five fiscal years from the sales tax imposed on retail sales of non-prepared food, and from the general sales tax imposed on retail sales of prepared food; requires a report be submitted to the chairs of the finance, ways and means committees and the office of legislative budget analysis. - Amends TCA Title 67, Chapter 6.

Maddy summaryHB 1778 requires Tennessee's Department of Revenue to study sales tax revenue from two food categories over the previous five fiscal years: non-prepared food (like fresh produce) and prepared food. The department must report its findings, including revenue amounts and recommendations, to legislative committees by December 31, 2026. This bill does not change tax rates or create new taxes - it only requests a factual analysis of existing revenue. The study aims to inform future policy decisions but does not enact any immediate policy changes.

In committee Jan 22, 2026 0 co-sponsors
Showing 1 to 10 of 140 bills
1 2 3 14 Next