

An Act amending the act of March 4, 1971 (P.L.6, No.2), known as the Tax Reform Code of 1971, in inheritance tax, further providing for transfers not subject to tax.
HB 256 exempts transfers of funds from qualified tuition programs (like 529 college savings plans) from Pennsylvania's inheritance tax when moved to the designated beneficiary or their parent/guardian if the beneficiary is under 18. It uses federal definitions from the Internal Revenue Code (Section 529) to define "qualified tuition program" and "designated beneficiary." The change applies to estates of people who died after November 6, 2023. This policy directly affects families using these education savings programs by removing an inheritance tax burden on transferred funds.
Bill status
in committee
1 of 4 stages cleared
Introduction
Jan 2025
Committee Review
Floor Vote
Governor
Introduced Jan 22, 2025
Last action Jan 22, 2025
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
1
Key actions
0
Committee
1
Jan 22, 2025
Committee
Referred to Finance
lower
1 primary · 11 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
Stephenie Scialabba
RRepublican
Co
Brad Roae
RRepublican
Co
David Rowe
RRepublican
Co
Jill Cooper
RRepublican
Co
Joe Hamm
RRepublican
Co
Keith Greiner
RRepublican
Co
Kristin Marcell
RRepublican
Co
Mark Gillen
RRepublican
Co
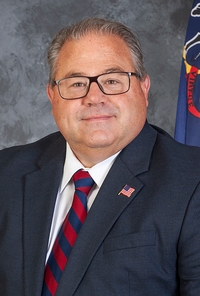
Mike Armanini
RRepublican
Co
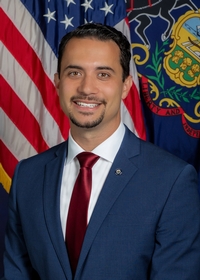
Robert Leadbeter
RRepublican
Co
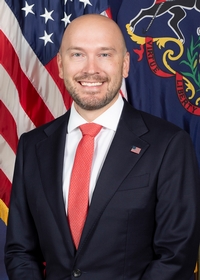
Roman Kozak
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 256
Scope: PA
Hi! I can help you understand HB 256. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline