

An Act amending the act of March 4, 1971 (P.L.6, No.2), known as the Tax Reform Code of 1971, in historic preservation incentive tax credit, further providing for tax credit certificates.
HB 1572 modifies Pennsylvania's historic preservation tax credit program by setting new annual spending limits and allocation rules. It caps total annual tax credits at $20 million (excluding unused prior-year credits), limits credits to $1.5 million per project owner annually (up from $500,000), and requires equitable regional distribution of credits - reallocating unclaimed funds to other regions. The bill directly affects historic preservation project owners seeking tax credits for rehabilitation work. These changes apply to fiscal years starting July 1, 2025, and aim to manage program funding more systematically.
Bill status
passed
3 of 5 stages cleared
Introduction
Jun 2025
Committee Review
Jul 2025
House Passage
Jun 2025
Senate Passage
Governor
Introduced Jun 10, 2025
Last action Jul 8, 2025
Floor votes · House Jun 30, 2025
How they voted
141–62
Passed
Total votes 203
Jun 30, 2025
D
Democratic102
100% Yea
R
Republican101
61% Nay
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
10
Key actions
4
Committee
7
Jul 8, 2025
Committee
Referred to Finance
upper
Jun 30, 2025
Lower · Passed
Third consideration and final passage
lower
Jun 30, 2025
Lower · Passed
Re-reported as committed
lower
Jun 26, 2025
Committee
Re-committed to Appropriations
lower
Jun 25, 2025
Lower · Passed
Re-reported as committed
lower
Jun 17, 2025
Committee
Re-committed to Rules
lower
Jun 17, 2025
Lower · Passed
Reported as committed
lower
Jun 10, 2025
Committee
Referred to Finance
lower
1 primary · 21 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
Dan Goughnour
DDemocratic
Co
Ben Sanchez
DDemocratic
Co
Bob Freeman
DDemocratic
Co
Brian Munroe
DDemocratic
Co
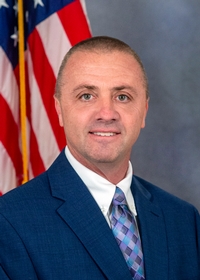
Dan Deasy
DDemocratic
Co
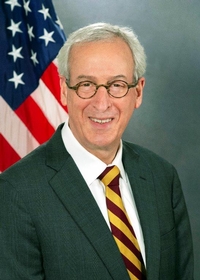
Dan Frankel
DDemocratic
Co
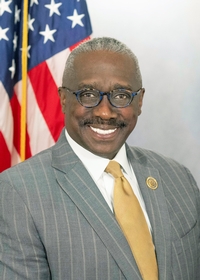
Dan Williams
DDemocratic
Co
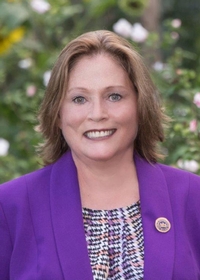
Jeanne McNeill
DDemocratic
Co
Jim Prokopiak
DDemocratic
Co
Joe Ciresi
DDemocratic
Co
Joe Webster
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 1572
Scope: PA
Hi! I can help you understand HB 1572. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline