

Income tax; requiring reduction of rate upon certification of excess collections. Effective date.
SB 1856 requires Oklahoma to automatically reduce the top individual income tax rate if state tax collections exceed the previous year's total by a specified threshold. It directly affects all Oklahoma residents and nonresidents who pay state income tax, as it triggers rate reductions based on certified excess collections. The bill amends tax code provisions to establish clear calculation methods for determining when and by how much the top marginal tax rate must decrease. This creates a concrete, automatic policy change tied to actual tax revenue performance, rather than legislative action.
Bill status
in committee
1 of 4 stages cleared
Introduction
Feb 2026
Committee Review
Floor Vote
Governor
Introduced Feb 2, 2026
Last action Feb 3, 2026
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
3
Key actions
0
Committee
0
Feb 2, 2026
Introduced
First Reading
upper
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
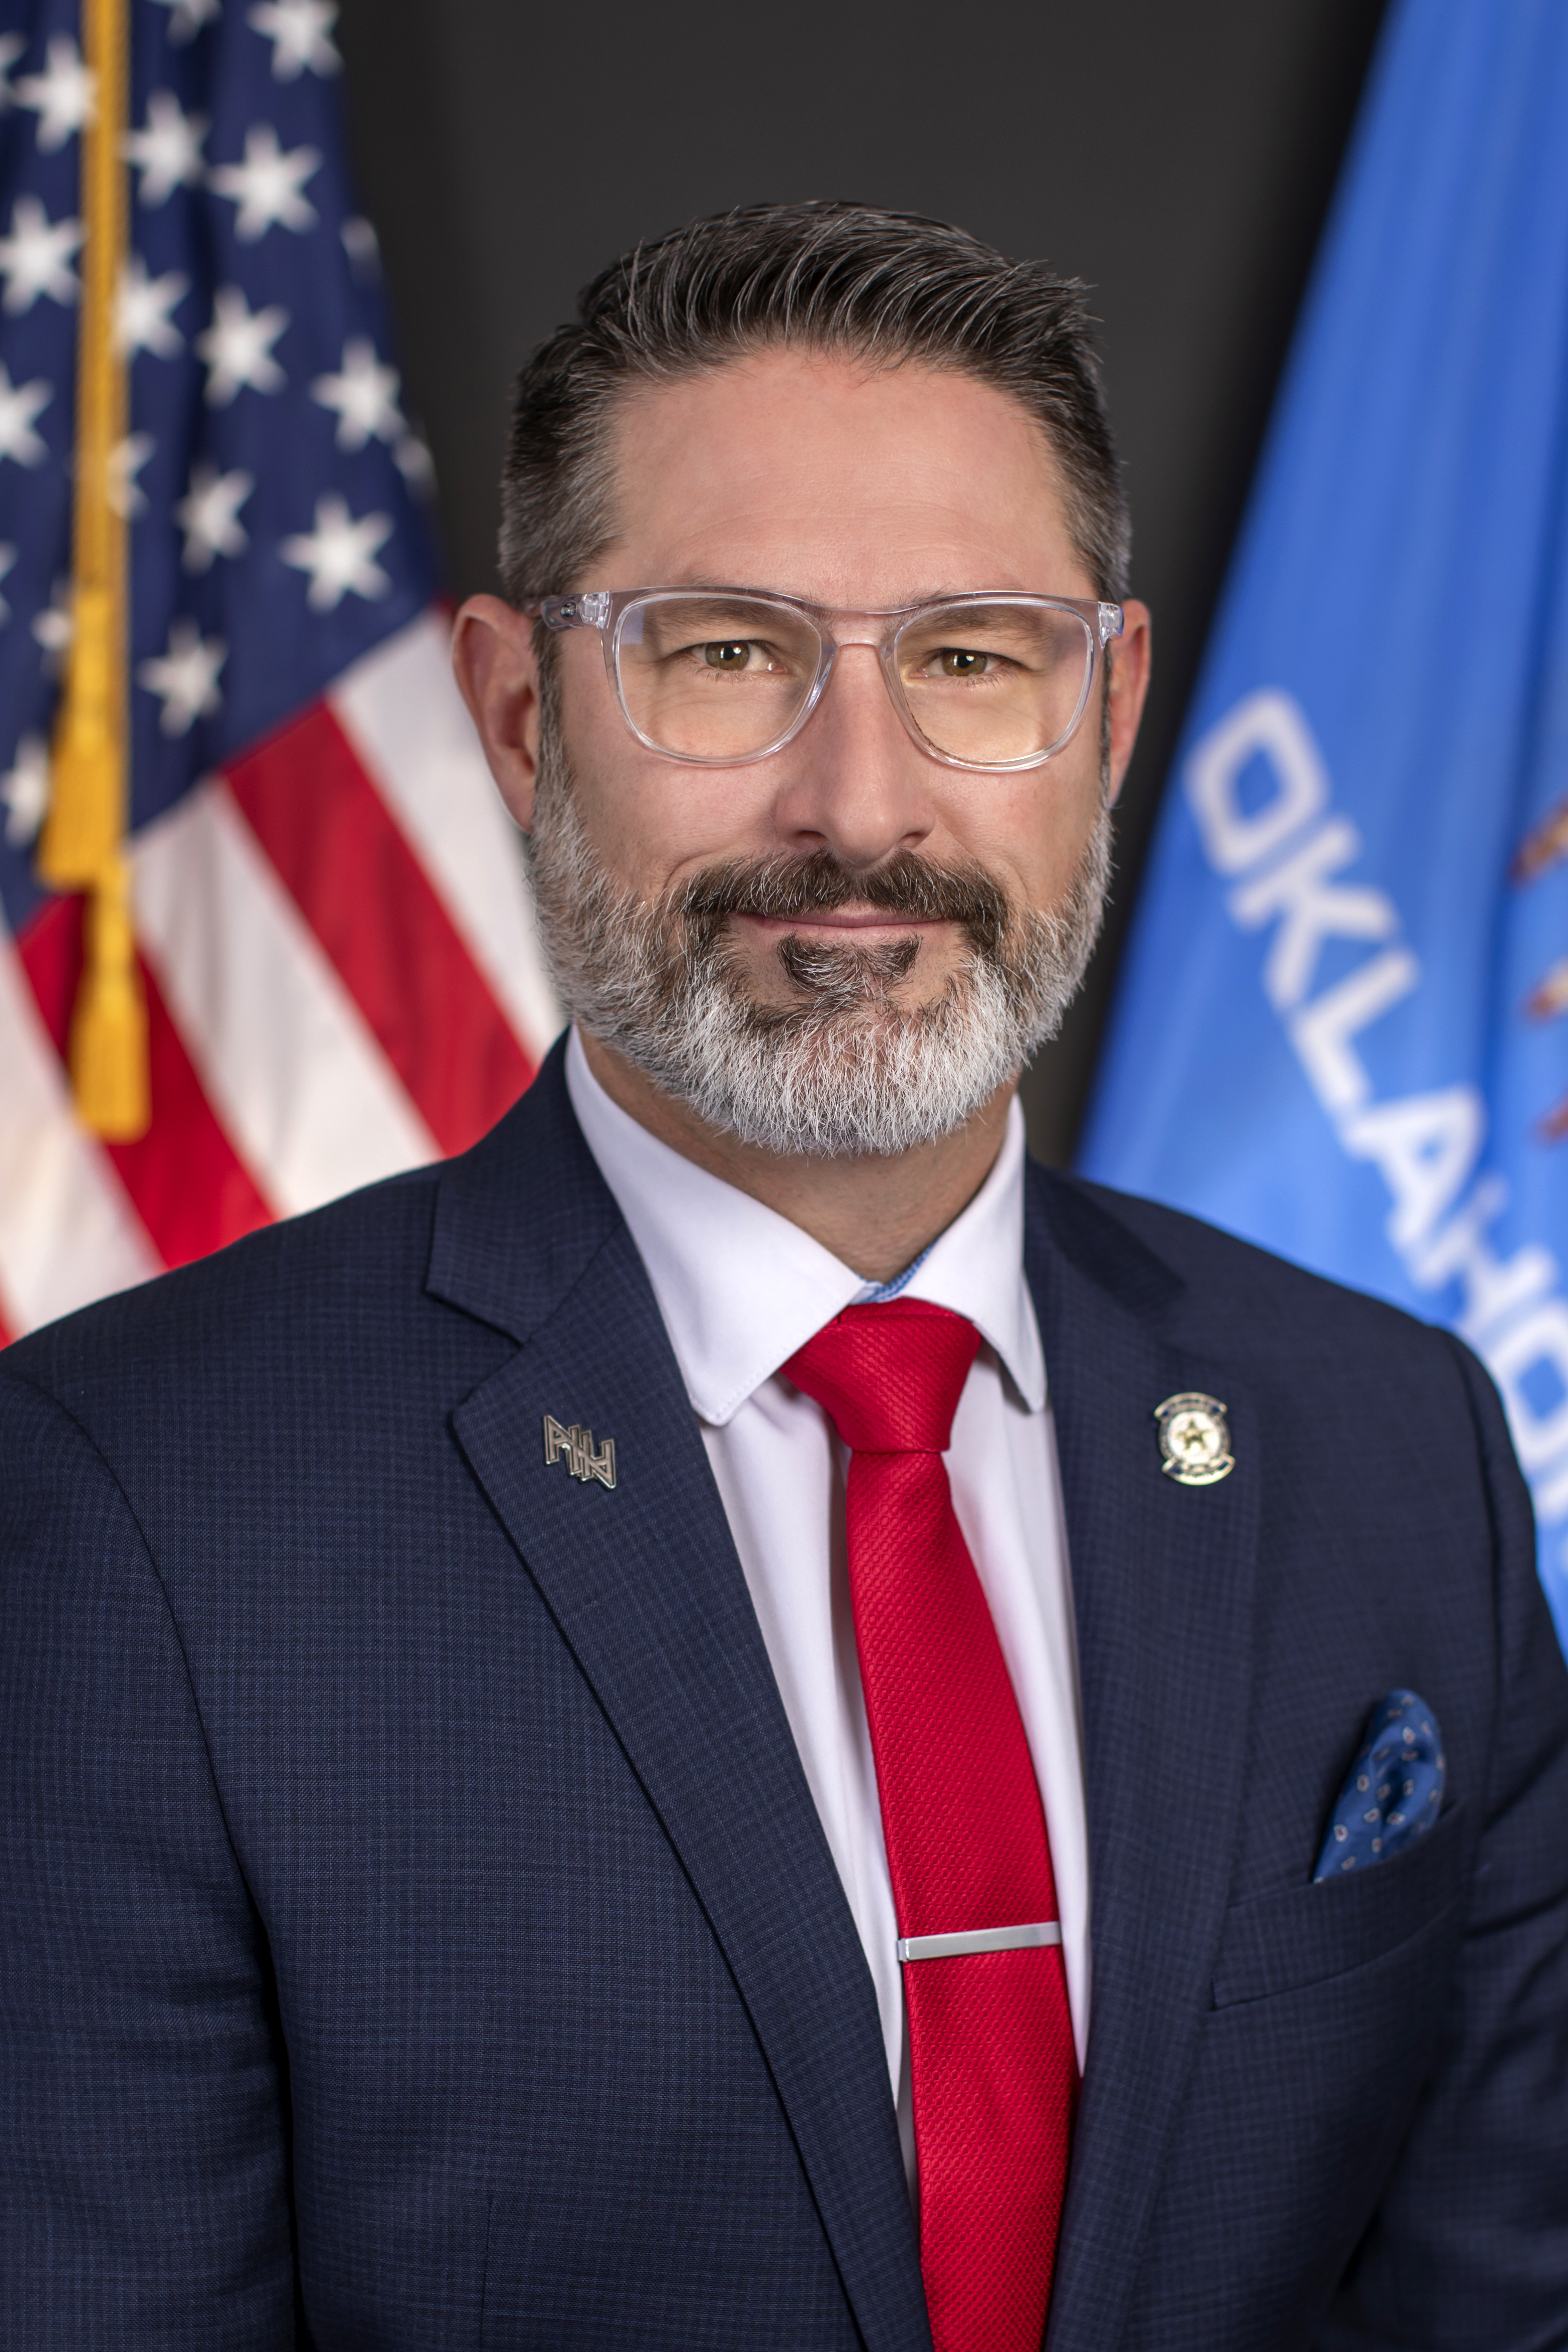
Dusty Deevers
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about SB 1856
Scope: OK
Hi! I can help you understand SB 1856. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline