

Taxes; gross production tax; requiring certain completion methods for specific exemptions; effective date.
HB 3986 modernizes Oklahoma's gross production tax for oil, gas, and mineral production. It sets a 7% tax rate on most oil and gas production (increasing from previous rates), with a temporary 5% rate for wells spudded before the law's effective date for 36 months. The bill creates tax exemptions for 5 years for secondary/tertiary recovery projects (approved after July 2022) and offers a 50% tax reduction for 36 months on production from orphaned wells (requiring a $25,000 bond per well). Producers of oil/gas using recycled water for well completion also get a 24-month exemption proportional to recycled water use. Refunds for exempt production are capped annually at $15 million for recovery projects and $10 million for recycled water projects.
Bill status
signed
all 5 stages cleared
Introduction
Feb 2026
Committee Review
May 2026
House Passage
Mar 2026
Senate Passage
May 2026
Signed into Law
May 2026
Introduced Feb 2, 2026
Signed May 12, 2026
Maddy AI version diff · 6 comparisons
What changed between versions
Floor (House)
→
Floor (Senate)
·
3 edits
MINOR
The bill was converted from a House version to a Senate version, updating the header, authorship, and page numbering. The substantive tax rates and exemption criteria for oil and gas production remain consistent with the House version, though the Senate version includes specific formatting markers indicating committee amendments.
Scope change
The bill's scope and applicability remain unchanged; it continues to govern gross production taxes on oil and gas in Oklahoma.
TECHNICAL
The document header was changed from 'HOUSE OF REPRESENTATIVES' to 'SENATE FLOOR VERSION', and the authorship line was updated to include 'Thompson of the Senate'.
Page footers were updated to reflect 'SENATE FLOOR VERSION' instead of 'HOUSE FLOOR VERSION'.
The text of the tax provisions was restructured with different numbering (e.g., paragraphs 1, 2, 3) and bold formatting was added to denote committee amendments, but the underlying tax rates and rules appear identical to the House version.
Floor votes · Senate May 5, 2026 · House Mar 24, 2026
How they voted
42–5
Passed · 3 other
Total votes 50
May 5, 2026
D
Democratic9
55% Nay
R
Republican41
97% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
25
Key actions
8
Committee
7
May 12, 2026
Signed into law
Approved by Governor 05/12/2026
lower
May 5, 2026
Committee
Referred for enrollment
lower
May 5, 2026
Upper · Passed
Engrossed measure signed, returned to House
upper
May 5, 2026
Upper · Passed
Measure passed: Ayes: 40 Nays: 5
upper
Apr 13, 2026
Upper · Passed
Reported Do Pass Revenue and Taxation committee; CR filed
upper
Apr 9, 2026
Committee
Referred to Revenue and Taxation
upper
Apr 9, 2026
Upper · Passed
Reported Do Pass Energy committee; CR filed
upper
Mar 25, 2026
Introduced
First Reading
upper
Mar 25, 2026
Lower · Passed
Engrossed, signed, to Senate
lower
Mar 24, 2026
Committee
Referred for engrossment
lower
Mar 24, 2026
Lower · Passed
Third Reading, Measure passed: Ayes: 81 Nays: 11
lower
Feb 25, 2026
Lower · Passed
CR; Do Pass, amended by committee substitute Appropriations and Budget Committee
lower
Feb 18, 2026
Committee
Referred to Appropriations and Budget
lower
Feb 2, 2026
Introduced
First Reading
lower
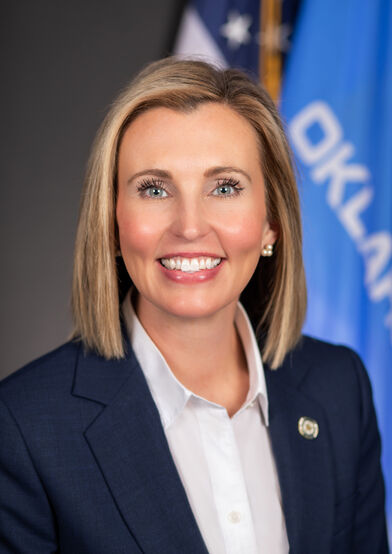
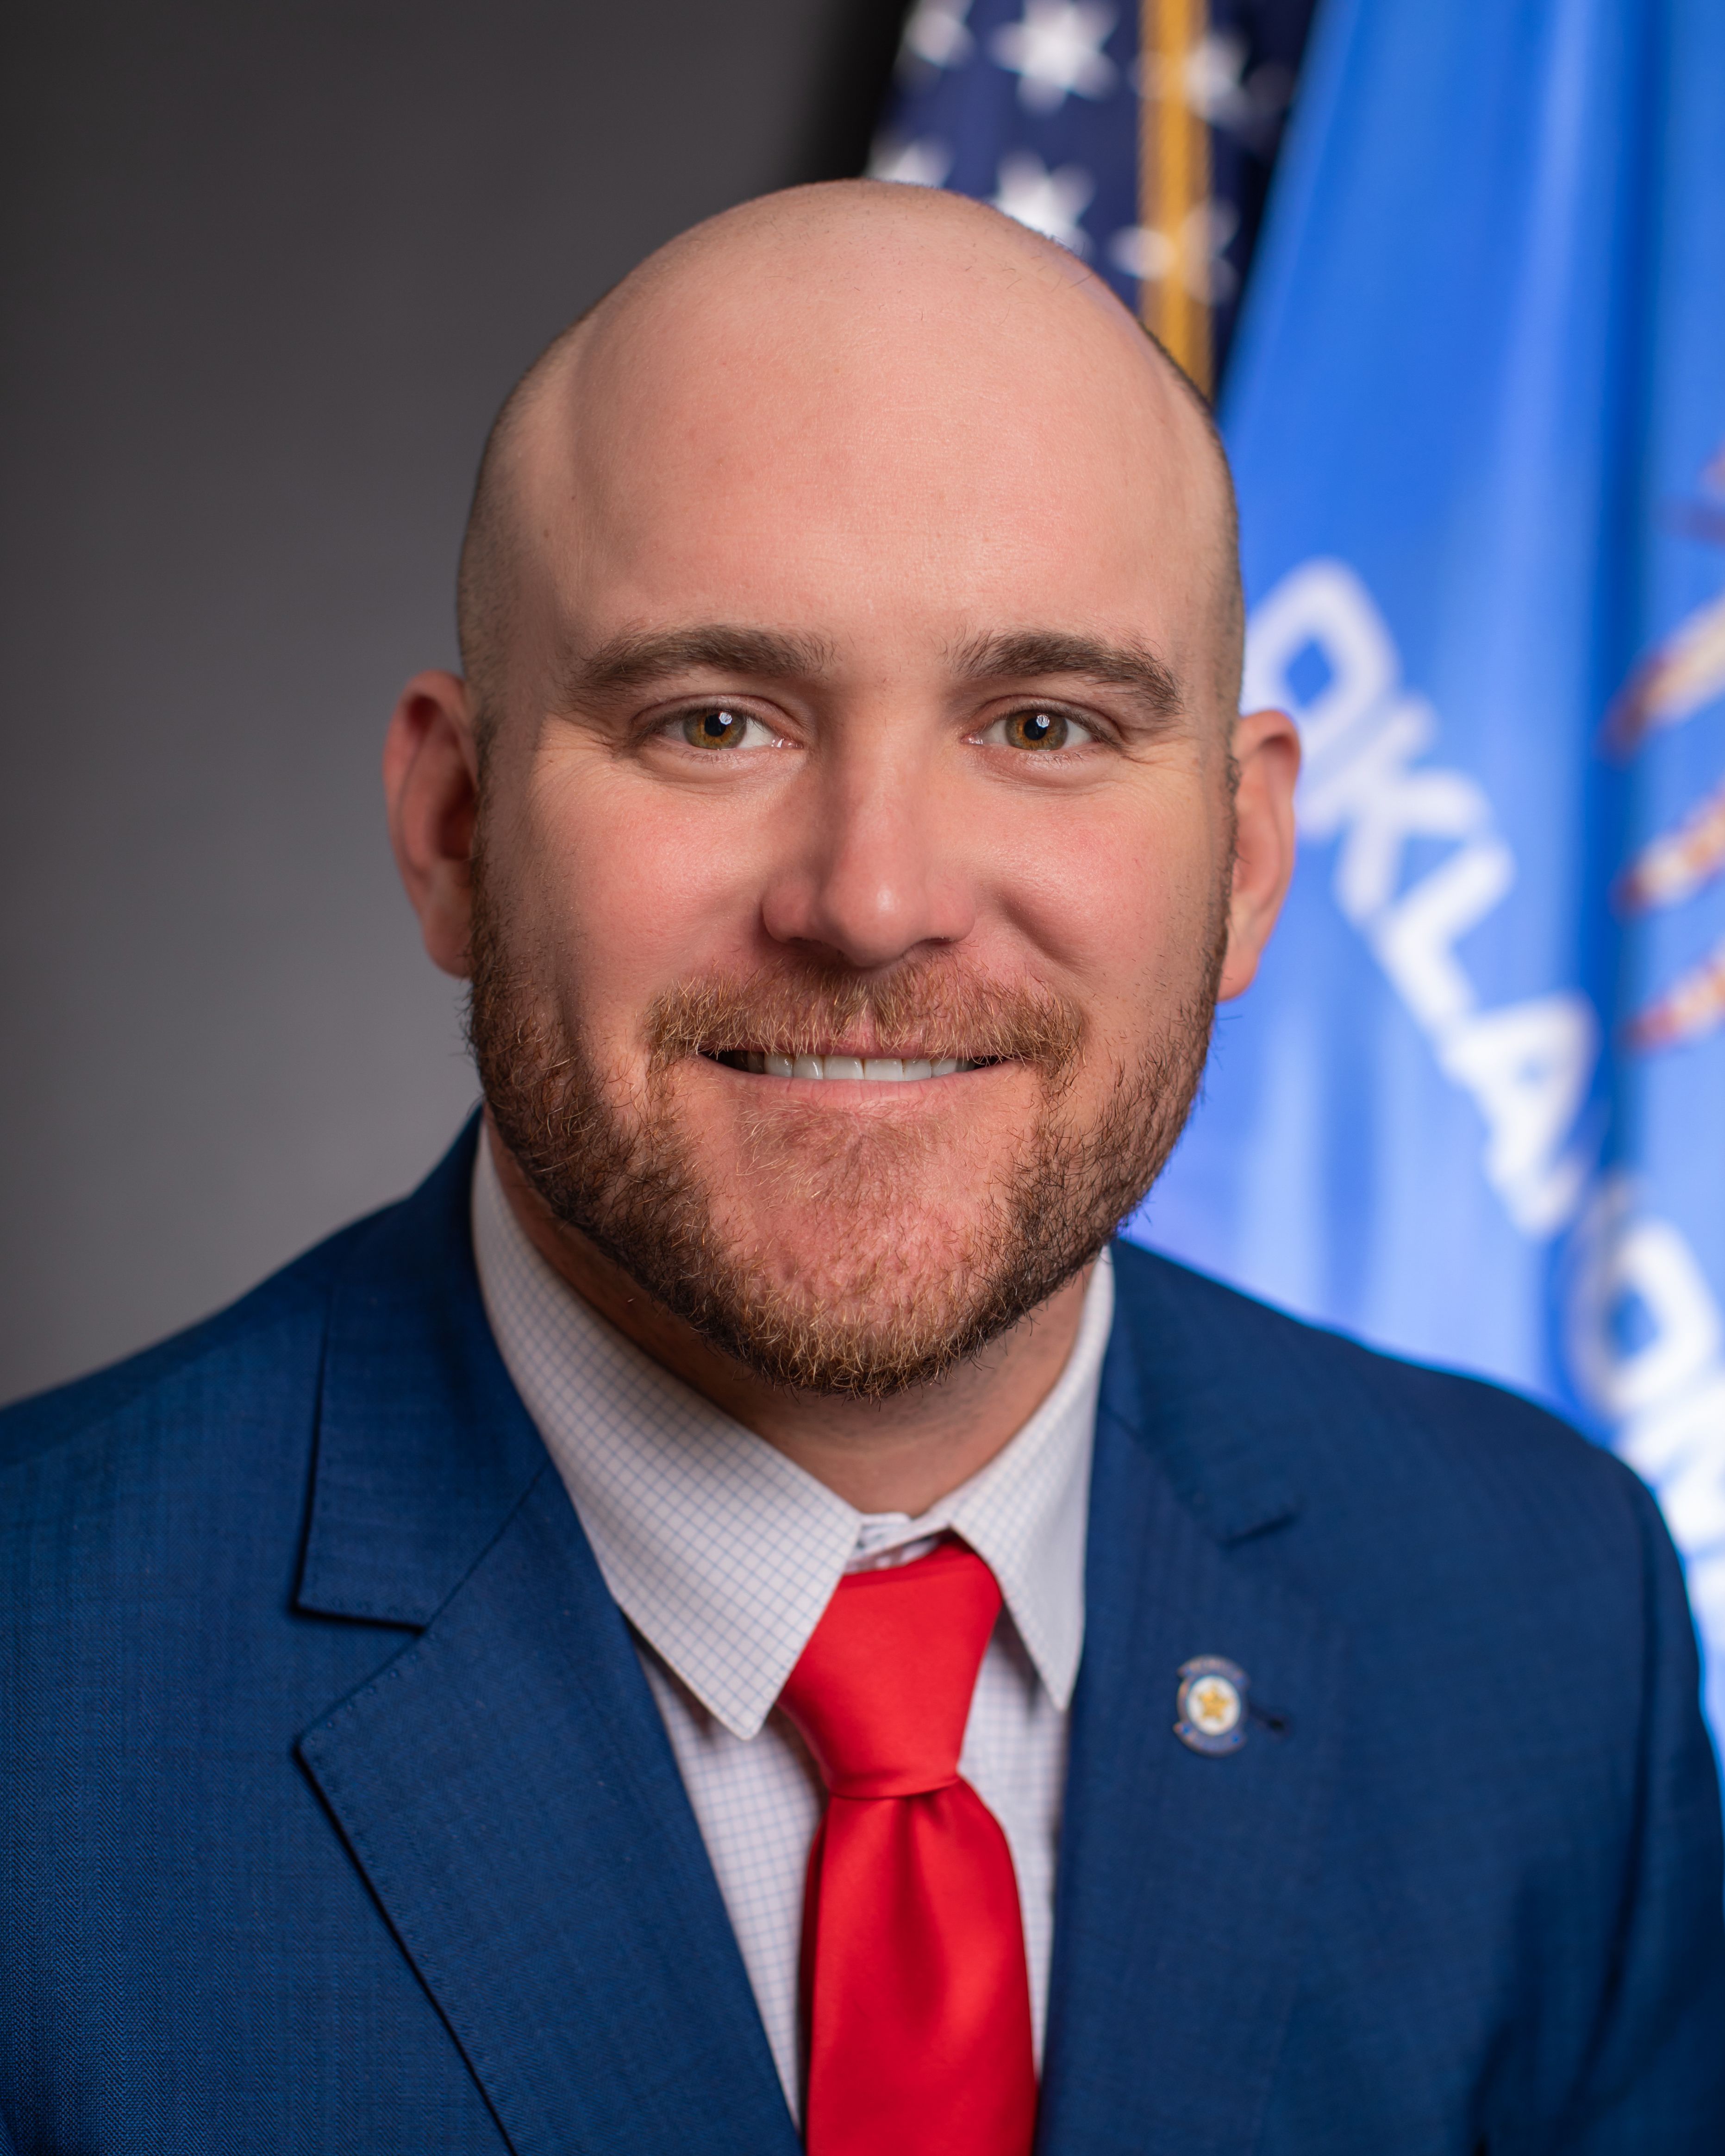
2 primary · 0 co-sponsors
Sponsors
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 3986
Scope: OK
Hi! I can help you understand HB 3986. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline