

Revenue and taxation; Oklahoma taxable income and adjusted gross income; exemption; retirement income; effective date.
HB 2190 amends Oklahoma's tax code to adjust how the state calculates taxable income for individuals and corporations, directly affecting taxpayers who file state returns. It modifies rules for deducting federal net operating losses, adjusts income allocation methods for property and business activities (like rental income or partnership sales), and clarifies how retirement income is treated. Key provisions include specifying how losses from out-of-state sources are handled and changing how income from property sales is allocated based on location. The bill does not change tax rates but refines the calculation process for determining Oklahoma taxable income. It is currently in committee review (referred to Appropriations and Budget Subcommittee) and has not yet been enacted.
Bill status
in committee
1 of 4 stages cleared
Introduction
Feb 2025
Committee Review
Floor Vote
Governor
Introduced Feb 3, 2025
Last action Feb 4, 2025
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
4
Key actions
0
Committee
1
Feb 4, 2025
Committee
Referred to Appropriations and Budget Finance Subcommittee
lower
Feb 3, 2025
Introduced
First Reading
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
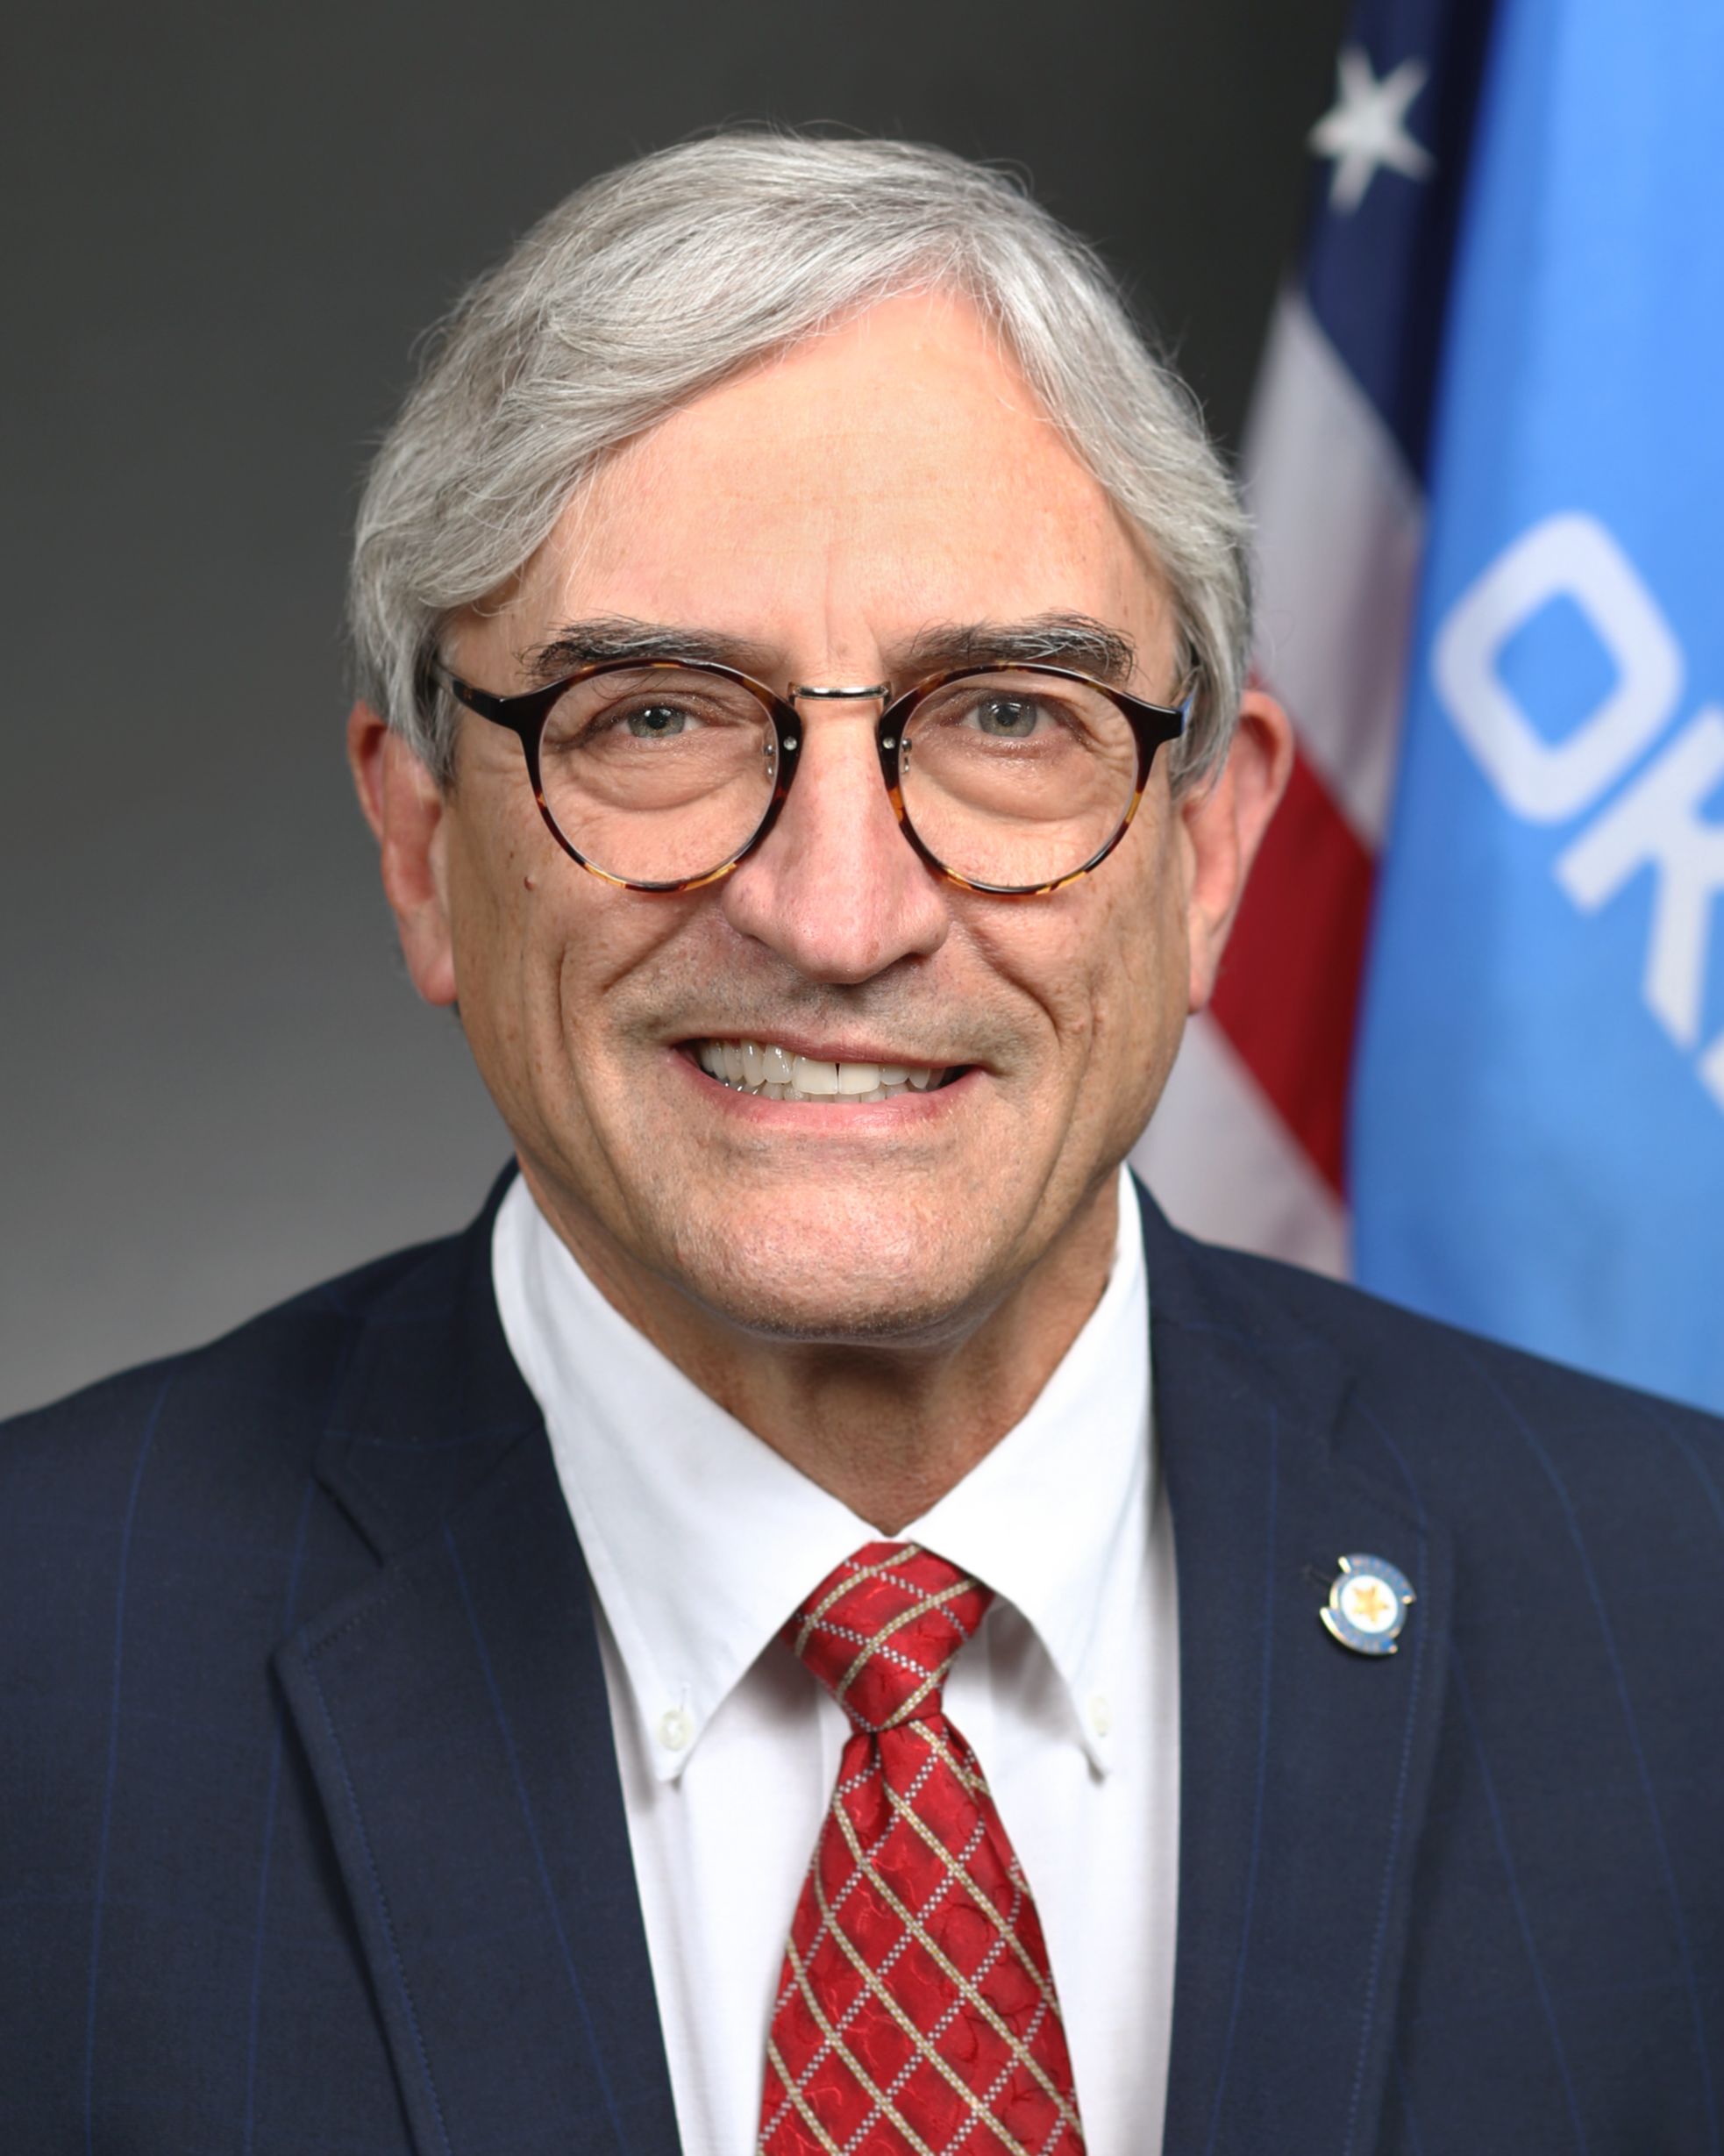
Max Wolfley
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 2190
Scope: OK
Hi! I can help you understand HB 2190. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline