

Revenue and taxation; income tax; adjustments; retirement benefits; effective date.
HB 1391 amends Oklahoma's income tax code to adjust how taxable income is calculated for individuals and corporations. It specifically revises rules for federal net operating loss deductions (including carryback periods and allocation methods) and clarifies how income from property (real or intangible) and business activities should be allocated to Oklahoma for tax purposes. The bill directly affects businesses and taxpayers who claim federal deductions or operate across state lines, requiring them to adjust their Oklahoma tax calculations based on Oklahoma-specific rules. Key changes include aligning Oklahoma's loss carryback rules with federal timelines for certain tax years and defining how income from property or sales is allocated to Oklahoma. This is a technical adjustment to Oklahoma's tax code, not a new tax or benefit.
Bill status
in committee
1 of 4 stages cleared
Introduction
Feb 2025
Committee Review
Floor Vote
Governor
Introduced Feb 3, 2025
Last action Feb 4, 2025
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
4
Key actions
0
Committee
1
Feb 4, 2025
Committee
Referred to Appropriations and Budget Finance Subcommittee
lower
Feb 3, 2025
Introduced
First Reading
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
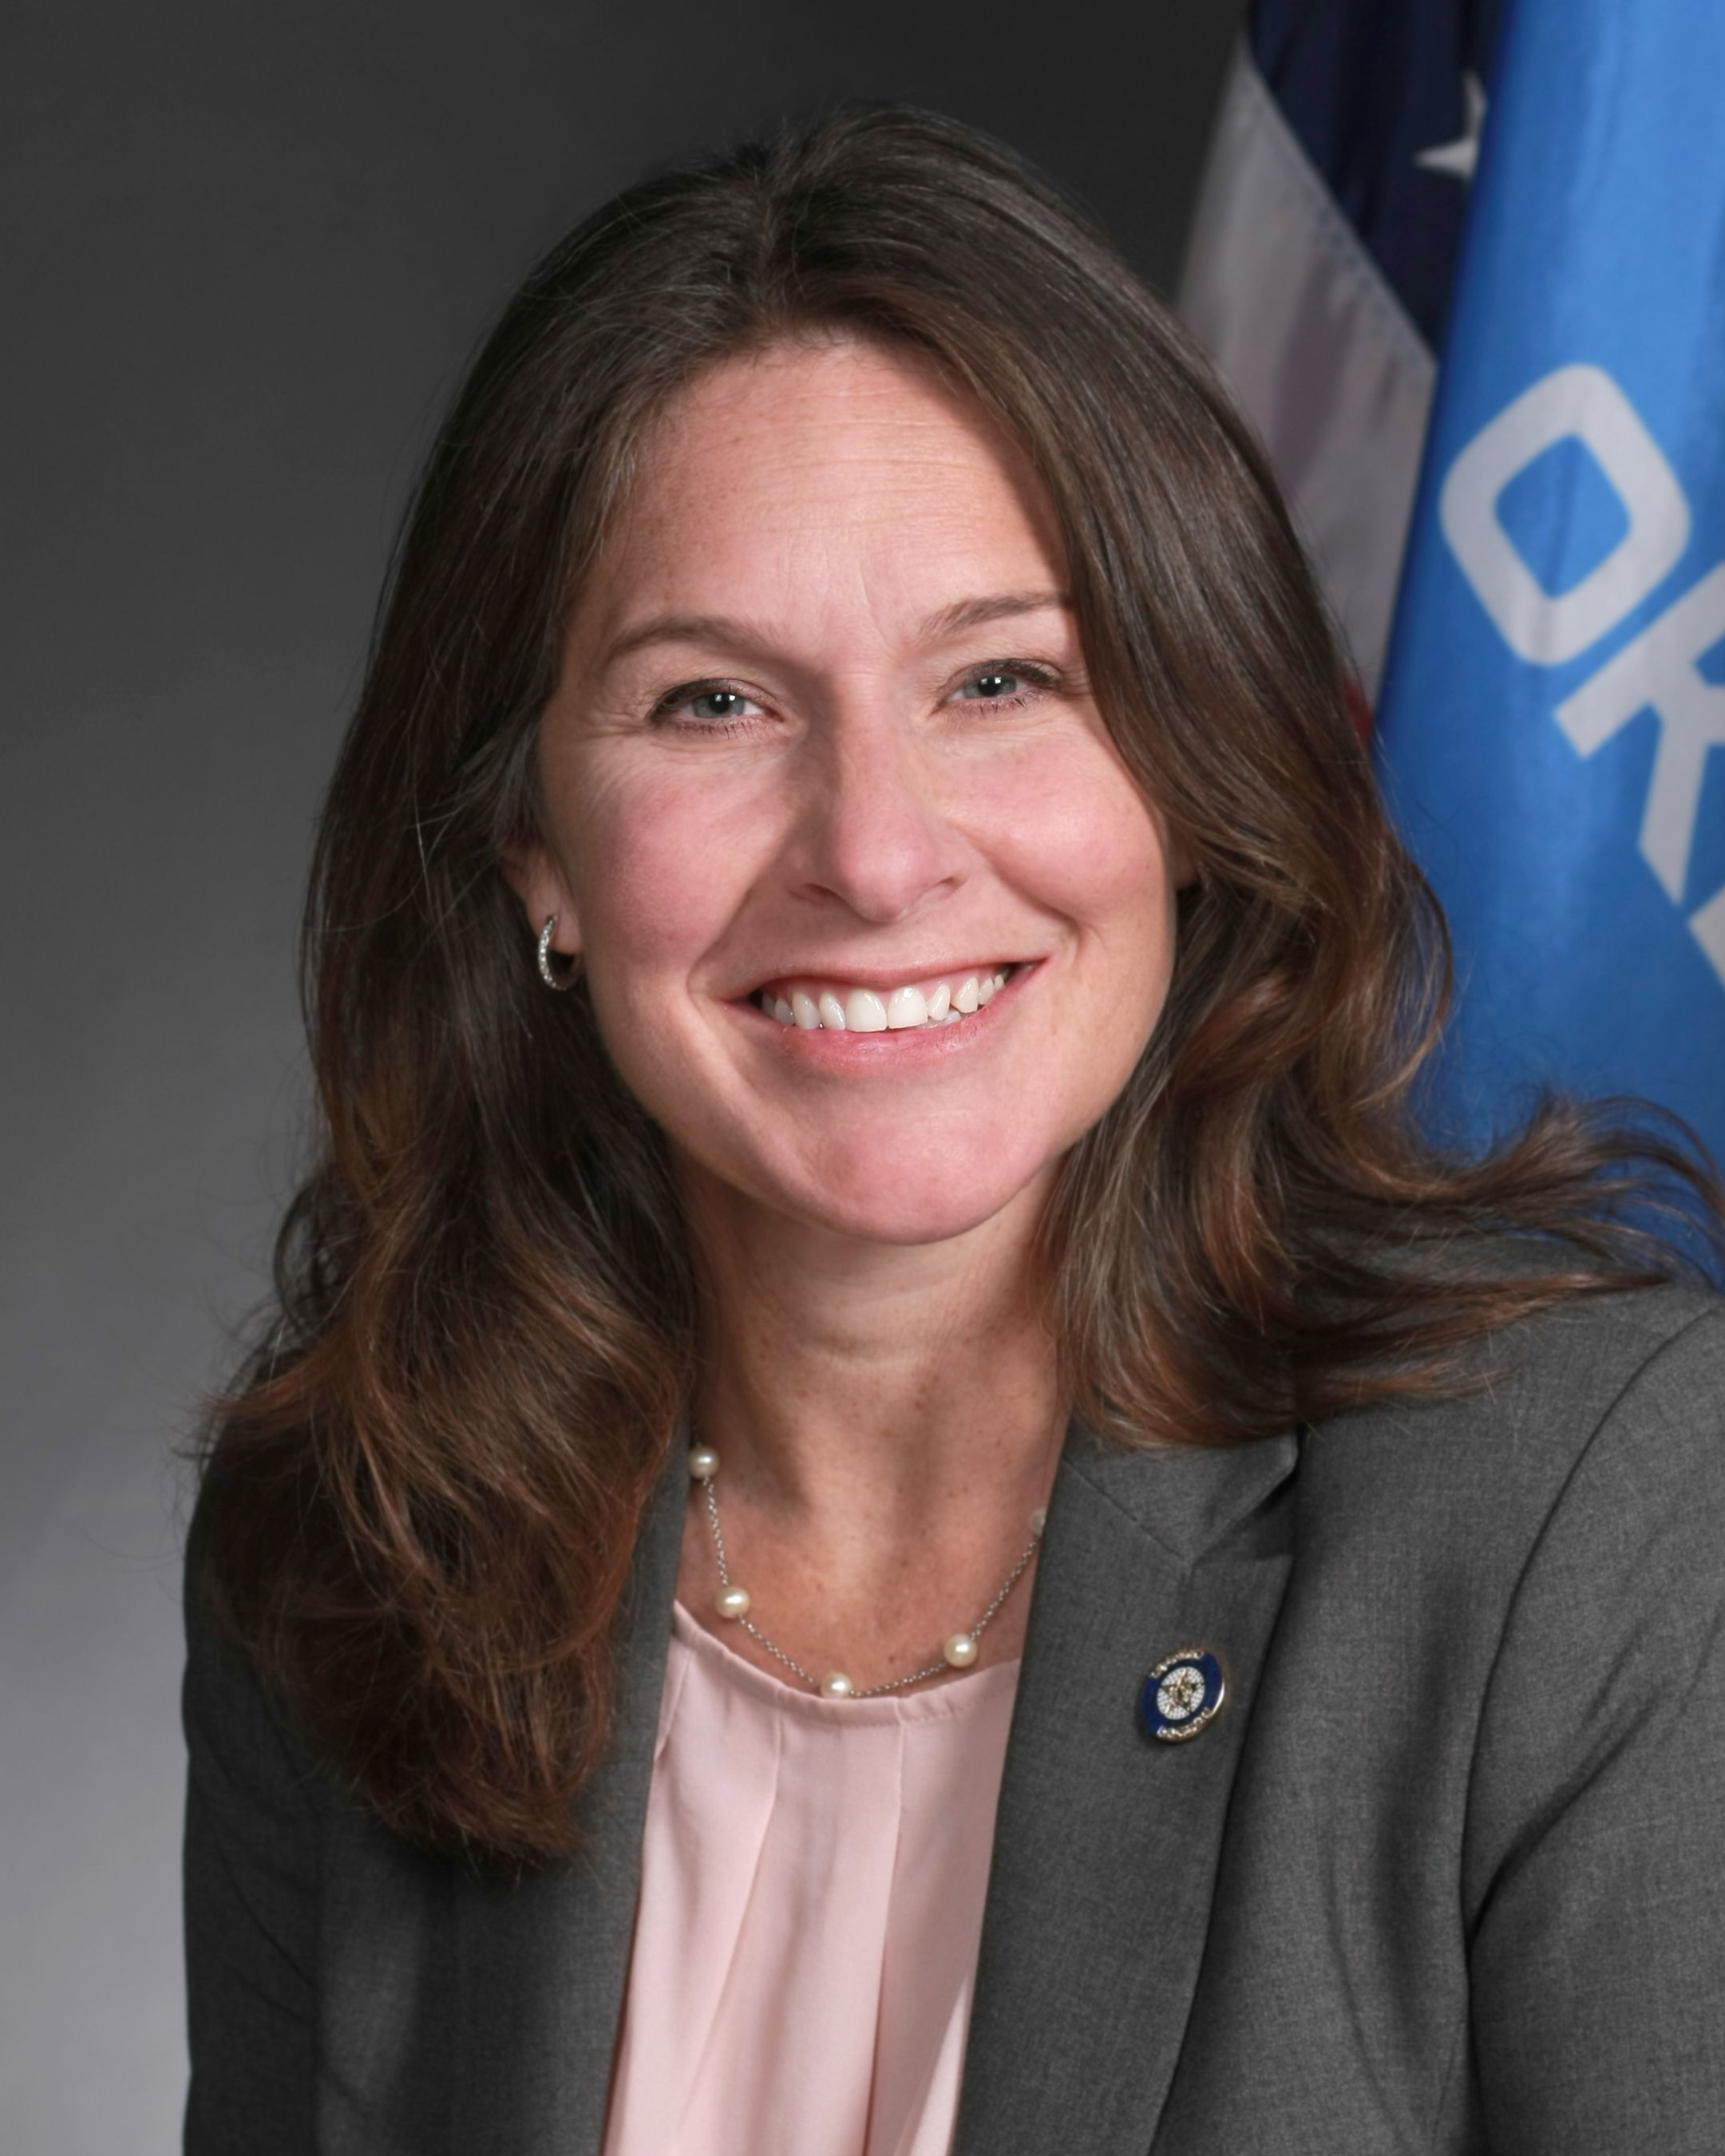
Melissa Provenzano
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 1391
Scope: OK
Hi! I can help you understand HB 1391. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline