

Income tax; modifying rate for certain corporations for certain tax years. Effective date.
SB 323 modifies Oklahoma's individual income tax rates for specific tax years, directly affecting residents who file under the standard tax calculation methods. It changes the tax rate applied to the highest portion of taxable income ("the remainder") from 6.75% for 1999-2001, to 7% for 2002-2003, and to 6.65% for 2004 and later. The bill updates the tax bracket structure described in Section 2355 of Oklahoma's tax code, which determines how income above certain thresholds is taxed. This adjustment affects all Oklahoma individual taxpayers using the standard tax calculation method, not corporations as the title suggests. The changes take effect for the specified tax years beginning after the effective date.
Bill status
in committee
1 of 4 stages cleared
Introduction
Feb 2025
Committee Review
Floor Vote
Governor
Introduced Feb 3, 2025
Last action Feb 4, 2025
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
3
Key actions
0
Committee
0
Feb 3, 2025
Introduced
First Reading
upper
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
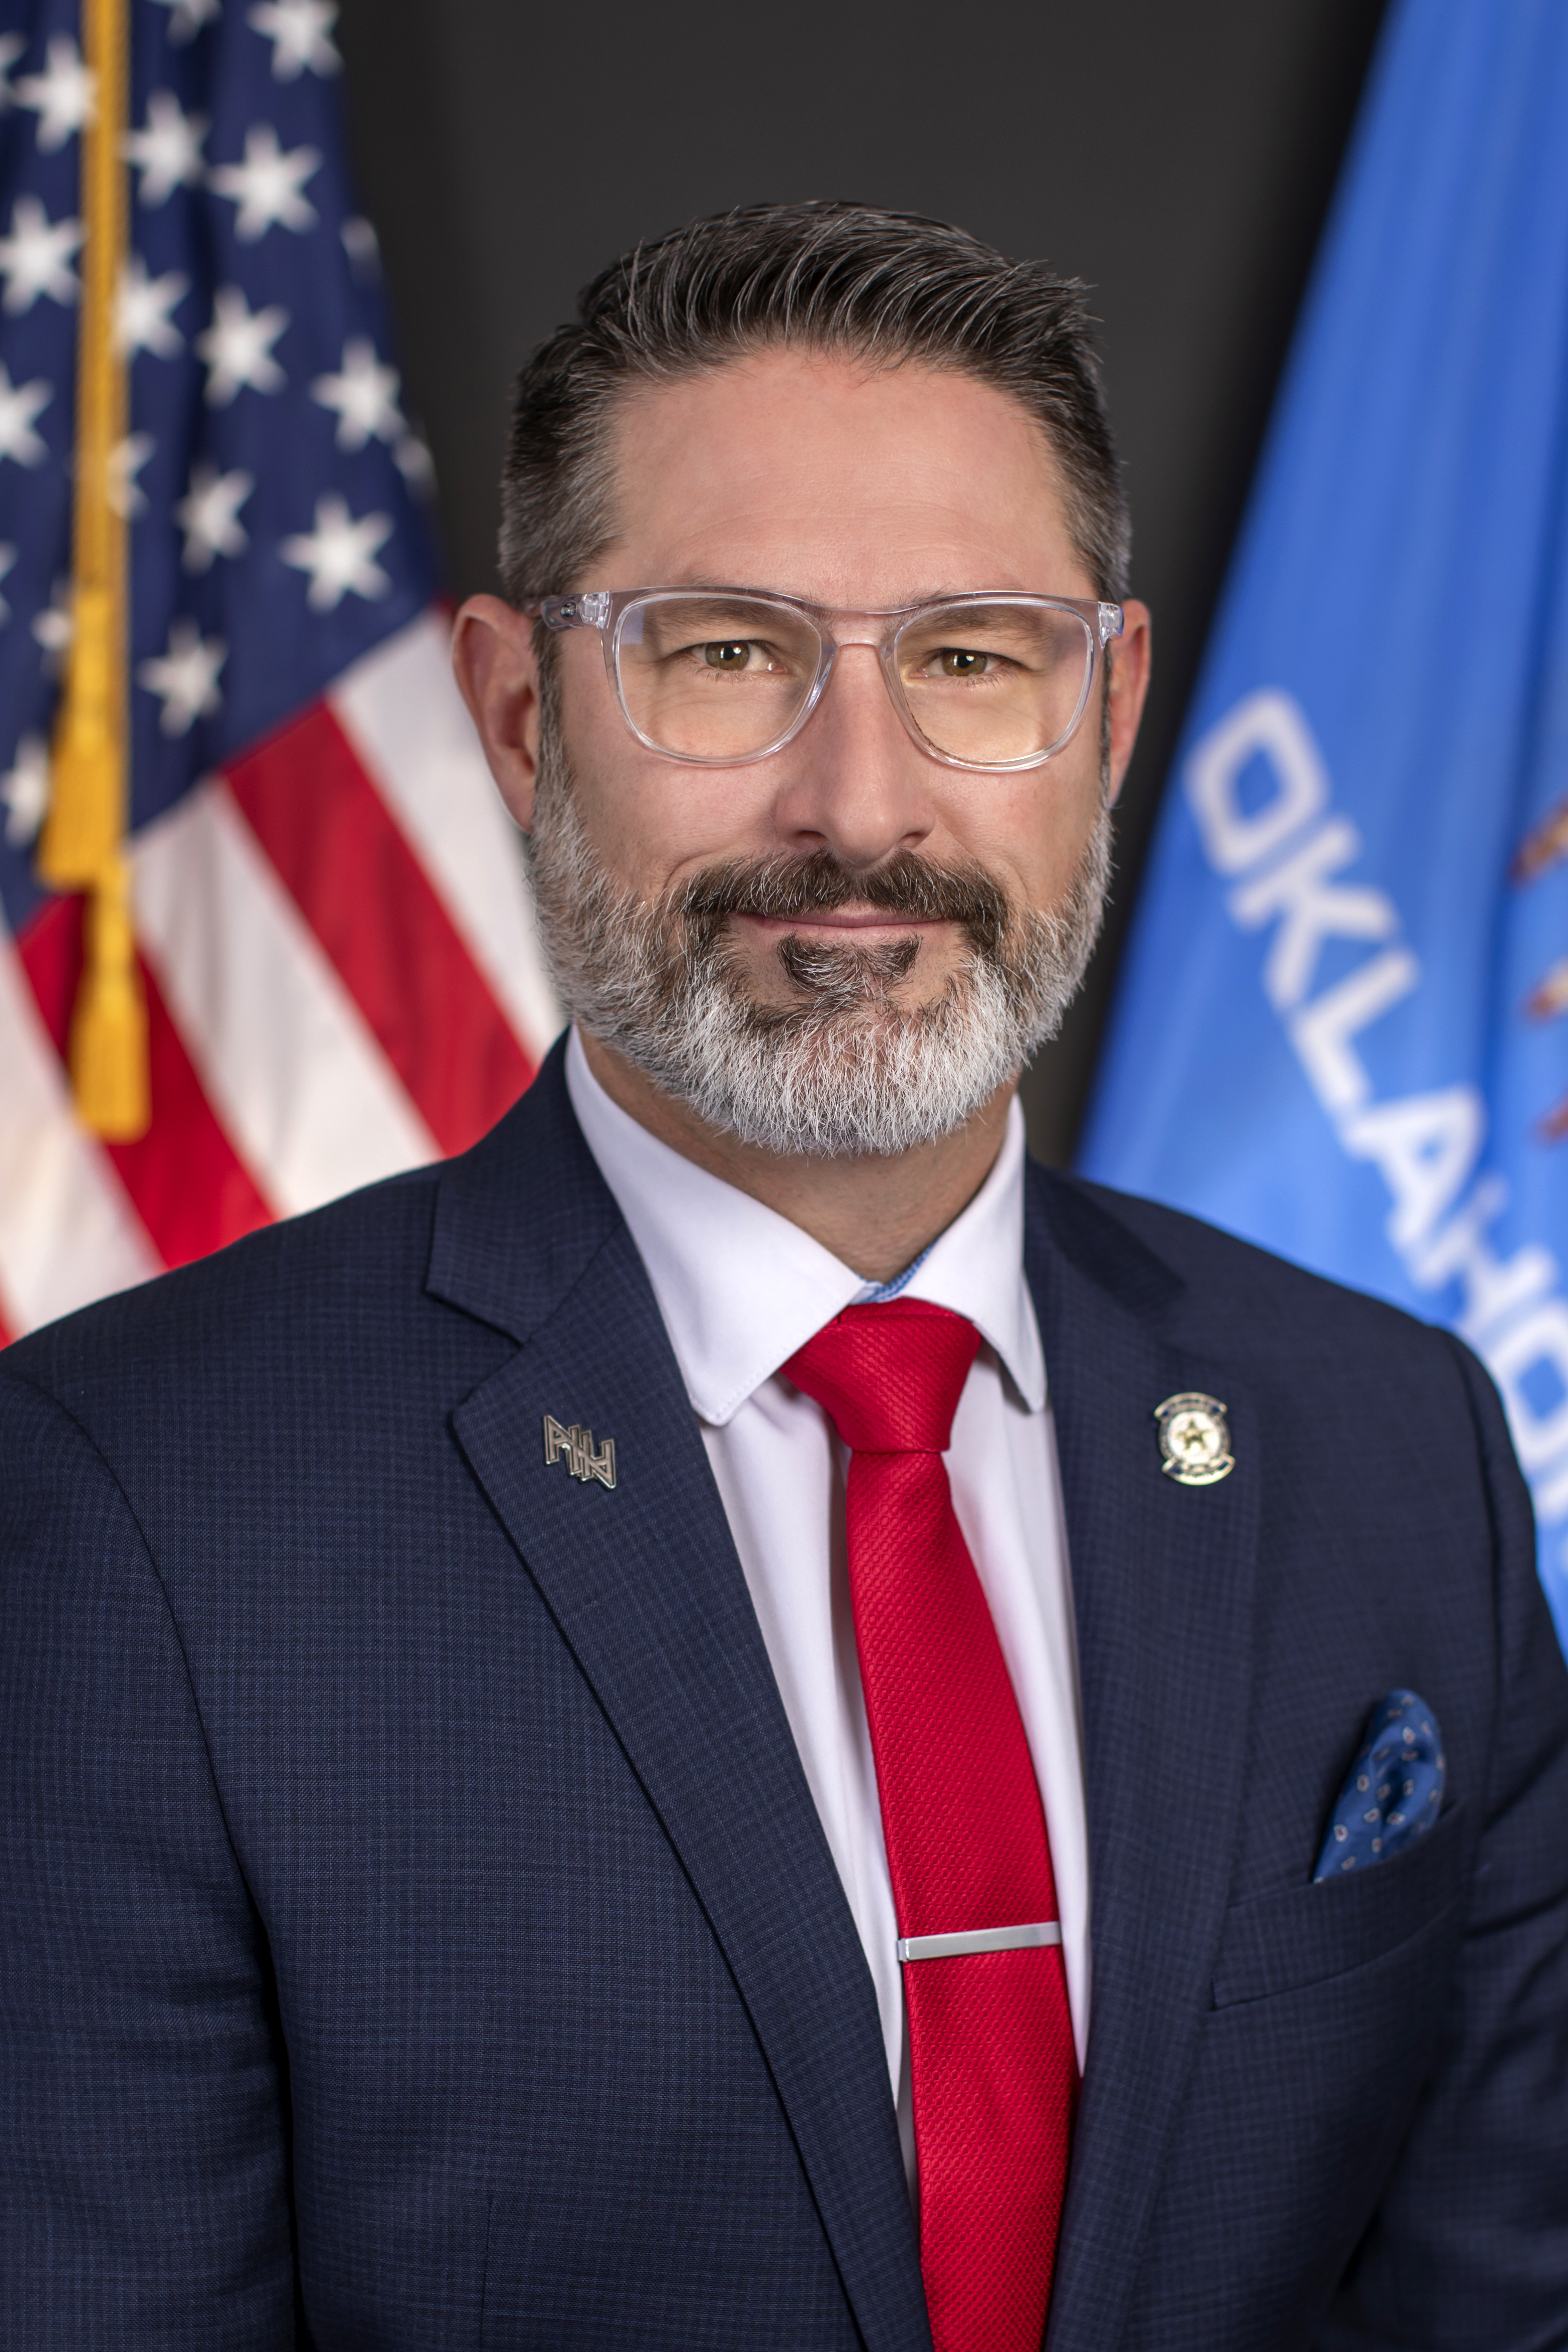
Dusty Deevers
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about SB 323
Scope: OK
Hi! I can help you understand SB 323. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline