

Relates to payments in lieu of taxes
This bill (S 3245) updates how New York local governments and school districts calculate payments in lieu of taxes (PILT) for tax-exempt properties. It requires the Commissioner of Taxation to compute an annual "quantity change factor" showing percentage shifts in taxable property values between specific assessment rolls. This factor must include changes in value for properties under PILT agreements, ensuring these adjustments directly impact local tax revenue calculations. The bill affects municipalities and school districts receiving PILT payments by standardizing how property value changes are factored into their funding.
Bill status
in committee
1 of 4 stages cleared
Introduction
Jan 2025
Committee Review
Floor Vote
Governor
Introduced Jan 24, 2025
Last action Mar 23, 2026
Maddy AI version diff · 1 comparison
What changed between versions
S3245
→
S3245A
·
5 edits
MODERATE
This bill amends New York State laws to clarify how 'payments in lieu of taxes' (PILOTs) are calculated for school districts. It allows local governments and school districts to elect an option where the tax value of PILOTs is included in growth calculations, rather than just the actual payment amount, ensuring tax revenue growth is accurately reflected. The bill also establishes specific procedures for making this election and confirms that the full assessed value of the property is never included in these calculations.
Scope change
The bill expands the scope by adding new elective options for both local governments and school districts to adjust how PILOTs are treated in tax growth formulas, whereas the previous version only addressed the inclusion of PILOT changes.
ELIGIBILITY
Added a new option for local governments to elect including the equivalent taxable value of PILOTs in quantity change factor calculations.
Added a new option for school districts to elect including the equivalent taxable value of PILOTs in their quantity change factor calculations.
REQUIREMENT
Established that these new options must be adopted through a local law or resolution following a public hearing or meeting.
DEFINITION
Clarified that the 'equivalent taxable value' is calculated by dividing the PILOT amount by the applicable tax rate, and explicitly stated that the full assessed value of the property is never included.
TIMELINE
Changed the effective date from one hundred twentieth days after enactment to immediately, with rules to be implemented by the effective date.
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
4
Key actions
2
Committee
2
Amendments
2
Mar 23, 2026
Upper · Passed
PRINT NUMBER 3245A
upper
Mar 23, 2026
Upper · Passed
AMEND AND RECOMMIT TO LOCAL GOVERNMENT
upper
Jan 7, 2026
Committee
REFERRED TO LOCAL GOVERNMENT
upper
Jan 24, 2025
Committee
REFERRED TO LOCAL GOVERNMENT
upper
1 primary · 7 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
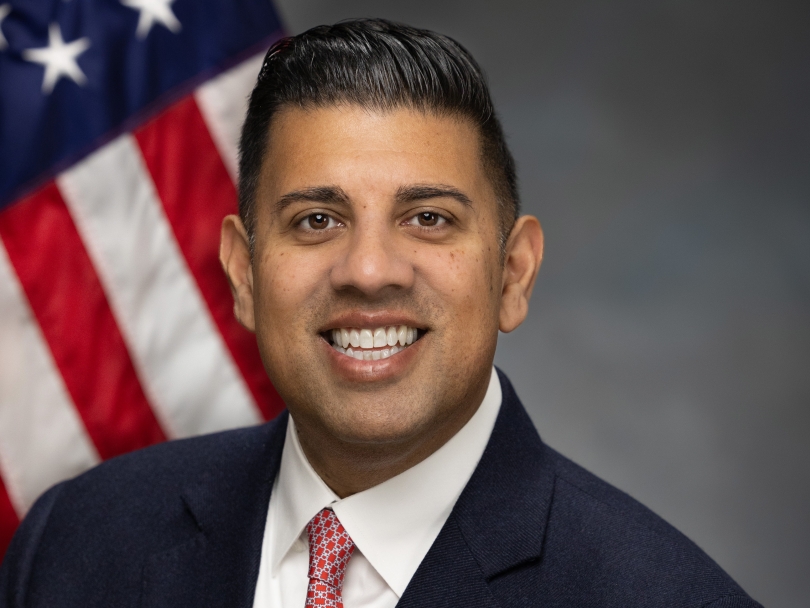
Jeremy Cooney
DDemocratic/Working Families
Co
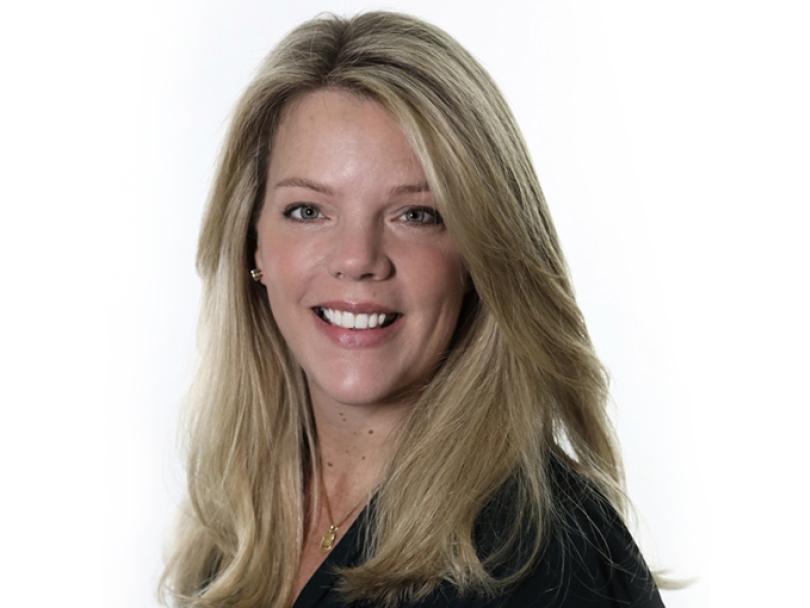
Alexis Weik
RRepublican/Conservative
Co
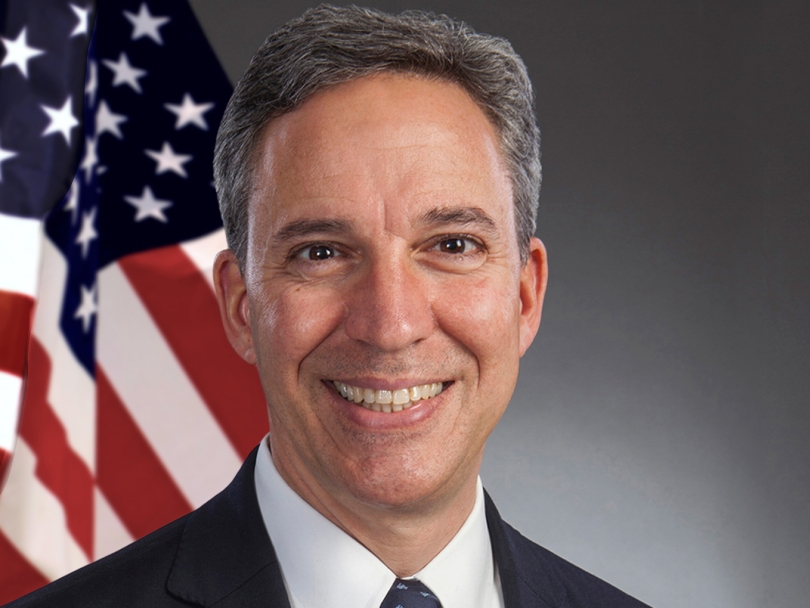
Jack Martins
RRepublican/Conservative
Co
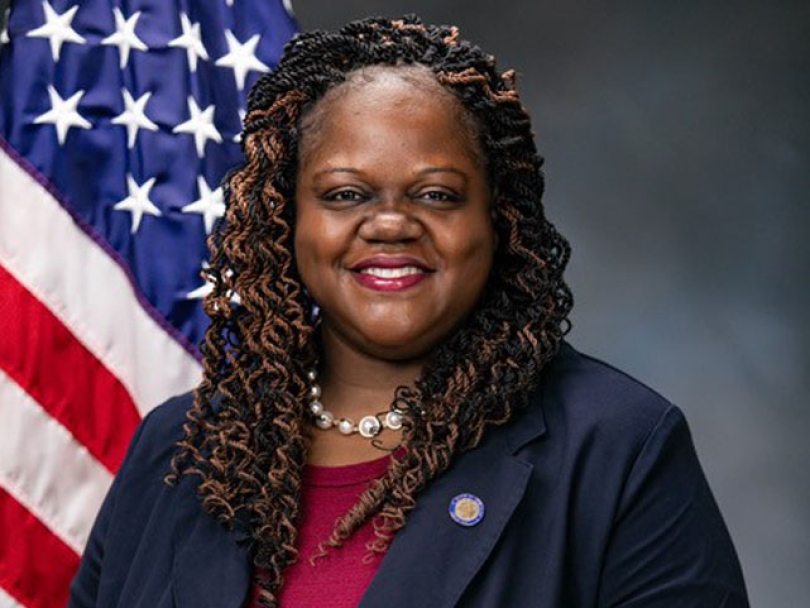
Lea Webb
DDemocratic/Working Families
Co
Pete Harckham
DDemocratic/Working Families
Co
Rachel May
DDemocratic/Working Families
Co
Steve Rhoads
RRepublican/Conservative
Co
Tom O'Mara
RRepublican/Conservative
Ask Maddy
·
AI policy assistant
Ask Maddy about S 3245
Scope: NY
Hi! I can help you understand S 3245. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline