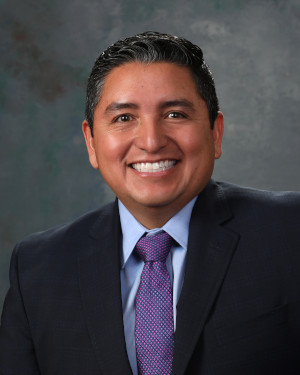
Photo of Derrick Lente
D New Mexico House · District 65 On the 2026 ballot

Rep. Derrick Lente

Compare
Total votes
1,096
all sessions
Attendance
87%
147 missed
Lower than 88% of chamber peers
With party
98%
of cast votes
Near the chamber average
Bipartisan score
1%
crosses aisle rarely
Near the chamber average
Sponsored
28
bills & resolutions
Lower than 84% of chamber peers
Committees
5
assignments
28 bills and resolutions

Sponsored bills

Total
28
Primary
28
Co-sponsor
0
This page
28
matching current filters
Primary HB 374
In committee · New Mexico House · Lead sponsor
PUBLIC PEACE, HEALTH, SAFETY & WELFARE

Maddy summaryHB 374 is a bill introduced in the New Mexico Legislature that relates to public peace, health, safety, and welfare, but it has not advanced beyond the initial committee stage. The bill was introduced by Representative Derrick J. Lente during the 57th Legislature's second session in 2026. As of March 24, 2026, the bill's action was postponed indefinitely, meaning no specific provisions or policy changes have been enacted or detailed in the available text. Without further legislative action, the bill remains inactive and does not currently affect any individuals or programs.

In committee Mar 24, 2026 0 co-sponsors
Primary HB 373
In committee · New Mexico House · Lead sponsor
PUBLIC PEACE, HEALTH, SAFETY & WELFARE

Maddy summaryThe provided context does not include the actual text or summary of HB 373, only its title, introduction details, and a placeholder "Summary:" line. Without specific provisions, mechanisms, or affected parties described in the bill text, a factual summary cannot be generated. The Recent Actions note indicates it is pending before the House Rules and Order of Business Committee but does not describe the bill's content. Therefore, no substantive summary can be provided based on the available information.

In committee Mar 24, 2026 0 co-sponsors
Primary HB 298
In committee · New Mexico House · Lead sponsor
RAIL INFRASTRUCTURE TAX CREDIT

Maddy summaryHB 298 creates a 50% tax credit for New Mexico railroads that spend on qualifying infrastructure projects, such as track repairs, new rail lines, or facilities serving new customers. The credit directly affects railroads classified as Class 2 or 3 by the federal government or owners/lessees of rail spurs in New Mexico, with limits of $5,000 per mile of track owned/leased and $1 million per new customer project. To claim the credit, railroads must first get DOT certification, and the total annual credits issued cannot exceed $6 million. The bill allows credits to be transferred between taxpayers but does not refund excess credit amounts beyond a taxpayer’s liability in a given year.

In committee Mar 24, 2026 0 co-sponsors
Primary HB 296
In committee · New Mexico House · Lead sponsor
INCREASE WORKING FAMILY TAX CREDIT

Maddy summaryHB 296 increases New Mexico's Working Families Tax Credit to 50% of the federal Earned Income Tax Credit (EITC) for eligible residents, up from previous rates of 20-25%. It directly affects low-to-moderate income New Mexico residents who file individual state tax returns and qualify for the federal EITC, including those aged 18-24 who previously faced age-based barriers. The bill allows the credit to reduce state tax liability, with any excess refunded to taxpayers. This change takes effect for tax years beginning January 1, 2026, as specified in Section 7-2-18.15 of New Mexico's tax code.

In committee Mar 24, 2026 0 co-sponsors
Primary HM 64
In committee · New Mexico House · Lead sponsor
BUILD CAPACITY FOR CAPITAL OUTLAY CHANGES

Maddy summaryThis House Memorial (HM 64) is a non-binding request urging New Mexico's Indian Affairs Department to build capacity for providing technical assistance to the state's Indian nations, tribes, and pueblos. It specifically asks the department to prepare for more efficient support regarding capital outlay projects - funded from the general state budget - amid pending legislative changes to the capital outlay process. The memorial does not change policy but formally encourages the department to strengthen its ability to help tribal entities access and manage these funds. (Note: As a memorial, it has no legal force but expresses legislative intent.)

In committee Mar 24, 2026 0 co-sponsors
Primary HB 148
died · New Mexico House · Lead sponsor
PROPERTY TAX AFFIDAVITS

Maddy summaryHB 148 creates a temporary 5% annual cap on increases in property tax valuations for nonresidential properties (like offices or stores) from 2026 through 2036, affecting commercial property owners. It also updates requirements for residential property transfers, mandating that sellers or buyers submit an affidavit with specific details (names, sale price, property description) to county assessors within 30 days of a transfer, but excluding many common transactions like family transfers, government deals, or leases. The bill explicitly states these affidavits are for statistical use only and cannot be used in property valuation. Exceptions to the valuation cap include new properties, expansions after disasters, or changes in property zoning.

died Mar 24, 2026 0 co-sponsors
Primary HB 332
Signed into law · New Mexico House · Lead sponsor
CAPITAL OUTLAY REAUTHORIZATIONS

Maddy summaryHB 332 reauthorizes and adjusts the use of existing state funds for specific capital projects, primarily extending their spending deadlines to fiscal year 2028 and modifying project purposes. It changes the original use of funds for the Lea County courthouse renovation (now for general county buildings) and expands the Albuquerque youth facility project to include young adults. The bill also extends timelines for a Navajo Nation bridge project and redirects unspent funds from a Curry County recreation complex to renovate a local park. These adjustments apply to previously appropriated funds without creating new spending, focusing on managing unspent balances from prior legislative actions.

Signed into law Mar 11, 2026 0 co-sponsors
Primary HB 248
Signed into law · New Mexico House · Lead sponsor
GENERAL OBLIGATION BONDS

Maddy summaryHB 248 authorizes New Mexico to issue $500 million in general obligation bonds to fund capital projects including senior centers statewide, higher education facilities, and public libraries. The bonds would be paid through a new property tax levy on all taxable property in the state, with principal and interest due over a maximum 10-year term. Voter approval via a statewide referendum at the 2026 general election is required before the bonds can be issued. This bill creates a new state debt obligation backed by the full faith and credit of New Mexico, directly affecting taxpayers through the property tax mechanism.

Signed into law Mar 10, 2026 0 co-sponsors
Primary HB 247
Signed into law · New Mexico House · Lead sponsor
CAPITAL OUTLAY CHANGES

Maddy summaryHB 247 limits how New Mexico state agencies can manage capital projects (like construction or equipment purchases) by requiring unspent funds to revert to specific state funds. It prohibits reauthorizing projects more than once or for over two years unless 10% of the initial funds are already committed, and mandates that projects over $100,000 must align with an approved infrastructure plan. Unspent general fund capital appropriations must revert to the Capital Development and Reserve Fund (or Tribal Infrastructure Fund for tribal projects) by specific deadlines, with water projects now requiring state agency grant programs instead of direct legislative funding. The bill updates prior laws (2022-2025) to enforce these reversion timelines and spending rules.

Signed into law Mar 10, 2026 0 co-sponsors
Primary HB 291
Signed into law · New Mexico House · Lead sponsor
TAX CHANGES

Maddy summaryHB 291 makes several specific changes to New Mexico tax procedures. It sets a $5 minimum civil penalty for failures to pay certain taxes (withholding, oil/gas, workers' comp fees), clarifies that taxpayers with approved payment plans aren't considered delinquent for license renewals, and allows attorney fees to be paid from tax revenue distributions. The bill also prevents interest from accruing during granted filing extensions and modifies rounding requirements for tax calculations. These changes directly affect taxpayers, businesses, and the state's tax administration processes.

Signed into law Mar 5, 2026 0 co-sponsors
Showing 1 to 10 of 28 bills