

Provides gross income tax exclusion for distributions from individual retirement accounts to qualified charitable organizations.
This New Jersey bill (S 1042) would exclude charitable distributions from individual retirement accounts (IRAs) to qualified organizations from state gross income tax. It directly affects New Jersey residents who make direct gifts from their IRAs to eligible charities. The key provision amends the state tax code to add a specific exclusion for these contributions, meaning donors would not owe New Jersey income tax on the gifted amount. This change applies only to distributions made to organizations meeting federal tax-exempt criteria.
Bill status
in committee
1 of 4 stages cleared
Introduction
Jan 2026
Committee Review
Floor Vote
Governor
Introduced Jan 13, 2026
Last action Jan 13, 2026
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
1
Key actions
0
Committee
0
Jan 13, 2026
Introduced
Introduced in the Senate, Referred to Senate State Government, Wagering, Tourism & Historic Preservation Committee
upper
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
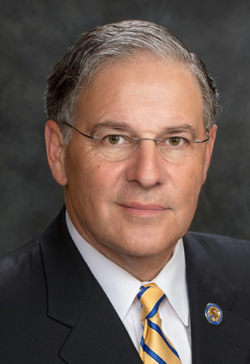
Jon Bramnick
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about S 1042
Scope: NJ
Hi! I can help you understand S 1042. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline