

Modify tax classification of shooting ranges
SB 247 classifies certain nonprofit shooting ranges as "Class four property" for taxation purposes, affecting organizations that operate these ranges and are exempt under 26 U.S.C. 501(c)(3) or 501(c)(4). The bill establishes a specific property tax rate for these qualifying ranges, taxing them at one-half the rate applied to general commercial property. It defines a "shooting range" as the necessary buildings, improvements, and up to 150 acres of appurtenant land, excluding residential or general commercial business uses. These changes will apply to tax years beginning after December 31, 2025.
Bill status
signed
all 5 stages cleared
Introduction
Jan 2025
Committee Review
Apr 2025
Senate Passage
Apr 2025
House Passage
Apr 2025
Signed into Law
May 2025
Introduced Jan 30, 2025
Signed May 13, 2025
Maddy AI version diff · 4 comparisons
What changed between versions
SB0247_X(2).pdf
→
SB0247_X(3).pdf
·
2 edits
MINOR
The bill text was slightly cleaned up by removing unnecessary quotation marks and extra blank lines, but the core policy content remains the same. The most significant substantive change is the effective date, which is set to apply to tax years beginning after December 31, 2025, meaning the new tax rules for shooting ranges will not take effect until the 2026 tax year.
Scope change
The bill's applicability is now explicitly defined to begin after December 31, 2025, delaying the implementation of the revised shooting range tax rate until the 2026 tax year.
TIMELINE
The effective date for the new tax rate on shooting ranges was established to apply to tax years starting after December 31, 2025.
TECHNICAL
Minor formatting adjustments were made, including the removal of closing quotation marks and extra blank lines from the header and footer sections.
Floor votes · Senate Apr 2, 2025 · House Apr 16, 2025
How they voted
49–1
Passed
Total votes 50
Apr 2, 2025
D
Democratic18
100% Yea
R
Republican32
96% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
45
Key actions
9
Committee
6
May 9, 2025
Signed into law
(S) Signed by Governor
upper
Apr 29, 2025
Lower · Passed
(H) Signed by Speaker
lower
Apr 23, 2025
Upper · Passed
(S) Signed by President
upper
Apr 16, 2025
House · Passed
House Vote: pass (57-41-2)
house
Apr 9, 2025
Lower · Passed
(H) Committee Report - (H) Taxation
lower
Apr 9, 2025
Lower · Passed
(H) Committee Executive Action - (H) Taxation
lower
Apr 3, 2025
Committee
(H) Referred to Committee - (H) Taxation
lower
Apr 2, 2025
Senate · Passed
Senate Vote: pass (49-1)
senate
Mar 20, 2025
Upper · Passed
(S) Committee Report - (S) Taxation
upper
Mar 19, 2025
Upper · Passed
(S) Committee Executive Action - (S) Taxation
upper
Feb 5, 2025
Committee
(S) Referred to Committee - (S) Taxation
upper
Jan 30, 2025
Introduced
(S) Introduced
upper
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
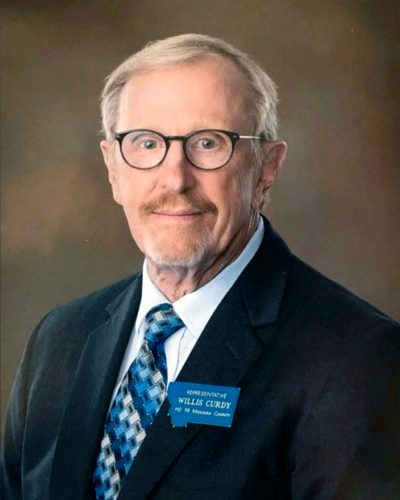
Willis Curdy
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about SB 247
Scope: MT
Hi! I can help you understand SB 247. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline