

Revise insurance laws relating to wildfire and real property
HB 533 requires insurance companies that use wildfire risk scores to underwrite or rate real property insurance to provide specific information to insureds or applicants upon request. This bill directly affects admitted insurers in the state and individuals seeking or holding property insurance. Upon request, insurers must disclose the property's current wildfire risk score, the range of possible scores, the score's creator, its creation date, and the main factors that negatively influenced the score. Insurers are required to provide this information in writing within 15 days of receiving a request.
Bill status
signed
all 5 stages cleared
Introduction
Feb 2025
Committee Review
Mar 2025
House Passage
Apr 2025
Senate Passage
May 2025
Signed into Law
May 2025
Introduced Feb 18, 2025
Signed May 13, 2025
Maddy AI version diff · 6 comparisons
What changed between versions
HB0533_X(1).pdf
→
HB0533_X(2).pdf
·
4 edits
MODERATE
The bill clarifies that wildfire risk scores apply specifically to residential property evaluation and rating, streamlines the disclosure requirements for insurers, and extends the response timeline for providing wildfire risk score information to 30 days from the original 15 days. These changes aim to improve transparency for homeowners while giving insurers a reasonable timeframe to gather and provide risk assessment data.
Scope change
The bill's scope is narrowed to explicitly apply only to residential real property rather than all property types, and the definition of wildfire risk score is refined to focus on measuring or assessing wildfire risk for residential property purposes.
REQUIREMENT
Changed disclosure requirements to specify that insurers must provide wildfire risk score information to insureds or applicants to enhance transparency, with clearer language about what information must be shared.
TIMELINE
Extended the timeline for insurers to respond to requests for wildfire risk score information from 15 days to 30 days.
DEFINITION
Refined the definition of wildfire risk score to clarify it measures or assesses wildfire risk for residential property specifically, rather than predicting future wildfire-related insurance loss exposure.
SCOPE
Narrowed the application of wildfire risk score requirements to residential real property only, removing broader property evaluation language.
Floor votes · Senate Apr 7, 2025 · House Apr 16, 2025
How they voted
49–0
Passed · 1 other
Total votes 50
Apr 7, 2025
D
Democratic18
94% Yea
R
Republican32
100% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
44
Key actions
9
Committee
6
Amendments
1
May 8, 2025
Signed into law
(H) Signed by Governor
lower
May 2, 2025
Upper · Passed
(S) Signed by President
upper
Apr 29, 2025
Lower · Passed
(H) Signed by Speaker
lower
Apr 16, 2025
House · Passed
House Vote: pass (96-1-3)
house
Apr 7, 2025
Senate · Passed
Senate Vote: pass (49-0-1)
senate
Apr 7, 2025
Introduced
(S) Returned to House with Amendments
upper
Mar 28, 2025
Upper · Passed
(S) Committee Report - (S) Business, Labor and Economic Affairs
upper
Mar 28, 2025
Upper · Passed
(S) Committee Executive Action - (S) Business, Labor and Economic Affairs
upper
Mar 14, 2025
Committee
(S) Referred to Committee - (S) Business, Labor and Economic Affairs
upper
Feb 28, 2025
Lower · Passed
(H) Committee Report - (H) Business and Labor
lower
Feb 27, 2025
Lower · Passed
(H) Committee Executive Action - (H) Business and Labor
lower
Feb 18, 2025
Committee
(H) Referred to Committee - (H) Business and Labor
lower
Feb 18, 2025
Introduced
(H) Introduced
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
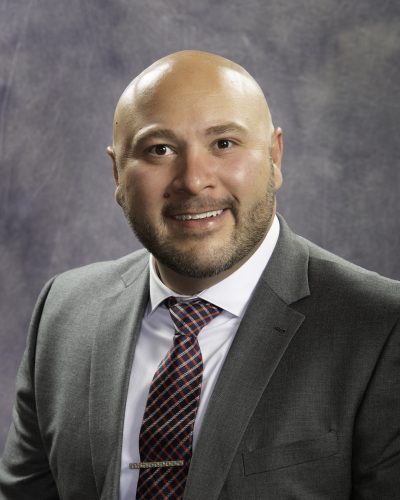
Curtis Schomer
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 533
Scope: MT
Hi! I can help you understand HB 533. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline