

Consumer credit: interest rates; prepayment penalties on certain mortgage loans made for business purposes; allow. Amends sec. 1c of 1966 PA 326 (MCL 438.31c).
HB 5552 amends Michigan's interest rate law to allow lenders to charge higher interest rates on mortgage loans made primarily for business purposes, removing state rate limits for these loans. It also prohibits prepayment penalties exceeding 1% of the loan amount for personal/family home loans within the first three years, with no penalties allowed after that period. The bill sets a maximum 11% annual interest rate for certain other mortgage types, including purchase money mortgages and second mortgages, inclusive of all finance charges. This affects lenders and borrowers involved in business-purpose mortgages, personal/family home loans, and specific second mortgages under Michigan law.
Bill status
passed both
4 of 5 stages cleared
Introduction
Feb 2026
Committee Review
Jun 2026
House Passage
May 2026
Senate Passage
Jun 2026
Governor
Introduced Feb 19, 2026
Last action Jun 2, 2026
Maddy AI version diff · 1 comparison
What changed between versions
House Introduced Bill
→
As Passed by the House
·
5 edits
·
May 21, 2026
MODERATE
The bill was restructured from a committee referral document into a formal enacted law. It clarifies interest rate rules for various loans, including those secured by real property, mobile homes, and purchase money mortgages, while adding specific exemptions for federally insured loans and trust plans. The text also introduces new definitions for 'affiliate' and 'regulated depository financial institution' to support biweekly payment provisions.
Scope change
The bill's scope expanded from a draft introduction to a full statutory enactment, adding specific definitions and exemptions that were missing in the original draft.
DEFINITION
Added new definitions for 'affiliate' and 'regulated depository financial institution' to clarify who can require interest-bearing accounts for biweekly loan payments.
EXEMPTIONS
Explicitly exempted loans insured or guaranteed by the federal government and certain trust plans from the act's interest rate limitations.
REQUIREMENT
Reorganized the text to clearly list lender restrictions on deposits, fees, and prepayment penalties for single-family home loans.
ENFORCEMENT
Added a provision allowing parties to seek injunctive court orders to enforce their rights under the act.
TECHNICAL
Removed committee referral text, page numbers, and internal tracking codes, replacing them with the standard 'The People of the State of Michigan Enact' language.
Floor votes · House May 21, 2026
How they voted
This bill passed the Senate by voice vote (no roll call recorded).
Full legislative history
Actions timeline
Total actions
13
Key actions
3
Committee
4
Jun 2, 2026
Committee
REFERRED TO COMMITTEE ON FINANCE, INSURANCE, AND CONSUMER PROTECTION
upper
Jun 2, 2026
Upper · Passed
PASSED BY HOUSE WITH IMMEDIATE EFFECT
upper
May 21, 2026
Lower · Passed
passed; given immediate effect Roll Call #164 Yeas 81 Nays 26 Excused 0 Not Voting 3
lower
Mar 17, 2026
Committee
referred to second reading
lower
Mar 17, 2026
Lower · Passed
reported with recommendation without amendment
lower
Feb 19, 2026
Committee
referred to Committee on Finance
lower
Feb 19, 2026
Introduced
introduced by Representative Rep. Mark Tisdel
lower
1 primary · 3 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
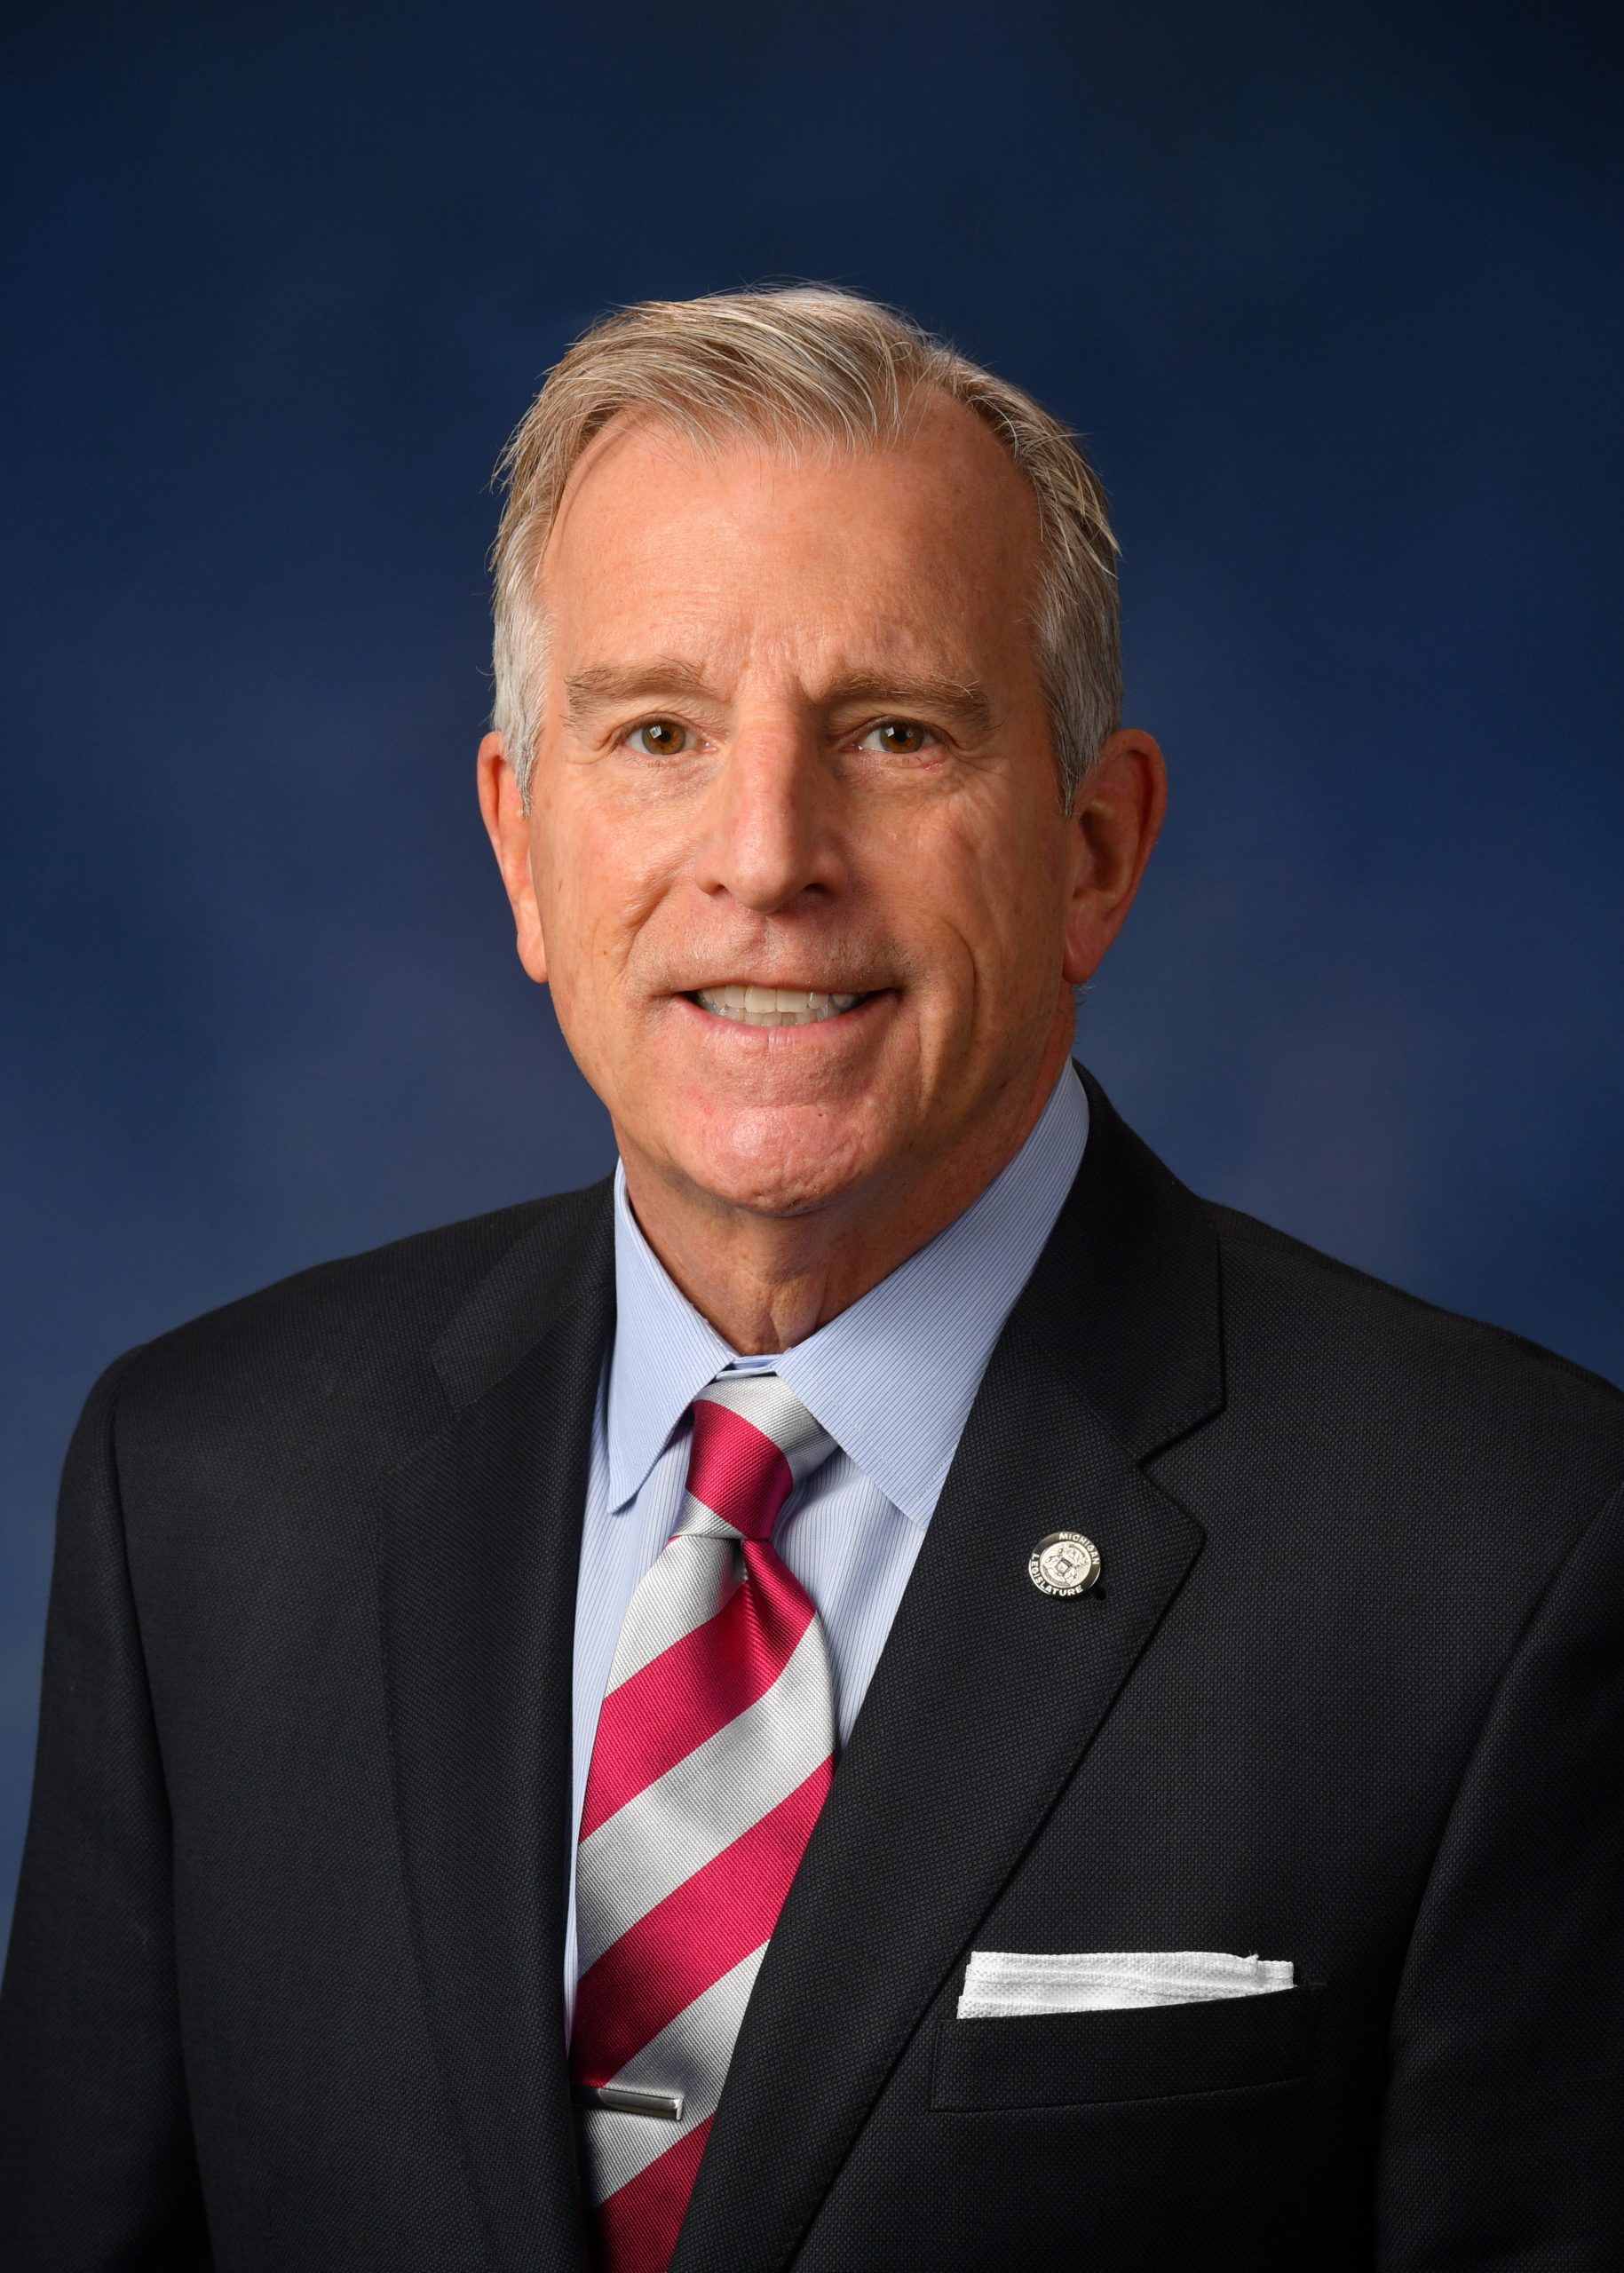
Mark Tisdel
RRepublican
Co
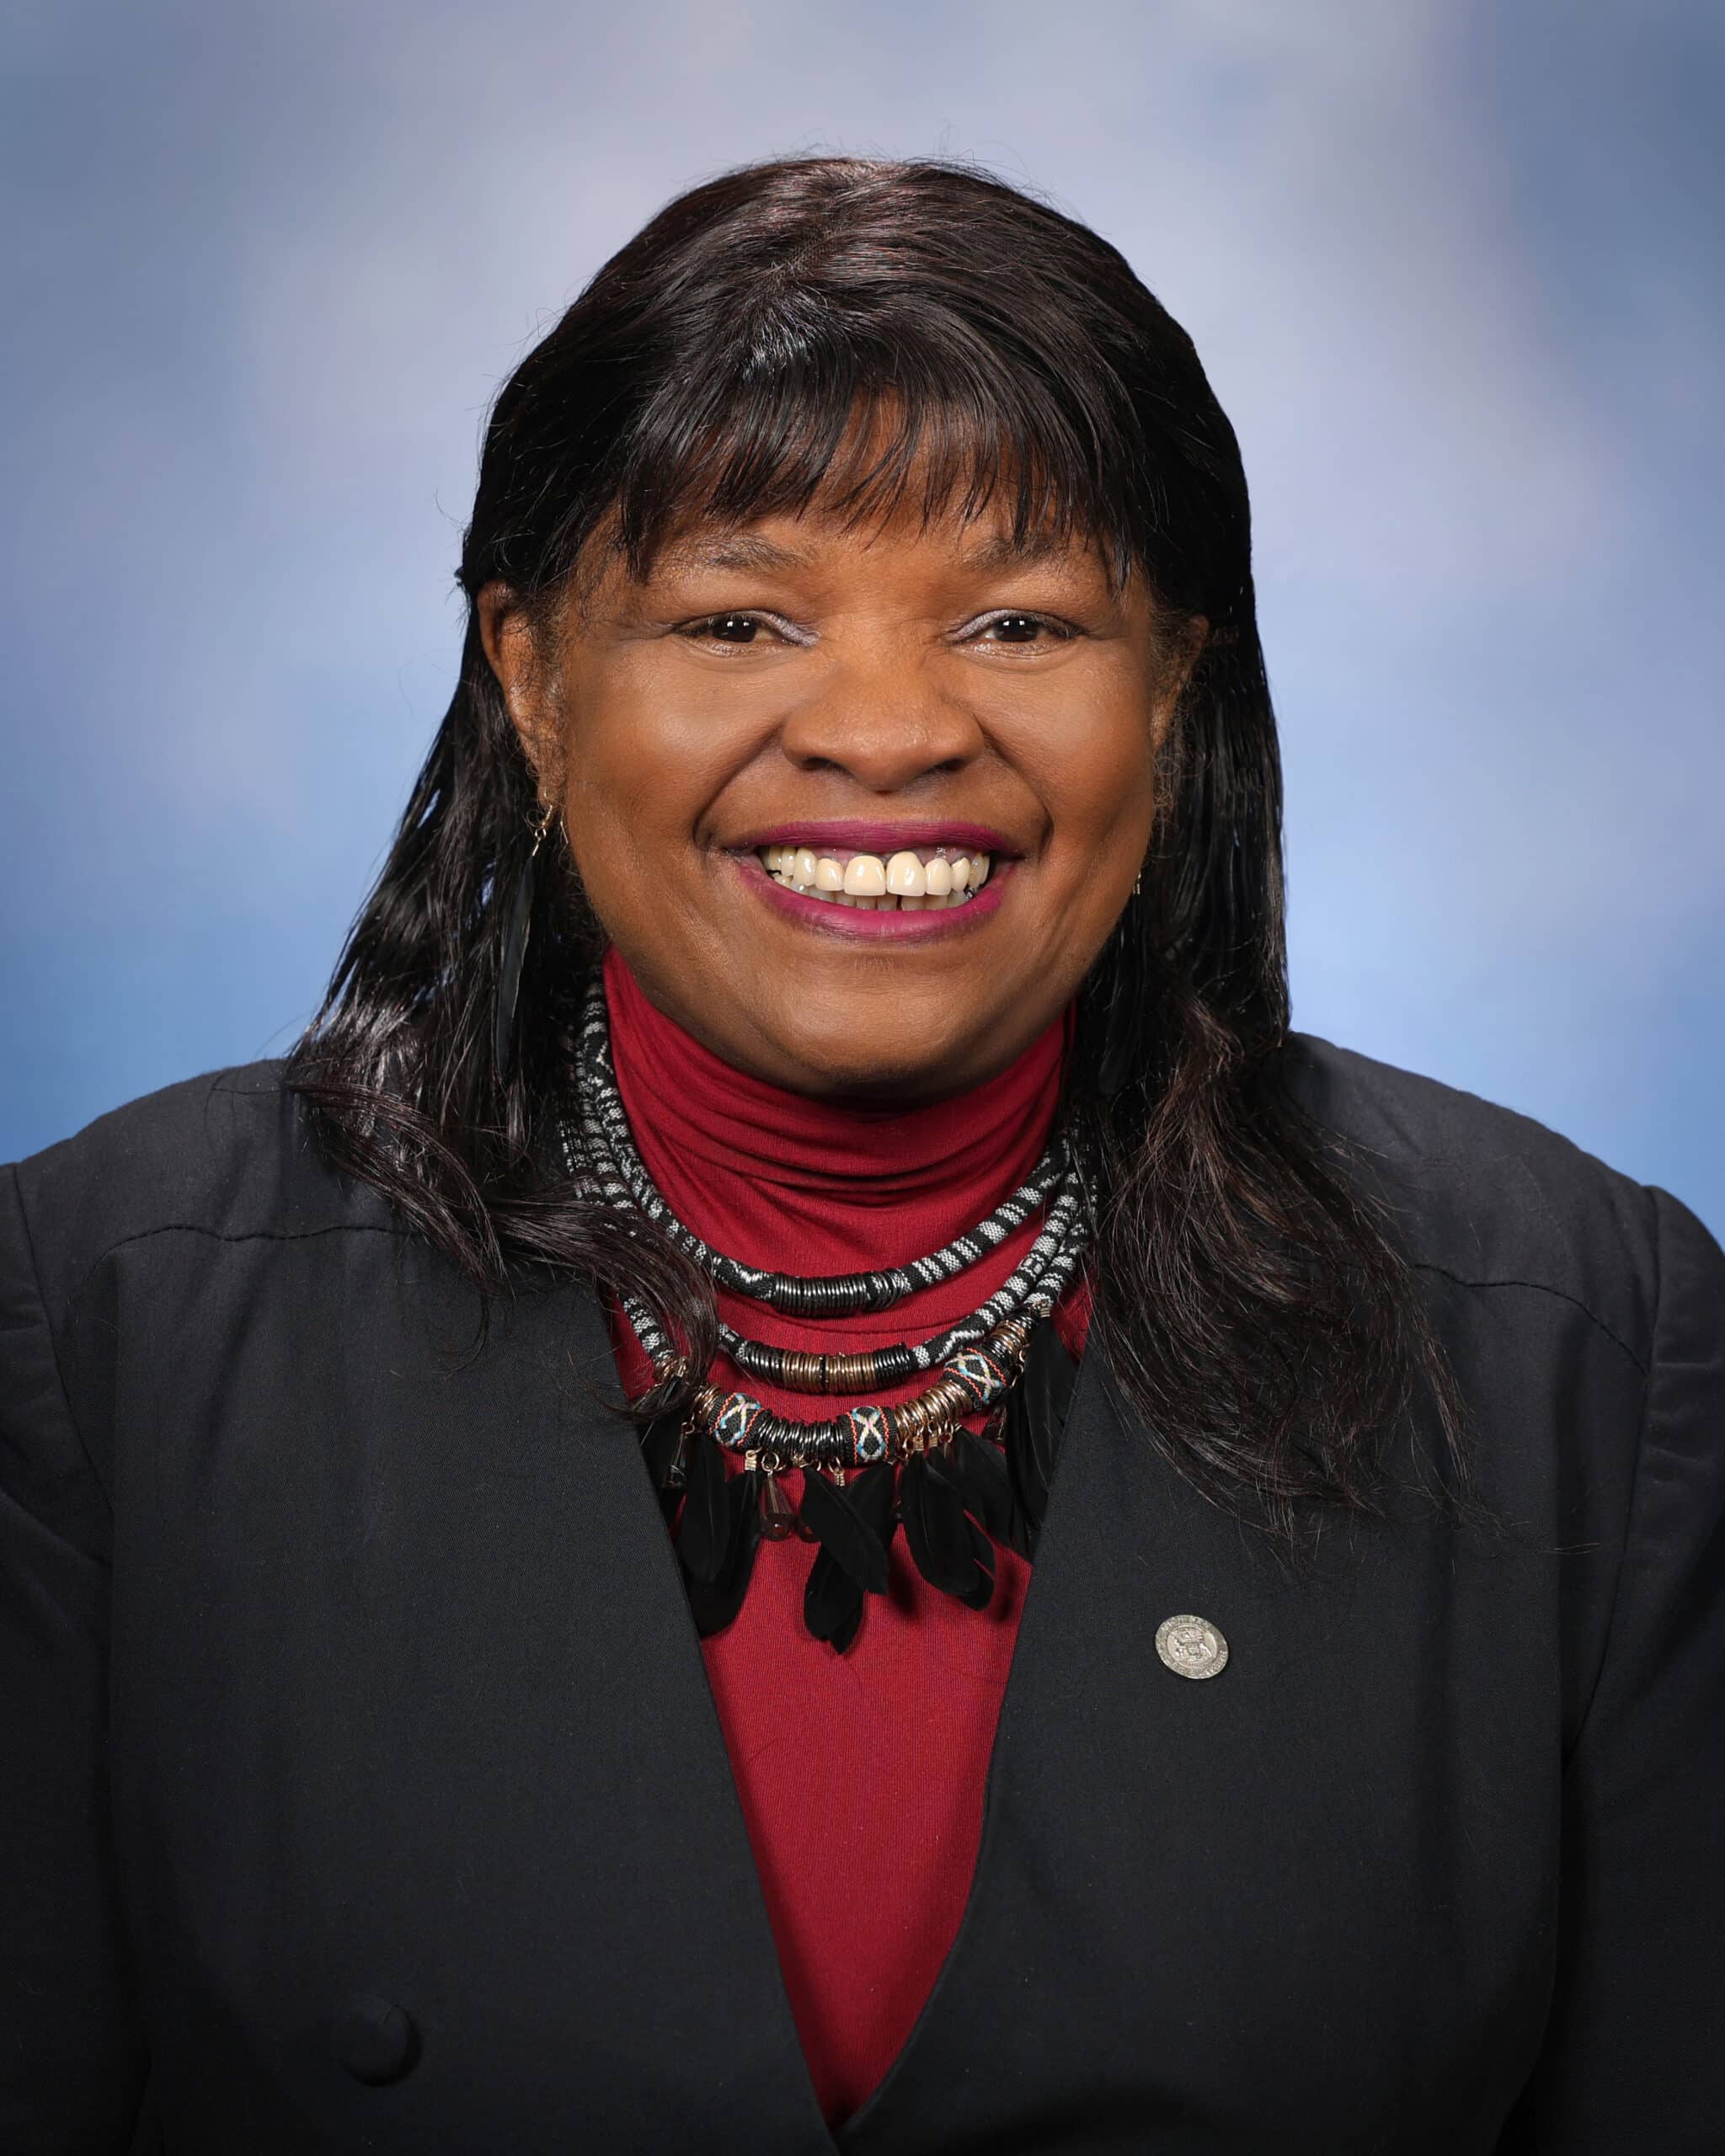
Brenda Carter
DDemocratic
Co
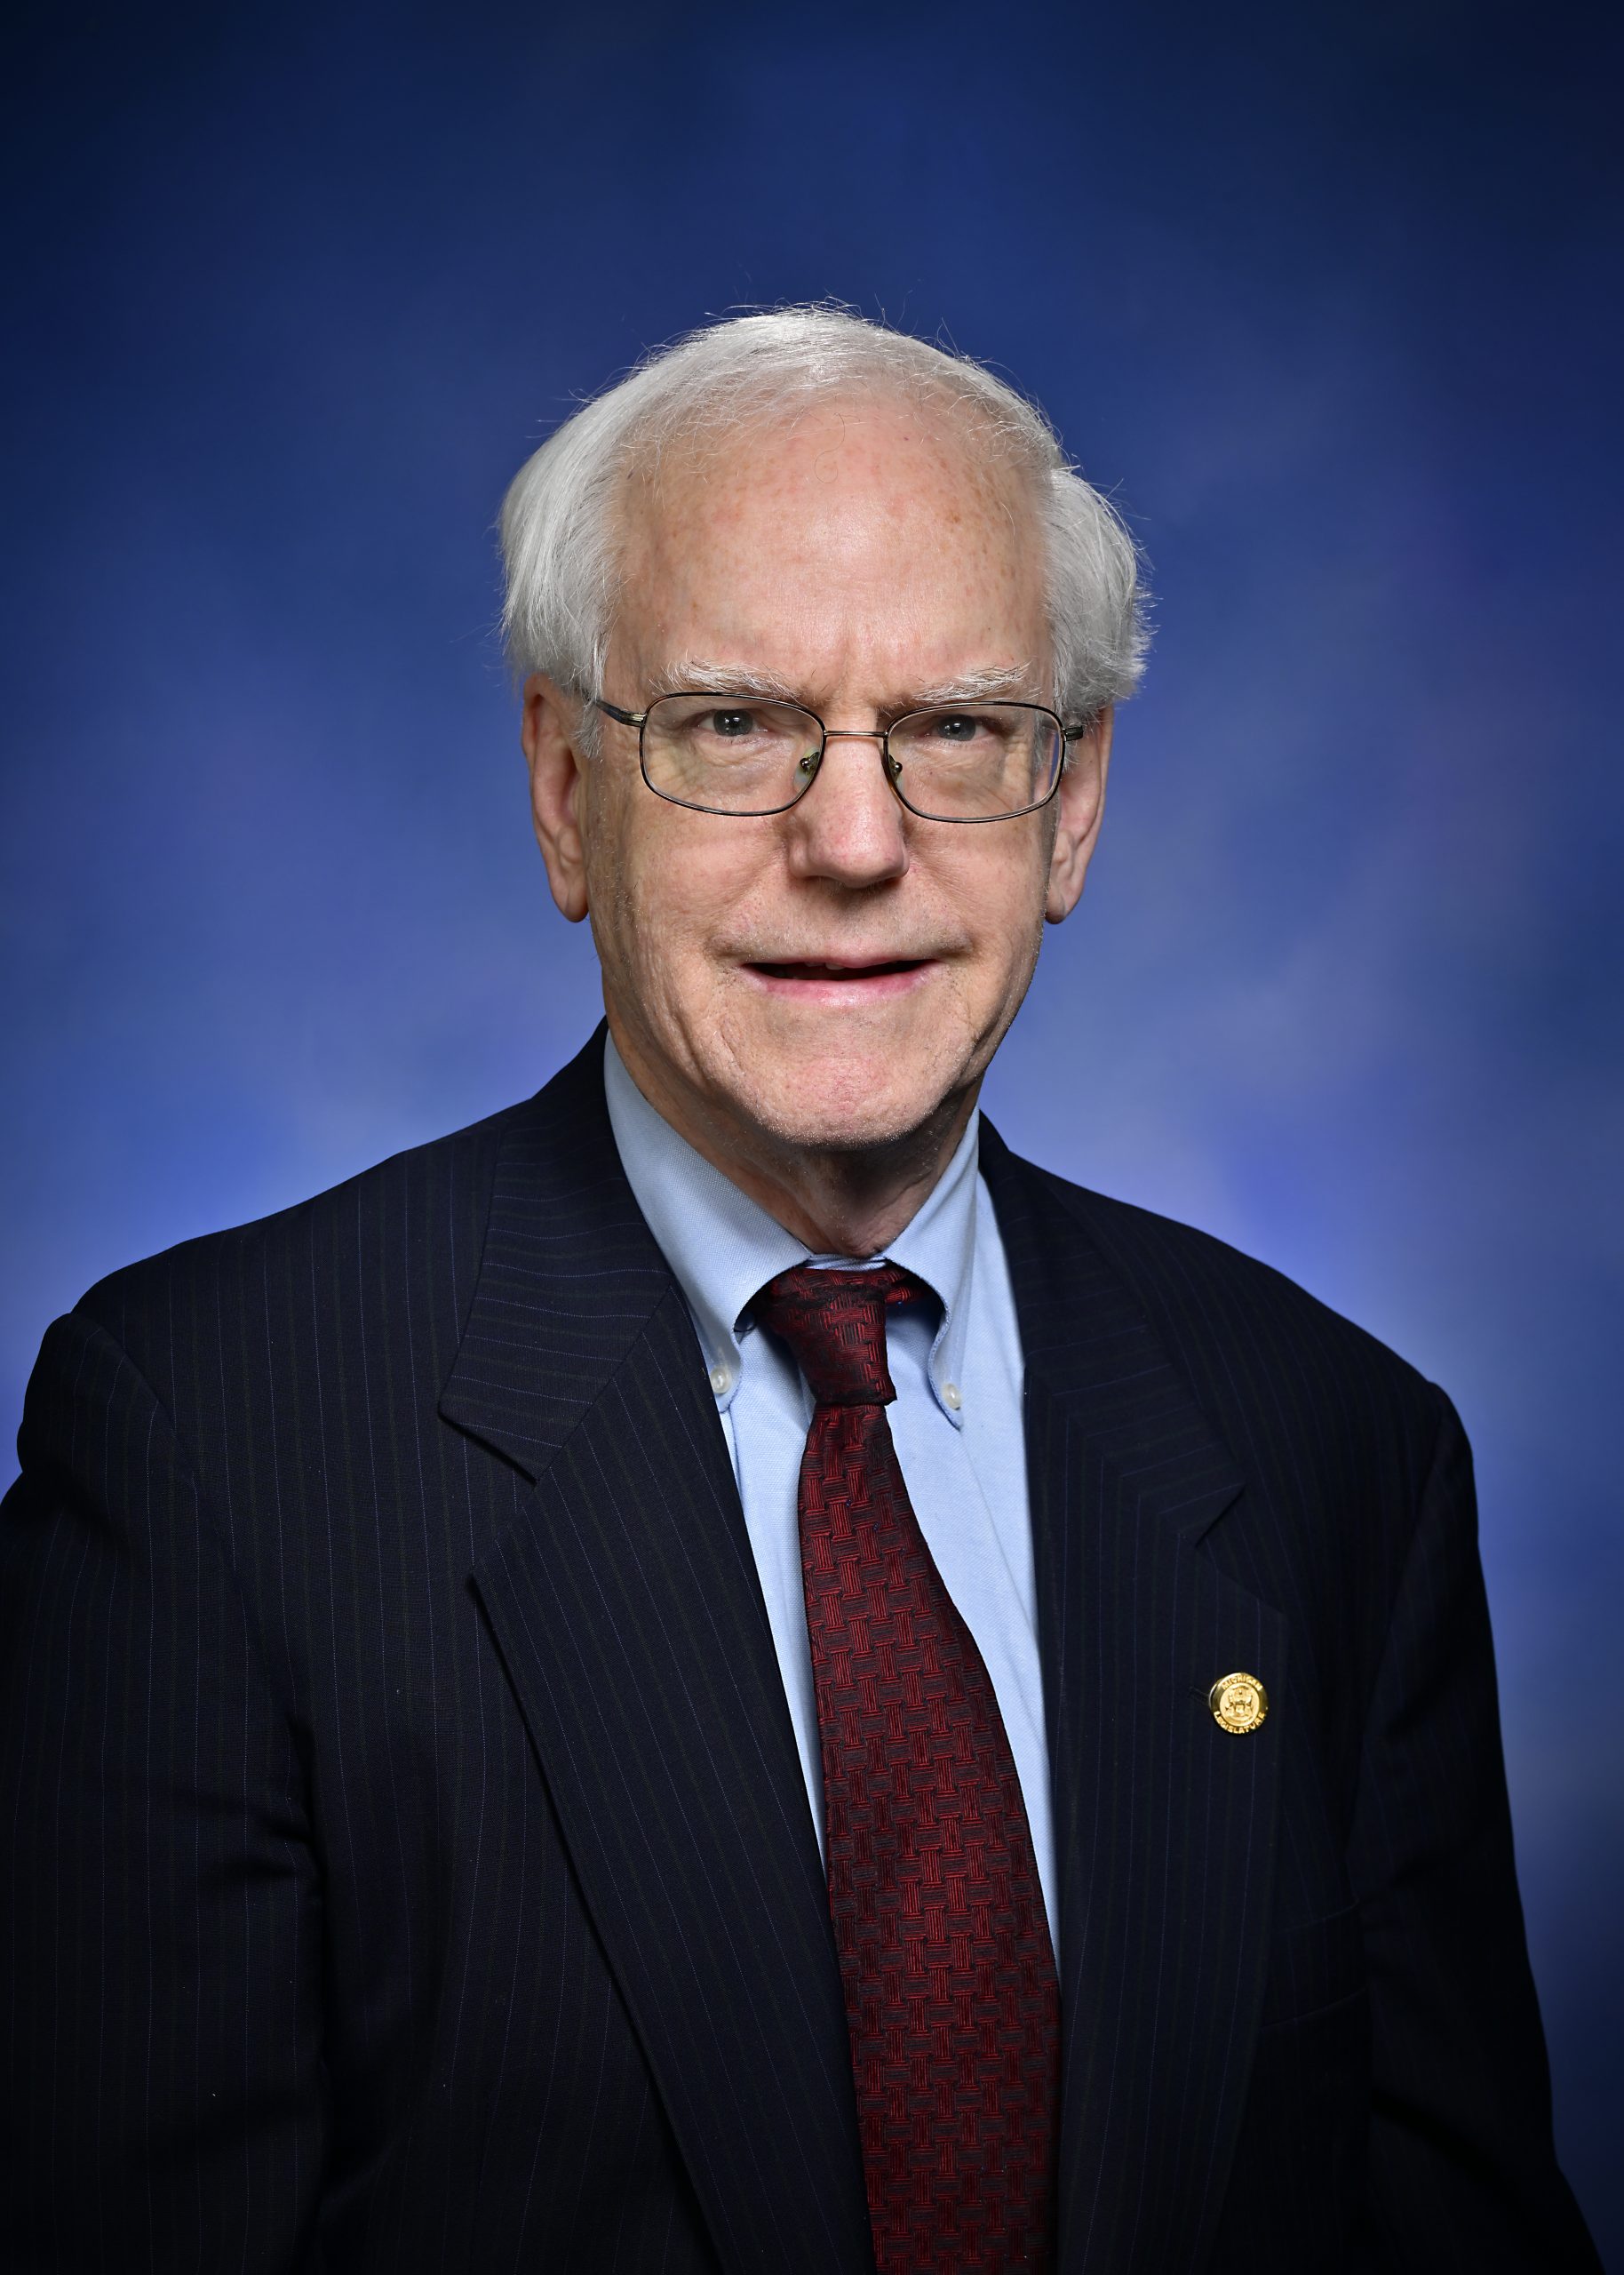
Tom Kuhn
RRepublican
Co
TC
Tyrone Carter
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 5552
Scope: MI
Hi! I can help you understand HB 5552. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline