

Property tax: payment and collection; effect of a postmark date when determining date property taxes are paid and other communications and notifications are provided; clarify. Amends sec. 44b of 1893 PA 206 (MCL 211.44b).
HB 4799 clarifies when mailed property tax payments and official communications are considered received by local governments. It specifies that the postmark date on a mailed payment or notice counts as the submission date, rather than the date it is physically received. This change directly affects property owners who mail payments and local tax collection offices that process them. The bill aims to prevent penalties for timely mailed payments that arrive slightly late due to postal delays.
Bill status
passed
3 of 5 stages cleared
Introduction
Aug 2025
Committee Review
Oct 2025
House Passage
Jan 2026
Senate Passage
Governor
Introduced Aug 26, 2025
Last action Jan 21, 2026
Maddy AI version diff · 3 comparisons
What changed between versions
Substitute (H-4)
→
Substitute (H-3) - 2
·
3 edits
MINOR
The bill was revised to expand how the state determines when a tax payment is officially received. The changes clarify that payments made via electronic communication or notifications are now treated as received on the date of submission, in addition to traditional mail and postmark dates. This update also broadens the types of taxes covered to include nondelinquent amounts and adds specific language to exclude certain modern payment methods like peer-to-peer apps.
Scope change
The bill's scope was expanded to explicitly include 'nondelinquent' property taxes and to recognize electronic communications as valid proof of payment timing.
REQUIREMENT
The definition of 'receipt' was updated to include the date of electronic submission for authorized electronic payments or communications, ensuring these are treated the same as mailed payments.
The definition of authorized electronic payment was refined to explicitly exclude external banking applications, peer-to-peer platforms, and unverified payment intermediaries.
SCOPE
The section applying to tax payments was broadened to cover 'nondelinquent' property taxes and assessments, whereas the previous version had a more specific limitation regarding delinquency status.
Floor votes
How they voted
This bill passed the House by voice vote (no roll call recorded).
Full legislative history
Actions timeline
Total actions
10
Key actions
2
Committee
3
Jan 21, 2026
Lower · Passed
substitute (H-4) adopted
lower
Oct 21, 2025
Committee
referred to second reading
lower
Oct 21, 2025
Lower · Passed
reported with recommendation with substitute (H-3)
lower
Aug 26, 2025
Committee
referred to Committee on Finance
lower
Aug 26, 2025
Introduced
introduced by Representative Rep. Sarah Lightner
lower
1 primary · 3 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
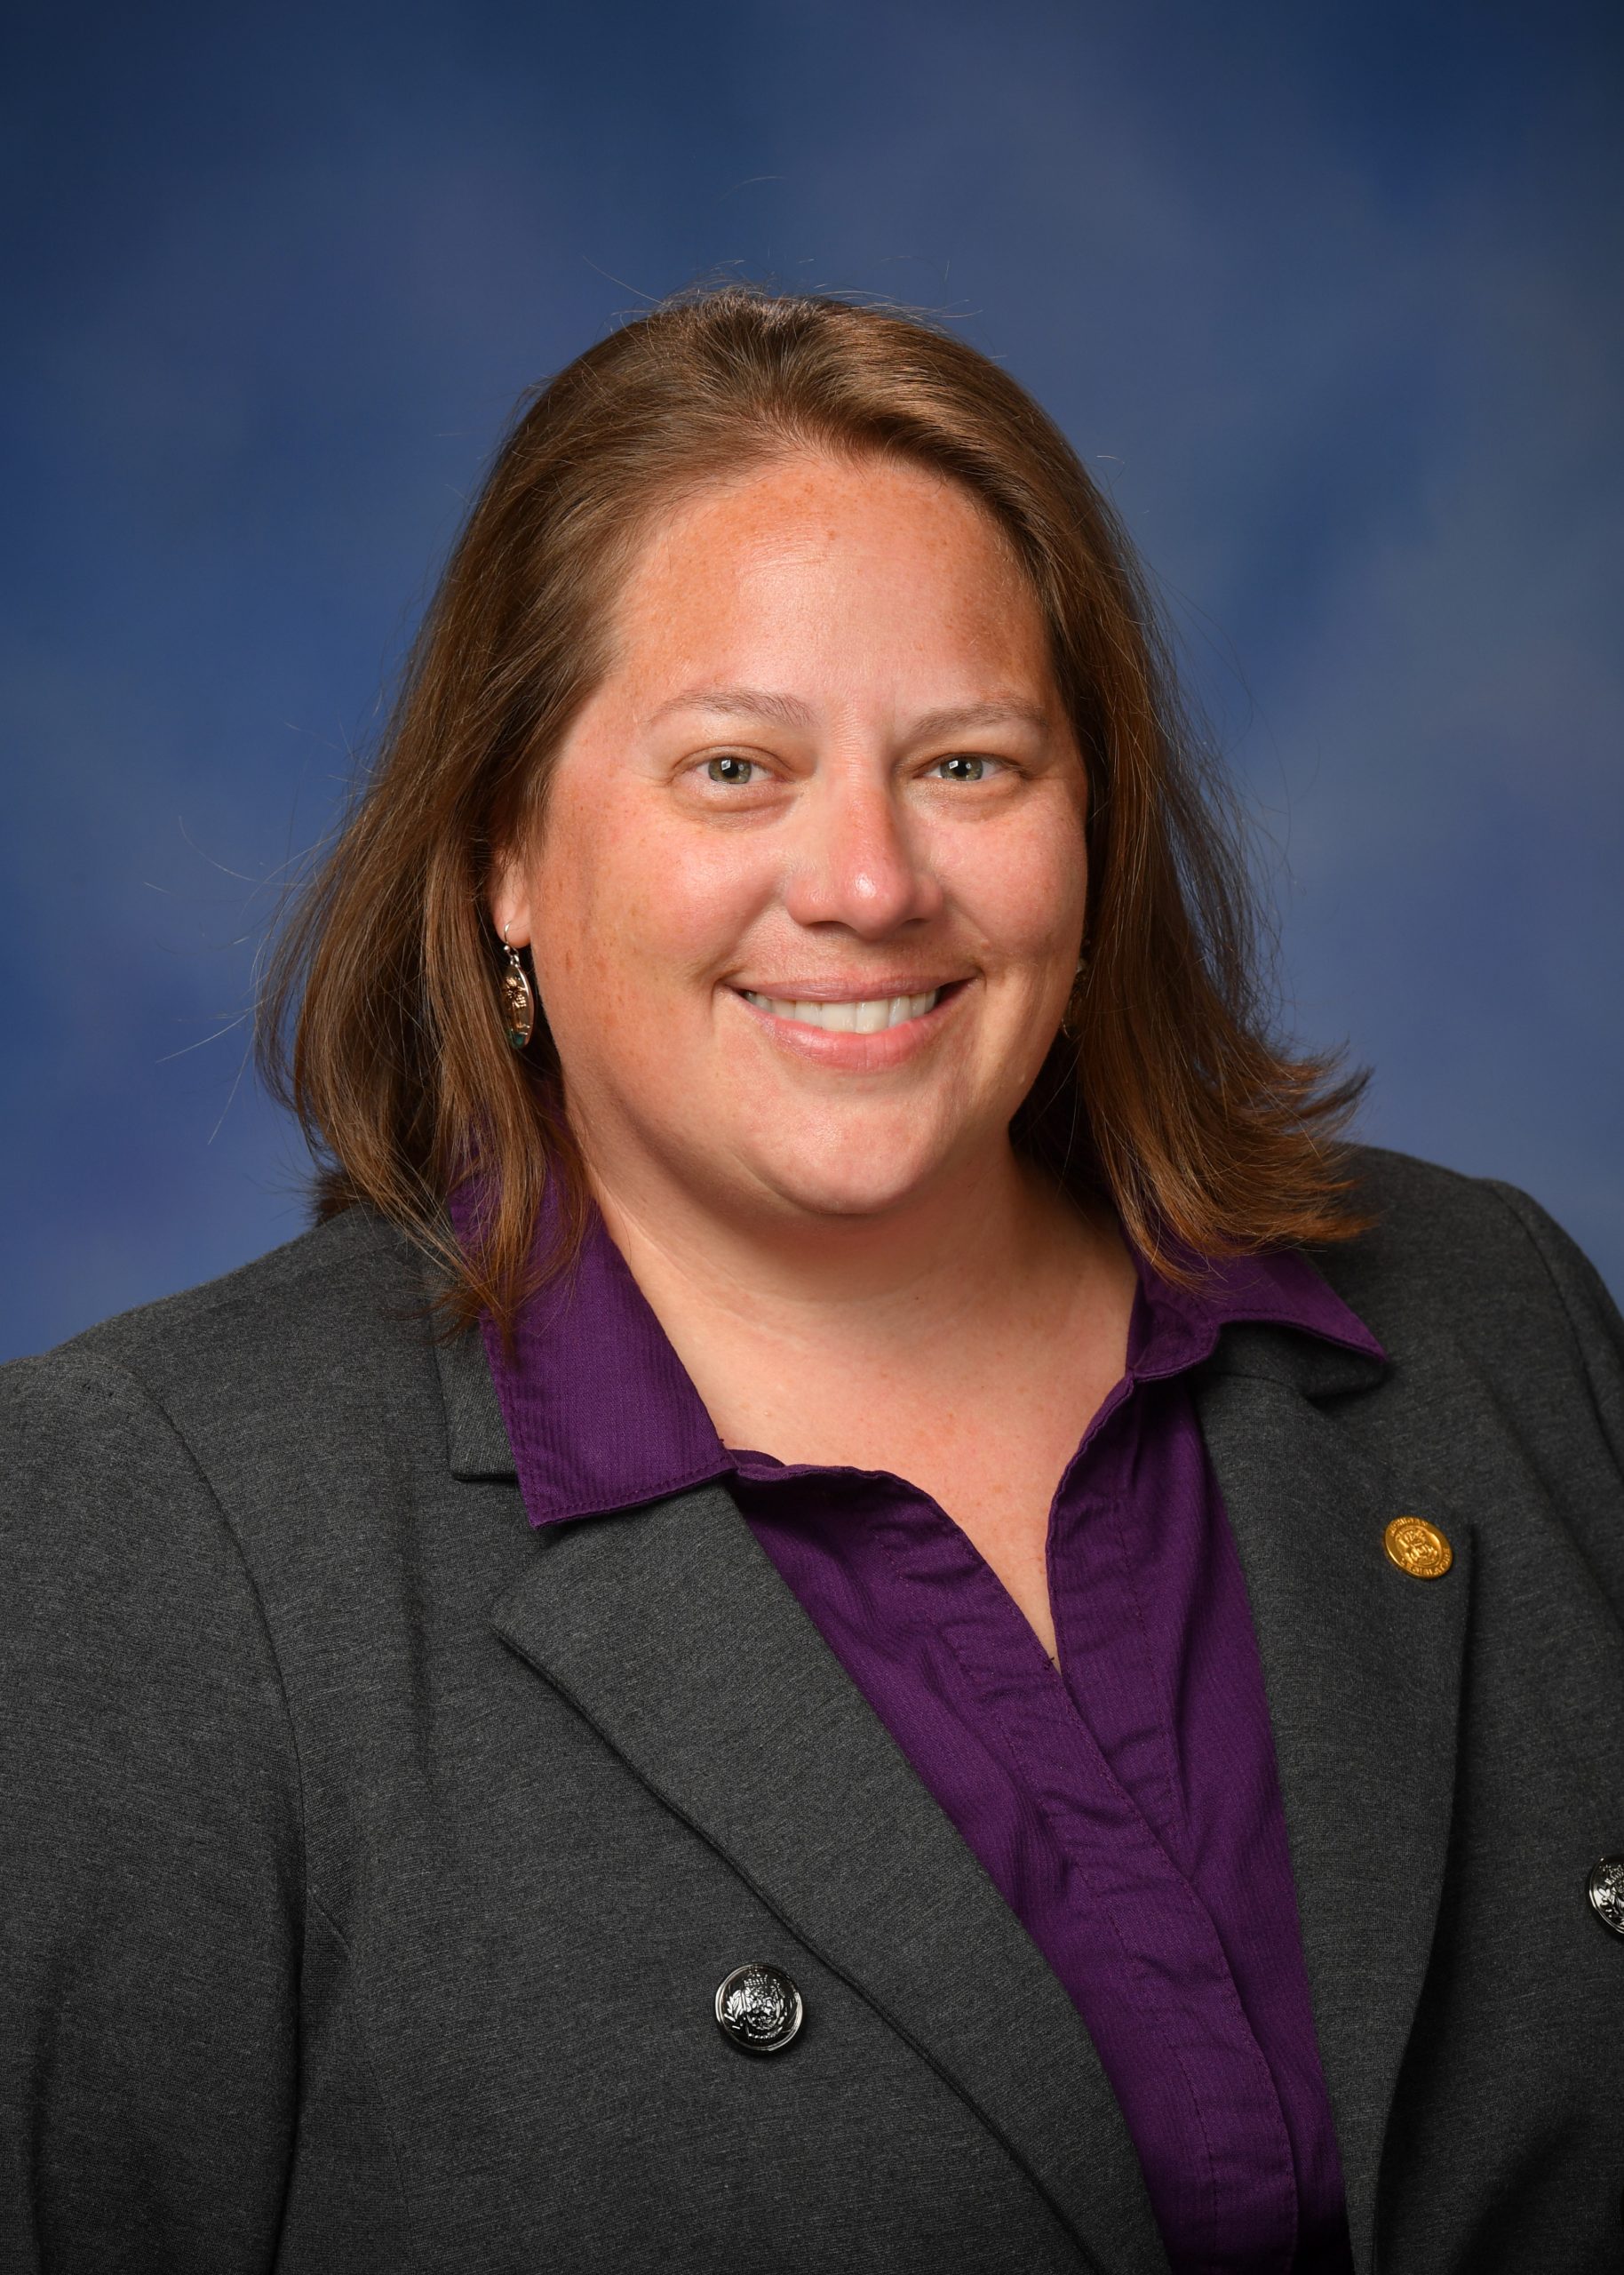
Sarah Lightner
RRepublican
Co
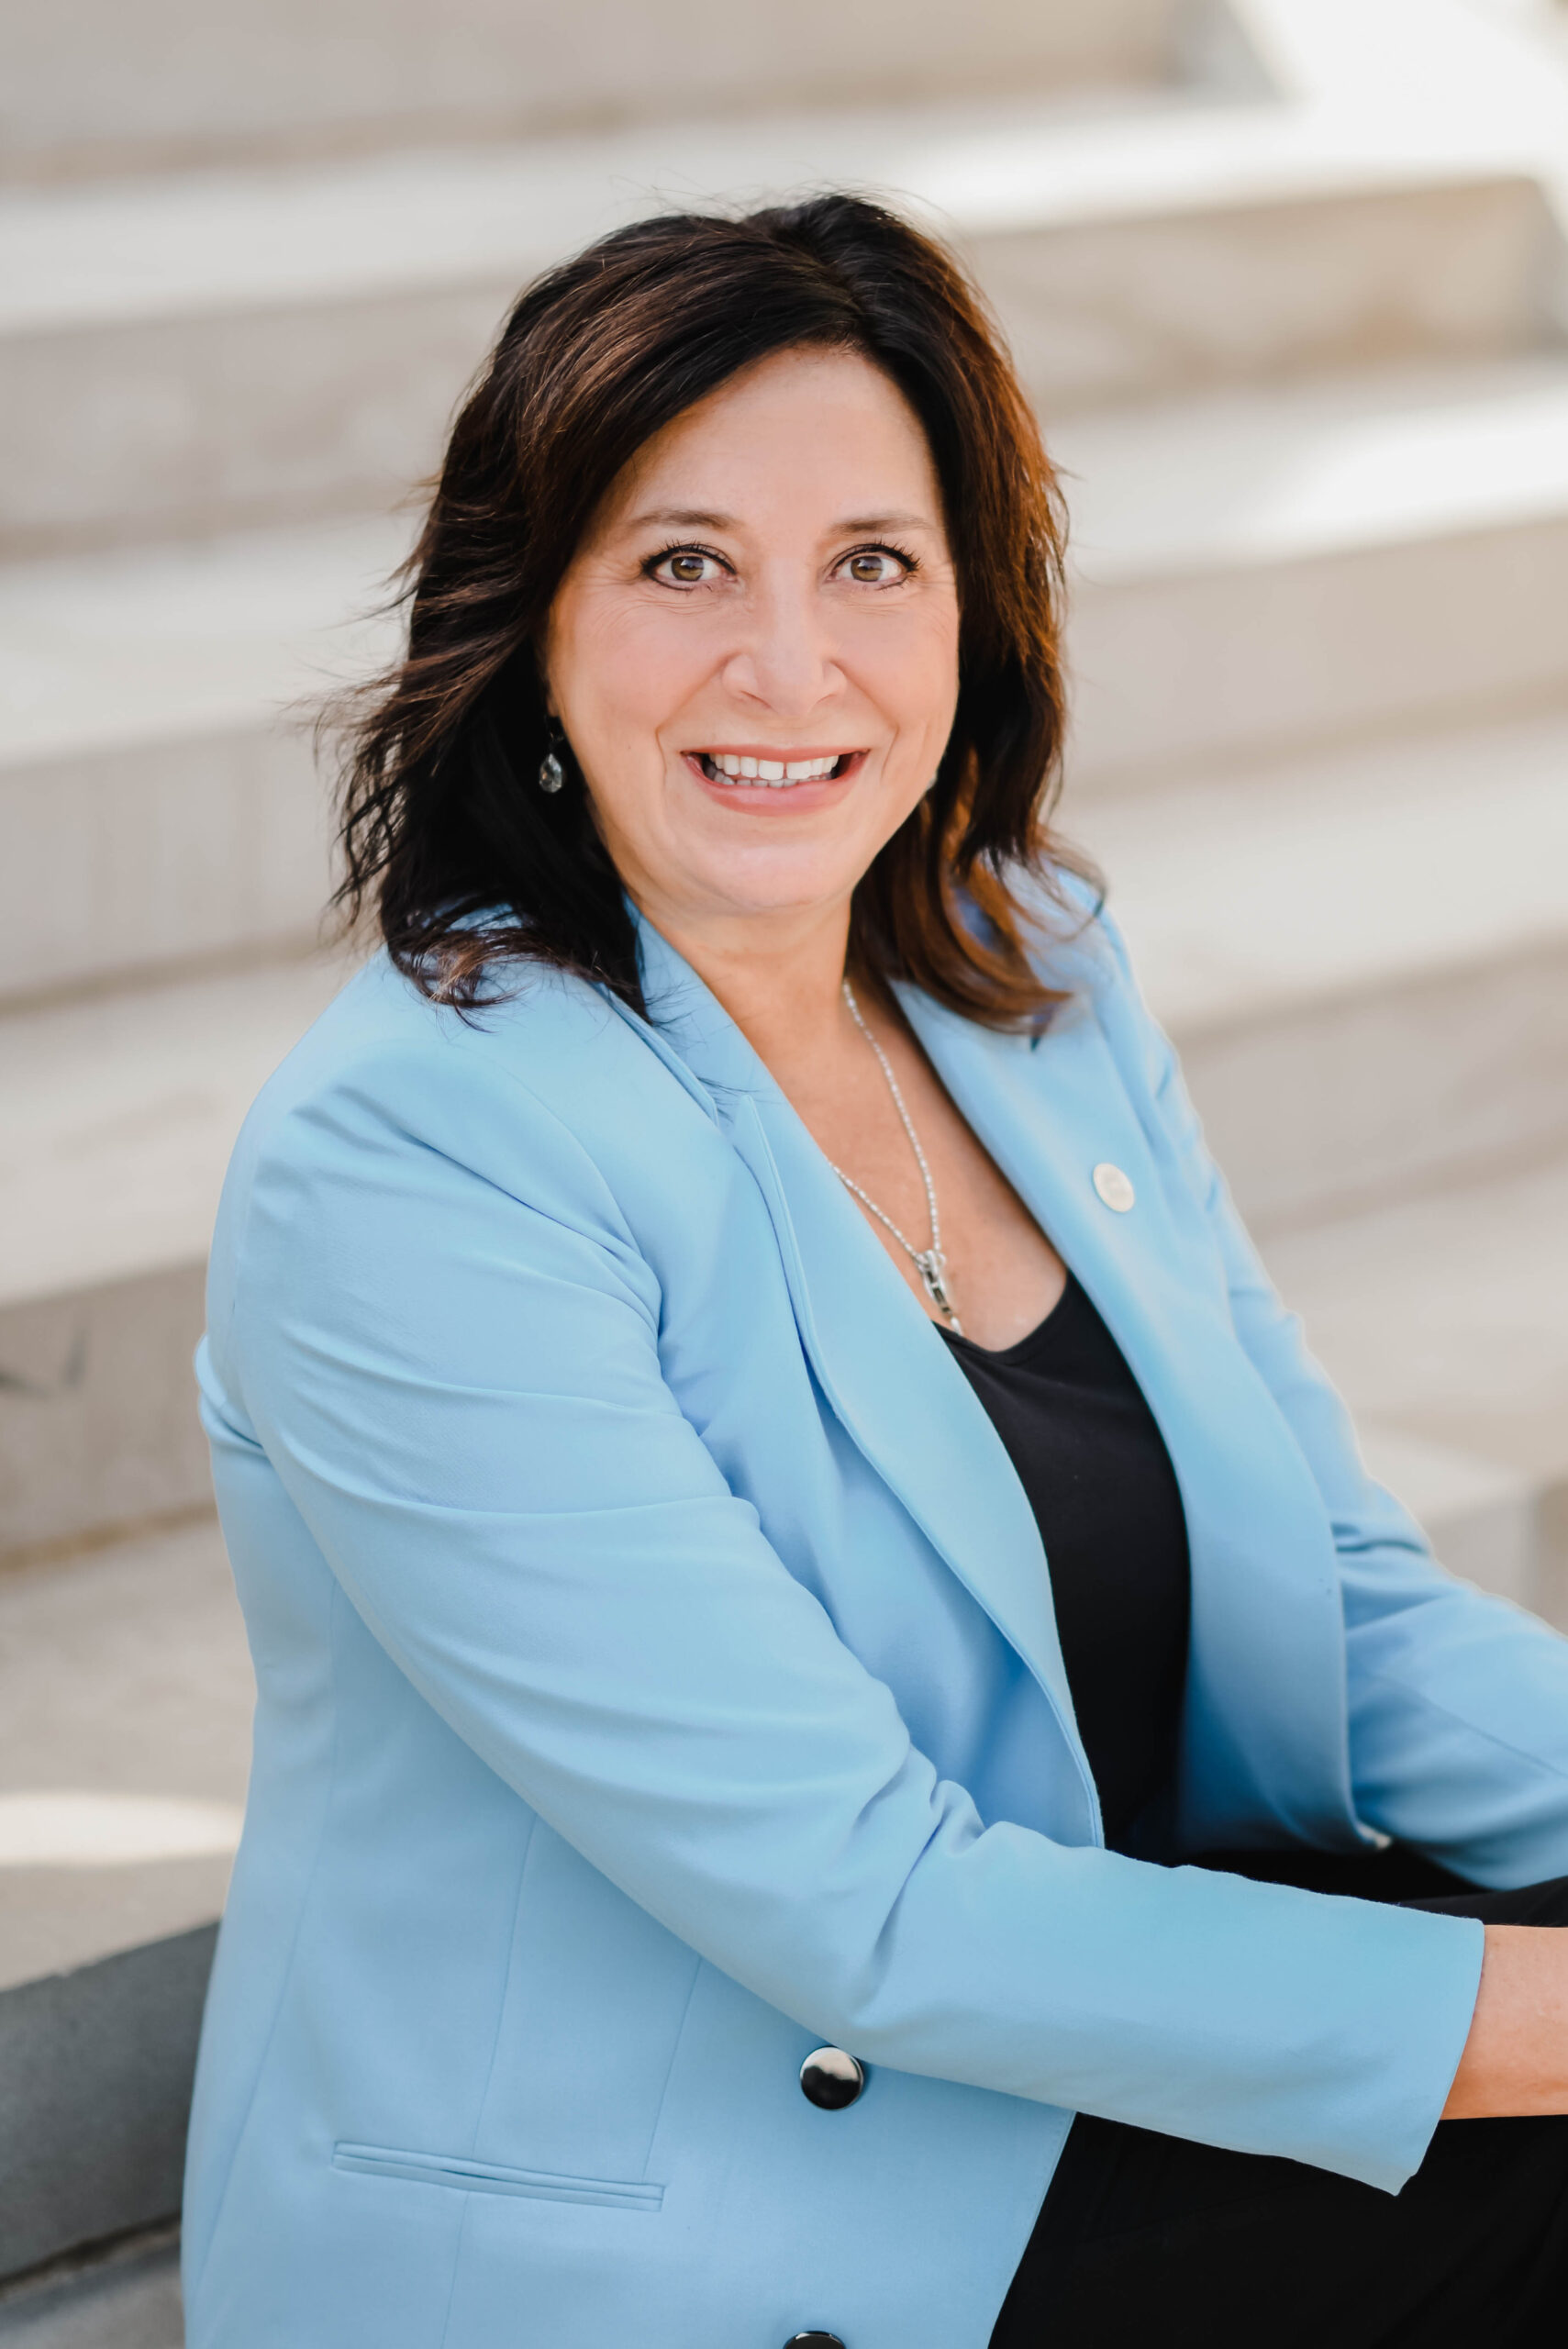
Angela Witwer
DDemocratic
Co
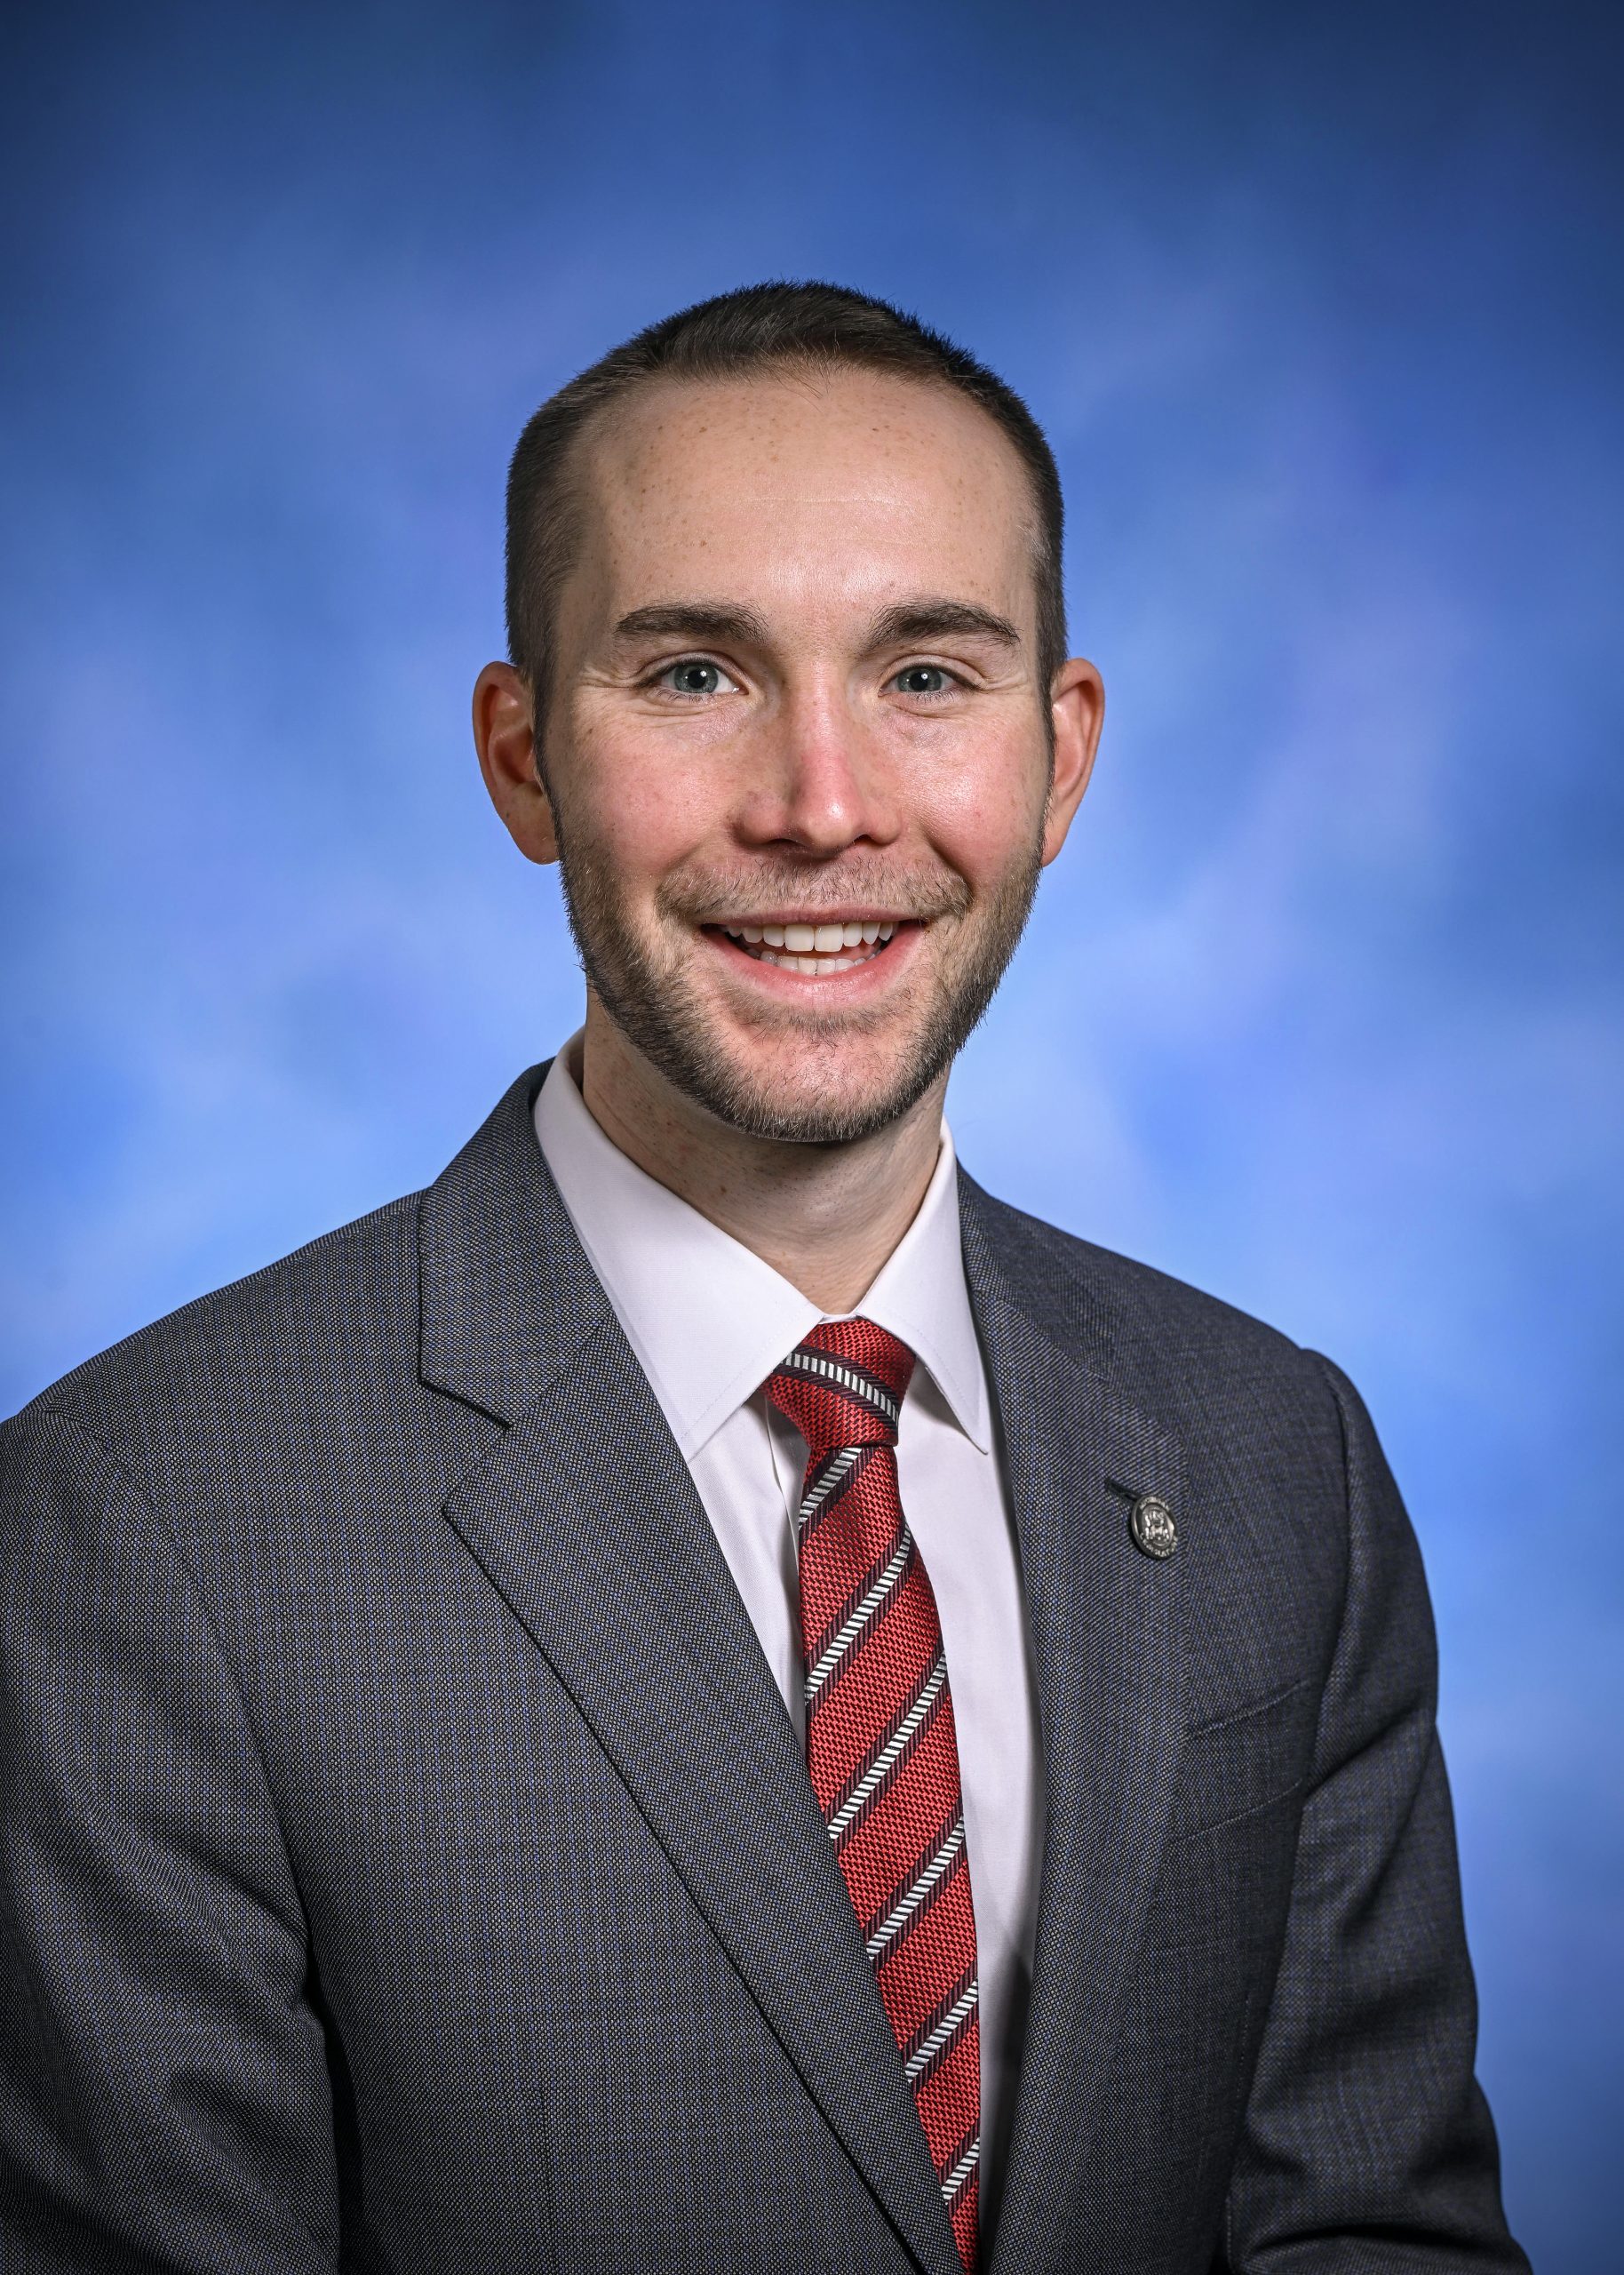
Bill Schuette
RRepublican
Co
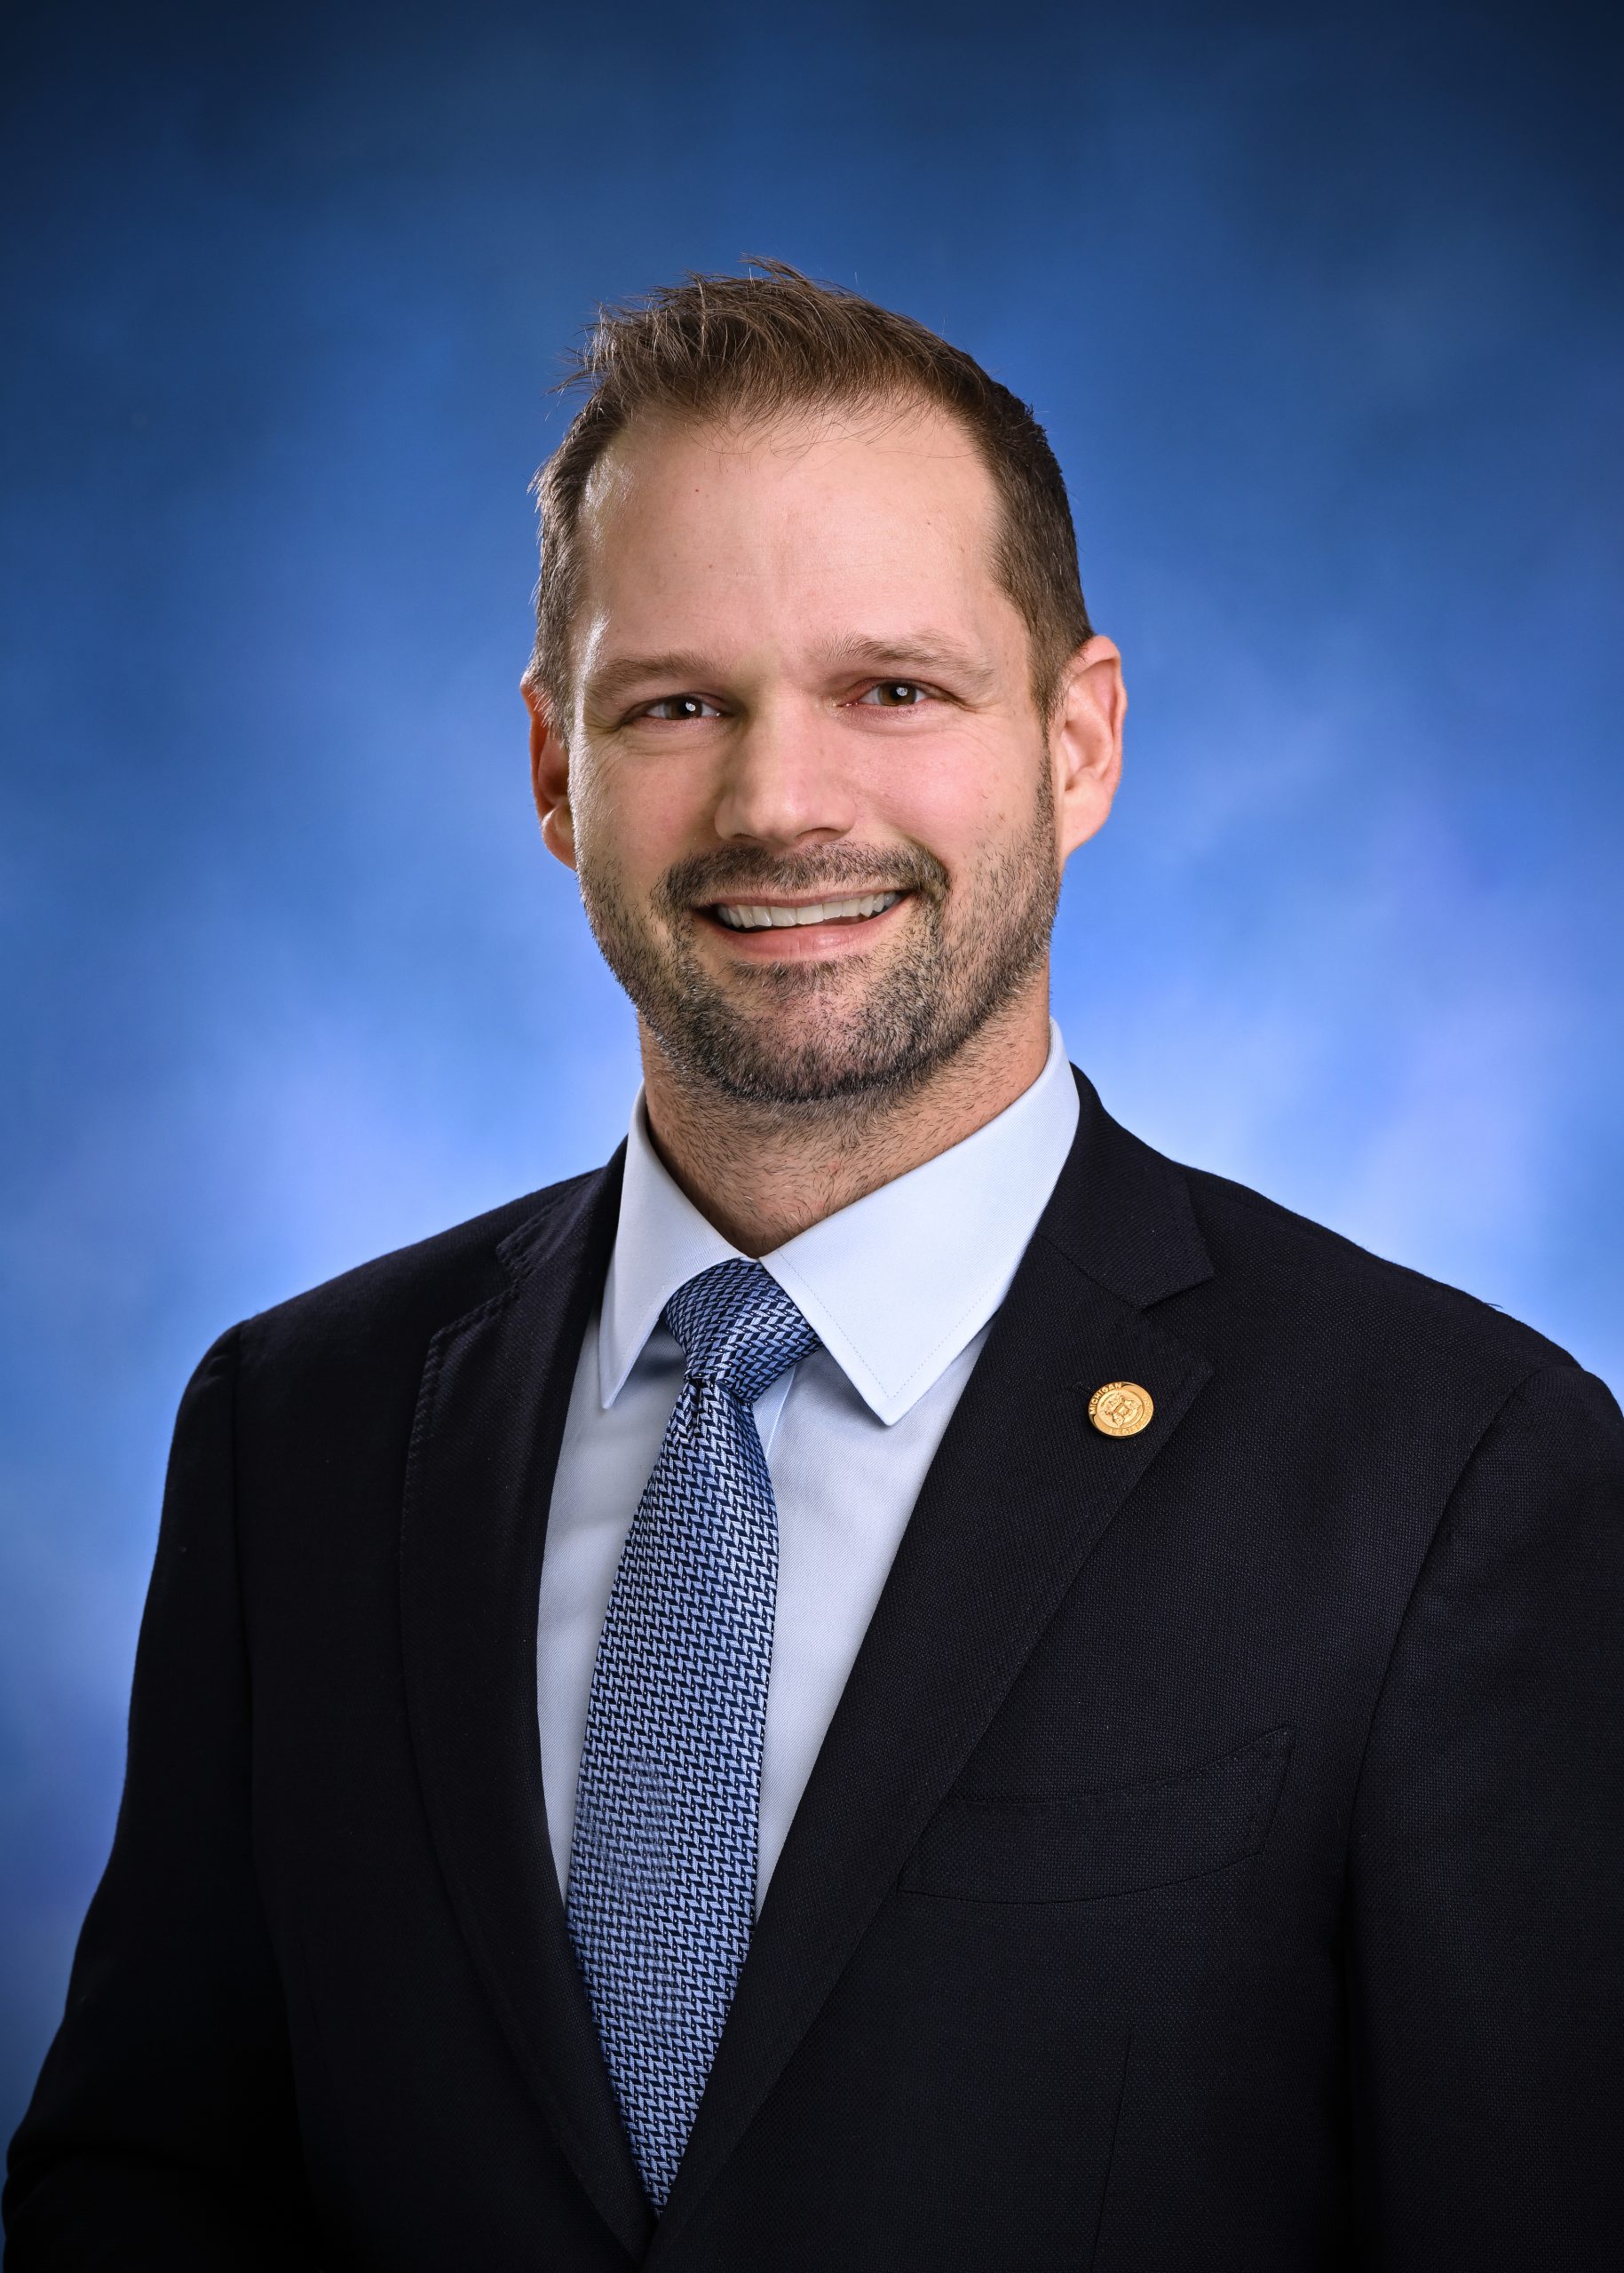
Bryan Posthumus
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 4799
Scope: MI
Hi! I can help you understand HB 4799. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline