

STATE EMPLOYEE RET: Provides relative to payments toward the unfunded accrued liability of the Louisiana State Employees' Retirement System and the amortization of certain actuarial gains. (gov sig) (EN SEE ACTUARIAL NOTE FC)
SB 21 amends Louisiana's state employees' retirement system funding rules, directly affecting state employees and the retirement system's financial management. It establishes new rules for calculating employer contributions and reamortizing the system's unfunded liability (retirement fund shortfall), requiring reamortization when the system reaches 80% funding or every five years starting in 2019-2020. The bill modifies how excess investment returns are applied to reduce the debt and clarifies that payments must follow specific amortization schedules. These changes aim to systematically address the retirement system's financial obligations without altering benefit levels.
Bill status
signed
all 5 stages cleared
Introduction
Jan 2026
Committee Review
May 2026
Senate Passage
Mar 2026
House Passage
May 2026
Signed into Law
May 2026
Introduced Jan 23, 2026
Signed May 15, 2026
Maddy AI version diff · 3 comparisons
What changed between versions
SB21 Original
→
SB21 Act
·
4 edits
MODERATE
This bill converts the Louisiana State Employees' Retirement System from a complex, multi-tiered amortization model to a single, simplified structure. It eliminates specific rules for calculating 'secondary' and 'residual' priority amounts, which previously allowed for layered funding calculations based on asset growth. The change aims to streamline how the system pays down its unfunded liability by removing these intricate adjustments.
Scope change
The bill narrows the scope of the retirement system's funding calculations by repealing specific subsections that governed the treatment of amortization bases after they were liquidated.
REQUIREMENT
Deleted the definition and calculation rules for 'secondary priority amount,' which previously allowed a portion of prior funding to be adjusted based on asset growth.
Repealed provisions that mandated re-amortization of remaining liabilities every fifth fiscal year, replacing them with a single, permanent amortization schedule.
DEFINITION
Removed the legal framework for 'residual priority amount,' simplifying how the system handles remaining debt after initial funding targets are met.
TIMELINE
Established a new effective date for the Act, specifying it becomes law upon the governor's signature or after the standard legislative timeline if not signed.
Floor votes · Senate Mar 24, 2026 · House May 12, 2026
How they voted
38–0
Passed · 2 other
Total votes 40
Mar 24, 2026
D
Democratic12
100% Yea
R
Republican28
92% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
18
Key actions
4
Committee
4
Amendments
1
May 12, 2026
Lower · Passed
Read third time by title, roll called on final passage, yeas 90, nays 3. Finally passed, ordered to the Senate.
lower
May 6, 2026
Introduced
Reported without Legislative Bureau amendments.
lower
May 5, 2026
Lower · Passed
Reported favorably (16-0). Referred to the Legislative Bureau.
lower
Mar 25, 2026
Committee
Read by title, under the rules, referred to the Committee on Retirement.
lower
Mar 24, 2026
Upper · Passed
Read by title, passed by a vote of 37 yeas and 0 nays, and sent to the House. Motion to reconsider tabled.
upper
Mar 16, 2026
Upper · Passed
Reported favorably.
upper
Mar 9, 2026
Committee
Introduced in the Senate; read by title. Rules suspended. Read second time and referred to the Committee on Retirement.
upper
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
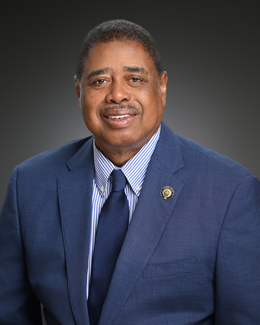
Ed Price
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about SB 21
Scope: LA
Hi! I can help you understand SB 21. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline