

FINANCIAL INSTITUTIONS: Provides relative to deferred presentment transactions and small loans
HB 582 updates the maximum loan amount for small loans (defined as $350 or less for 60 days or less) by requiring annual adjustments based on inflation. It mandates that the state office of financial institutions calculate a new yearly maximum principal balance using the previous year's Consumer Price Index data, rounding up to the nearest $10. This applies specifically to licensed financial institutions offering deferred presentment transactions or small loans, directly affecting borrowers who use these services and the institutions that provide them. The bill does not change fee limits but ensures the loan cap automatically adjusts for inflation each year.
Bill status
signed
all 5 stages cleared
Introduction
Apr 2025
Committee Review
Jun 2025
House Passage
Jun 2025
Senate Passage
Jun 2025
Signed into Law
Jul 2025
Introduced Apr 4, 2025
Signed Jul 1, 2025
Maddy AI version diff · 4 comparisons
What changed between versions
HB582 Original
→
HB582 Act 510
·
4 edits
MODERATE
This bill updates Louisiana laws governing deferred presentment transactions and small loans by redefining key terms, adjusting fee limits, and introducing new reporting requirements. It establishes a new maximum principal balance that will be adjusted annually based on inflation and prohibits licensees from reporting negative customer information to credit bureaus.
Scope change
The bill expands the scope by adding a prohibition on reporting negative customer data to credit bureaus and introduces a new mechanism for adjusting loan limits based on economic indicators.
DEFINITION
Redefines 'deferred presentment transaction' to clarify the check-holding period and sets a new maximum principal balance of $3,570, which will be recalculated annually based on the Consumer Price Index.
Adds a specific definition for 'small loan' as a consumer loan of $350 or less with a term of 60 days or less.
REQUIREMENT
Requires the Office of Financial Institutions to publish the updated maximum principal balance on its website by September 1st each year.
ENFORCEMENT
Prohibits licensees from reporting any negative information about their customers to credit bureaus or credit reporting services.
Floor votes · Senate Jun 3, 2025 · House May 12, 2025
How they voted
33–2
Passed · 2 other
Total votes 37
Jun 3, 2025
D
Democratic11
90% Yea
R
Republican26
88% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
21
Key actions
5
Committee
5
Jun 4, 2025
Lower · Passed
Read by title, roll called, yeas 87, nays 0, Senate amendments concurred in.
lower
Jun 3, 2025
Upper · Passed
Rules suspended. The amended bill was read by title, passed by a vote of 34 yeas and 2 nays, and ordered returned to the House. Motion to reconsider tabled.
upper
Jun 1, 2025
Committee
Committee amendments read and adopted. Read by title and referred to the Legislative Bureau.
upper
May 29, 2025
Upper · Passed
Reported with amendments.
upper
May 12, 2025
Lower · Passed
Read third time by title, amended, roll called on final passage, yeas 65, nays 26. Finally passed, title adopted, ordered to the Senate.
lower
May 6, 2025
Lower · Passed
Reported with amendments (17-0).
lower
Apr 14, 2025
Committee
Read by title, under the rules, referred to the Committee on Commerce.
lower
Apr 4, 2025
Committee
Under the rules, provisionally referred to the Committee on Commerce.
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
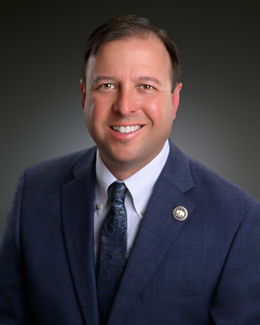
Jeremy LaCombe
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 582
Scope: LA
Hi! I can help you understand HB 582. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline