

Revenue and taxation; tax credits for certain contributions made by taxpayers to certain mortgage loan originators; provide
Summary
A BILL to be entitled an Act to amend Article 2 of Chapter 7 of Title 48 of the Official Code of Georgia Annotated, relating to imposition, rate, computation, exemption, and credits, so as to provide for tax credits for certain contributions made by taxpayers to certain mortgage loan originators; to provide for definitions; to provide for an aggregate annual limit; to provide for terms and conditions; to provide for applications and certifications; to provide for the revocation of qualified status; to provide for certain penalties; to provide for the promulgation of rules and regulations; to provide for related matters; to provide for an effective date and applicability; to repeal conflicting laws; and for other purposes.
Bill status
died
1 of 4 stages cleared
Introduction
Feb 2025
Committee Review
Floor Vote
Governor
Introduced Feb 10, 2025
Last action Apr 4, 2025
Maddy AI version diff · 1 comparison
What changed between versions
LC 62 0083/a
→
LC 50 1195S/hs
·
5 edits
MODERATE
This bill was amended to reduce the annual tax credit cap from $20 million to $10 million, adjust contribution limits, and restructure the application timeline for tax credit preapprovals. The changes aim to better manage available tax credits and provide clearer guidance on when contributions can be processed during the year.
Scope change
The bill's scope remains focused on mortgage loan originator tax credits, but the financial thresholds and administrative procedures have been modified to limit the total credit pool and adjust the timing of credit availability.
FISCAL
Reduced the maximum annual tax credit amount from $20 million to $10 million per calendar year.
Lowered the annual contribution limit per qualified organization from $2 million to $1 million.
TIMELINE
Added a new provision allowing tax credit preapprovals during the period from July 1 to December 31 of each year, in addition to the existing process.
REQUIREMENT
Changed the percentage of income tax liability used to calculate qualified contributions from 75% to 30% for corporations or entities not covered by other categories.
Removed the requirement that taxpayer notices must not require a signed release or notarized approval, simplifying the commissioner's notification process.
Floor votes
How they voted
No floor votes recorded yet.
Full legislative history
Actions timeline
Total actions
5
Key actions
1
Committee
2
Apr 4, 2025
Committee
House Withdrawn, Recommitted
lower
Mar 6, 2025
Lower · Passed
House Committee Favorably Reported By Substitute
lower
Feb 10, 2025
Introduced
House Hopper
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
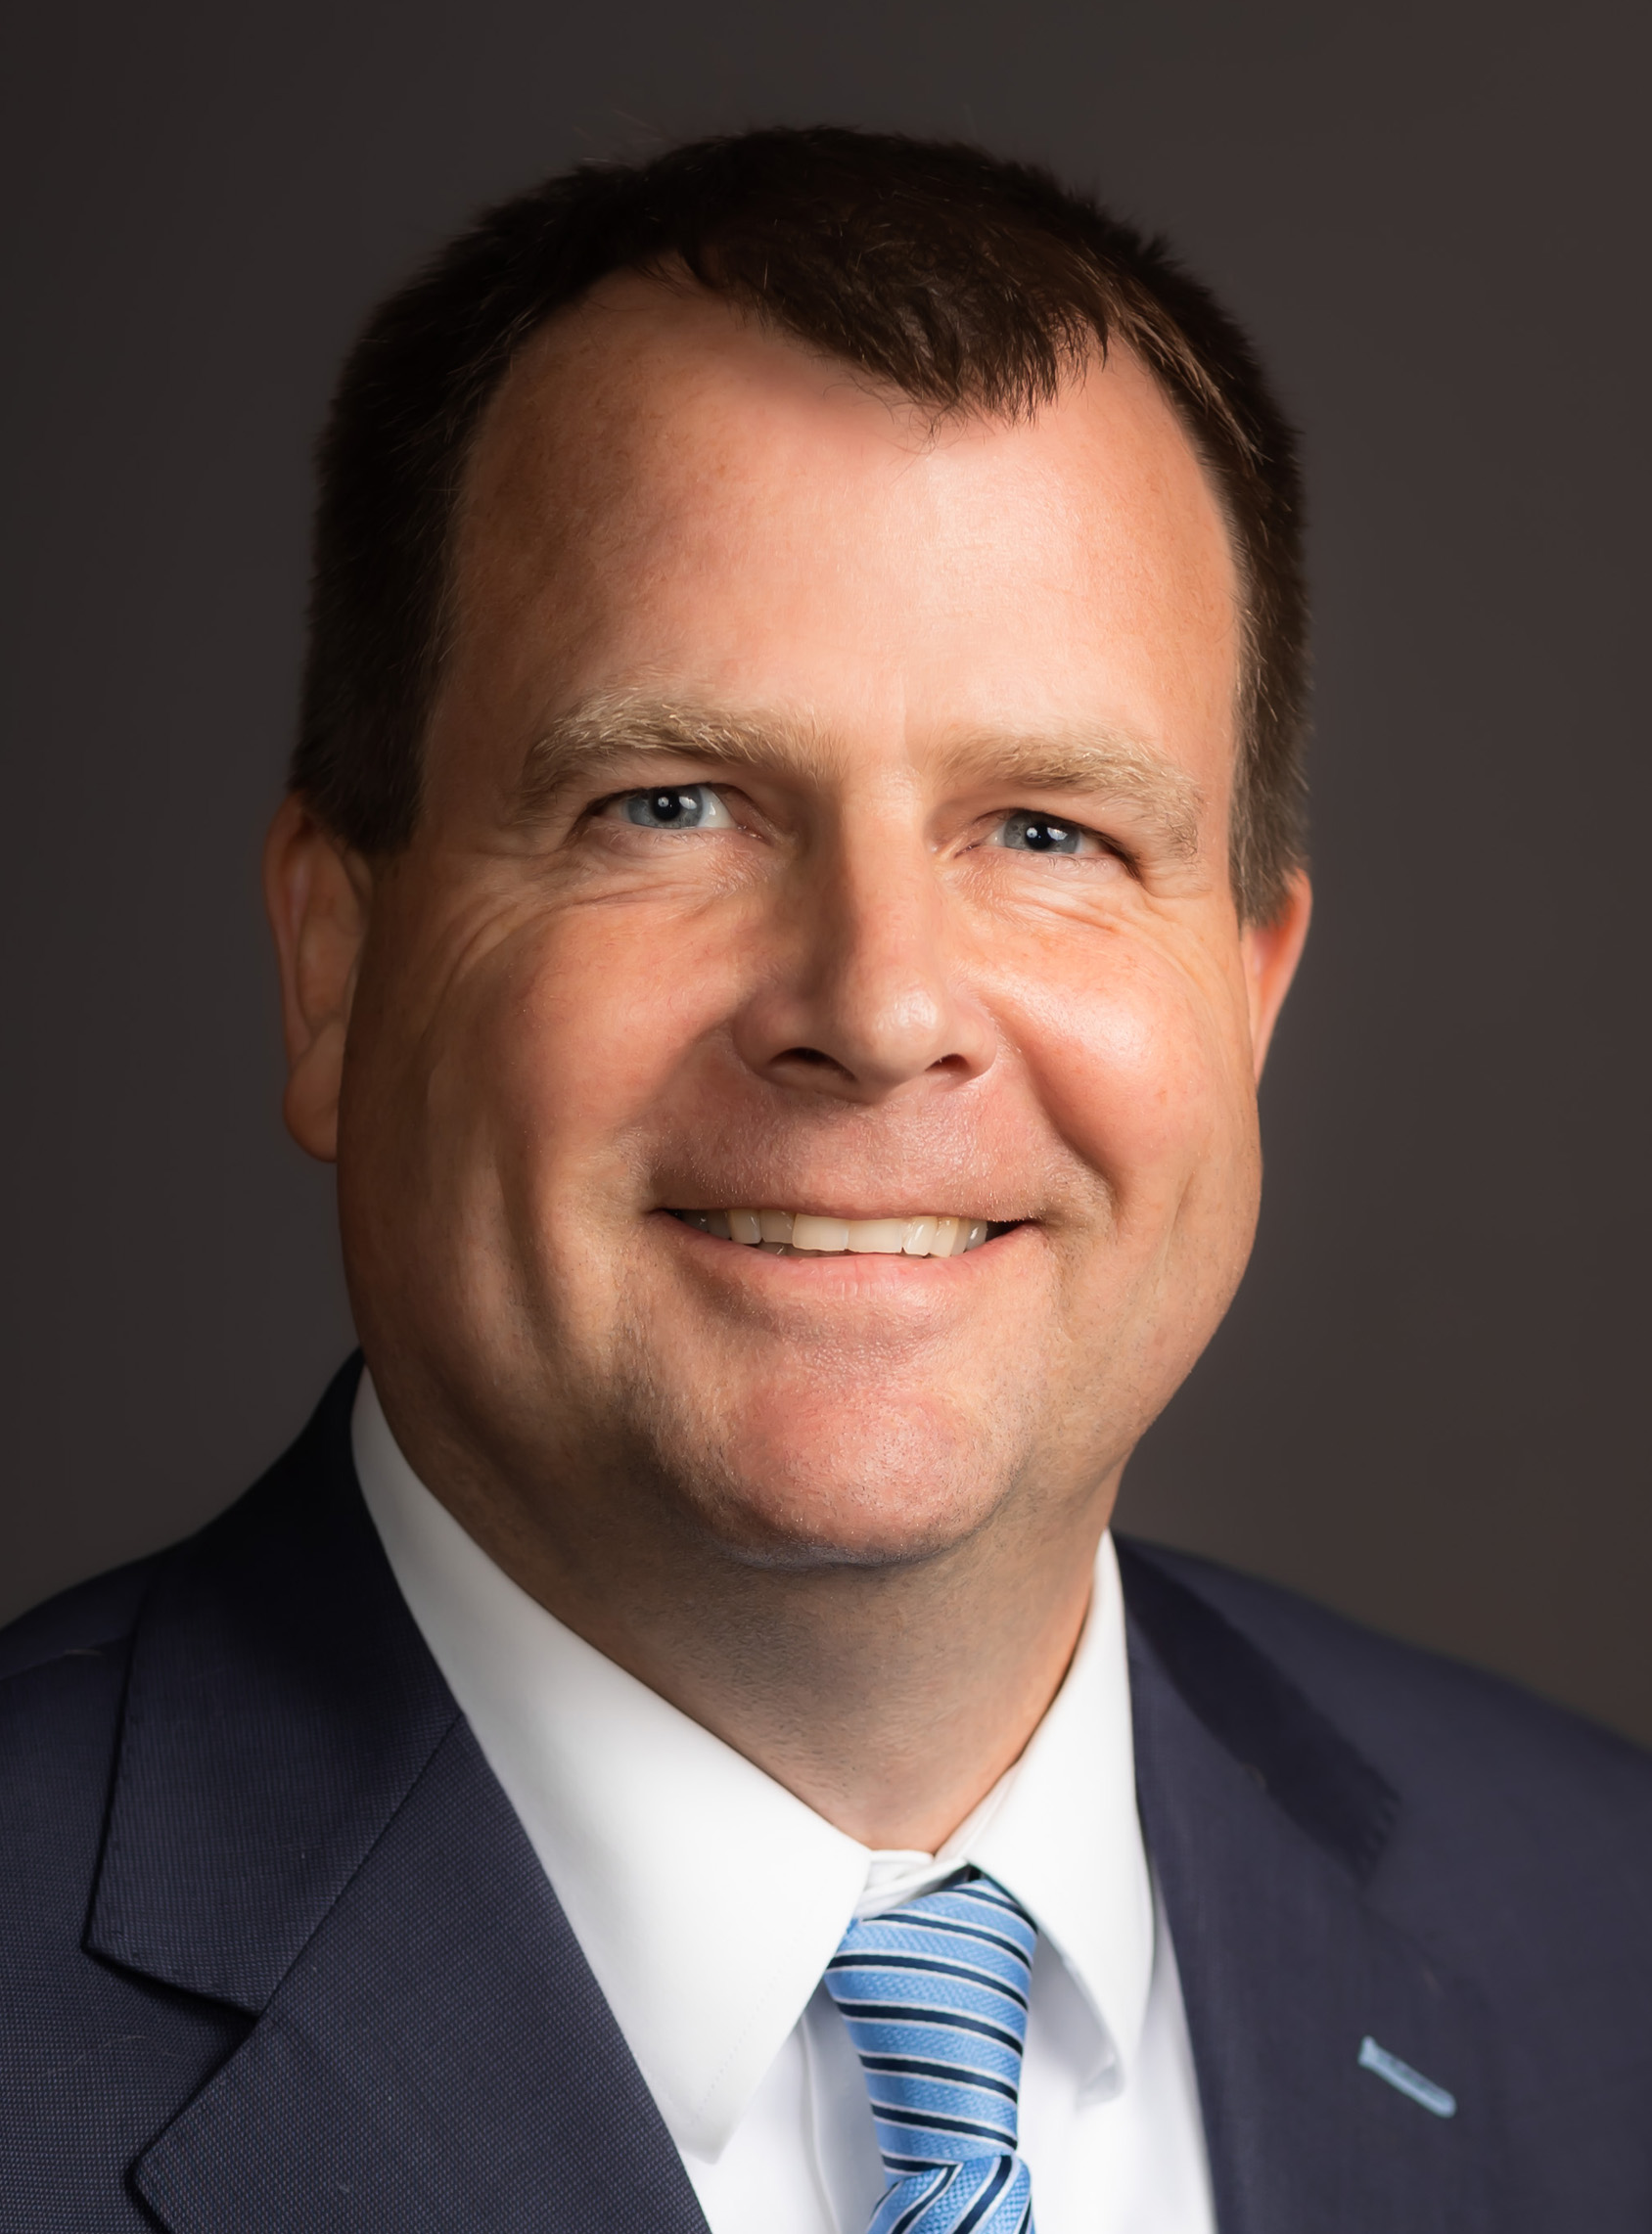
Lehman Franklin
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 357
Scope: GA
Hi! I can help you understand HB 357. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline