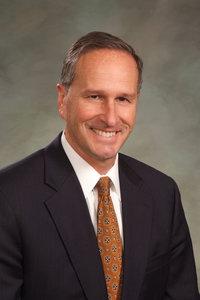
Photo of Timothy Leonard
R Colorado House · District 25

Rep. Timothy Leonard

Compare
Total votes
1,163
all sessions
Attendance
96%
33 missed
Near the chamber average
With party
87%
of cast votes
Lower than 83% of chamber peers
Bipartisan score
8%
crosses aisle rarely
Higher than 79% of chamber peers
Sponsored
16
bills & resolutions
Lower than 83% of chamber peers
Committees
0
assignments
16 bills and resolutions

Sponsored bills

Total
16
Primary
16
Co-sponsor
0
This page
16
matching current filters
Primary SB 18-242
Signed into law · Colorado Senate · Lead sponsor
Public Official Oath Of Office

The bill requires a person swearing an oath of office for a public office or position to do so by swearing by the everliving God. The bill also requires the person swearing the oath of office to do so with an uplifted hand. (Note: This summary applies to the reengrossed version of this bill as introduced in the second house.) , Read More

Signed into law Jun 1, 2018 0 co-sponsors
Primary SB 18-070
Passed · Colorado Senate · Lead sponsor
Church Property Tax Exemption

Under the state constitution, property that is used solely and exclusively for religious worship is exempt from property tax, unless otherwise provided by general law. By statute, the property must be owned and used solely and exclusively for religious purposes to qualify for the exemption. The bill eliminates the ownership requirement, which is not expressly included in the state constitution, so that a property leased to a church or other organization that uses it solely and exclusively for religious purposes is exempt from property tax. (Note: This summary applies to the reengrossed version of this bill as introduced in the second house.) Read More

Passed Apr 4, 2018 0 co-sponsors
Primary HB 18-1221
In committee · Colorado House · Lead sponsor
Income Tax Deduction For 529 Account Kindergarten Through Twelfth Grade Expenses

Current law allows contributions to a qualified state tuition program, also known as a 529 account, so long as the distributions are used for qualified higher education expenses (and some additional exceptions), but not for kindergarten through twelfth grade school expenses. The federal 'Tax Cuts and Jobs Act', which became law in December 2017, added distributions for kindergarten through twelfth grade expenses as qualified distributions thereby allowing, on the federal level, income tax-free distributions for elementary and secondary education expenses in addition to already authorized income tax-free distributions for higher education expenses. The bill makes similar changes to Colorado law to allow contributions to qualified state tuition programs for kindergarten through twelfth grade expenses thereby allowing a taxpayer to claim a deduction for such contributions and clarifying that such expenses are qualified distributions, ensuring that a taxpayer does not encounter tax recapture of any claimed deductions when such contributions are distributed for kindergarten through twelfth grade school expenses. (Note: This summary applies to this bill as introduced.) , Read More

In committee Mar 26, 2018 0 co-sponsors
Primary HB 18-1213
In committee · Colorado House · Lead sponsor
Declare Party Affiliation School District Director

Under current law, a candidate for school director shall not run as a candidate of any political party for that school directorship, but the statute is not clear whether the candidate is prohibited from identifying his or her political party affiliation. The bill permits a candidate for the office of school district director to declare the political party with which he or she is affiliated at any time up to 67 days before the election date. If a candidate chooses to declare his or her political party affiliation, the name or abbreviation of the political party with which the candidate is affiliated will be printed on the ballot after his or her name. In order to be able to exercise the option of declaring his or her affiliation, the candidate must have been affiliated with the political party, as shown in the statewide voter registration system, as of the first business day in the month of January during the year in which the election is held. (Note: This summary applies to this bill as introduced.) , Read More

In committee Mar 21, 2018 0 co-sponsors
Primary SB 18-103
Signed into law · Colorado Senate · Lead sponsor
Issuance Of Performance-based Incentives For Film

Legislative Audit Committee. The bill strengthens the requirements necessary to earn performance-based incentives for film production activities in the state by: Requiring a production company that originates production activities in Colorado to have engaged in production activities in the state for other projects in the 12 months prior to applying for the performance-based incentive for a new project, and if the production company creates a business entity for the sole purpose of conducting production activities in the state, requiring the manager of the business to be a resident of the state for 12 consecutive months as of the date of applying for a performance-based incentive as well as defining a manager as someone with decision-making authority to give permission or 'go-ahead' to move forward with a project; Requiring a production company to provide documentation to prove that the production company meets the statutory definition of 'originates'; Requiring the production company's certified public accountant to provide in his or her written report documentation of the production company's expenditures, including the qualified local expenditures, and documentation that proves that the production company hired the necessary workforce to qualify for the performance-based incentive; Requiring the office of economic development (office) to conduct a review of the certified public accountant's written report to ensure the statutory requirements are met; Requiring the office to develop a list of certified public accountants that meet the statutory requirements and make the list available to all production companies as well as post it on the office of economic development's website; and Specifying that the office shall not issue a performance-based incentive to a production company until the production company and the office have entered into a contract in accordance with the procurement code. The bill also specifies that if a performance-based incentive is erroneously or improperly issued to a production company for any reason, the office is required to engage the services of the attorney general to recover from the production company any amount of the performance-based incentive that was erroneously or improperly issued. The bill also requires the Colorado economic development commission to annually schedule an orientation with the staff of the office in order to receive an official overview of the statutory requirements for a production company to earn a performance-based incentive for film production in Colorado. (Note: This summary applies to the reengrossed version of this bill as introduced in the second house.) , Read More

Signed into law Mar 15, 2018 0 co-sponsors
Primary HB 18-1121
In committee · Colorado House · Lead sponsor
No Funding Trafficking Aborted Human Body Parts

Each higher education institution that receives funding from the state must file a verified report each December 1 with the joint budget committee stating whether or not the institution engaged, directly or indirectly, in the harvesting, trafficking, purchasing, or selling of aborted human body parts in the previous year. If a higher education institution files a report affirming that the institution engaged, directly or indirectly, in the harvesting, trafficking, purchasing, or selling of aborted human body parts, the general assembly shall not appropriate any state funding to that institution in the next fiscal year.(Note: This summary applies to this bill as introduced.) , Read More

In committee Feb 28, 2018 0 co-sponsors
Primary HB 18-1119
In committee · Colorado House · Lead sponsor
Highway Building & Maintenance Funding

Section 9 of the bill requires the transportation commission (commission) to submit a ballot question to the voters of the state at the November 2018 statewide election which, if approved: Will require the executive director of the department of transportation (CDOT) to issue transportation revenue anticipation notes (TRANs) in a maximum principal amount of $3.5 billion and with a maximum repayment cost of $5 billion; and Will, in conjunction with sections 3, 4, and 7, repeal current law, enacted by Senate Bill 17-267, that requires the state treasurer to execute lease-purchase agreements of up to $1.88 billion for the purpose of funding high-priority qualified federal aid transportation projects. The executive director must issue at least one-third of the TRANs within one year of the date of the official declaration of the vote on the ballot issue by the governor, issue at least two-thirds of the TRANs within 2 years of that date, and issue all of the TRANs within 3 years of that date. The additional TRANs must have a maximum repayment term of 20 years, and the certificate, trust indenture, or other instrument authorizing their issuance must provide that the state may pay them in full before the end of the specified payment term without penalty. TRANs must otherwise generally be issued subject to the same requirements as the TRANs issued in 1999; except that the commission must pledge to annually allocate from legally available money under its control any money needed for payment of TRANs until the TRANs are fully repaid. Section 10 requires TRANs net proceeds not otherwise pledged for TRANs payments to be credited to the state highway fund and expended by CDOT only for qualified federal aid highway projects as described in section 6. CDOT may expend no more than 10% of the net proceeds for the administration and engineering of the projects being funded with the net proceeds. On and after July 1, 2018, section 5 requires 7.5% of state sales and use tax net revenue to be credited to the state highway fund and used first to make TRANs payments. Section 6 requires state sales and use tax net revenue credited to the state highway fund that is not expended to make TRANs payments to be expended only for maintenance of qualified federal aid highways and requires TRANs net proceeds credited to the state highway fund to be expended only for qualified federal aid highway projects included in the strategic transportation project investment program of CDOT and designated for tier 1 funding as 10-year development program projects on CDOT's development program project list. If the voters of the state approve the issuance of TRANs, CDOT is required to ensure that construction of one-third of the projects commences within one year of the date of the official declaration of the vote on the ballot issue by the governor, to ensure that construction of two-thirds of the projects commences within 2 years of that date, and ensure that construction of all of the projects commences within 3 years of that date. Section 7 requires CDOT to include specified information about the state sales and use tax net revenue and TRANs net proceeds in its annual report to the senate transportation committee and the house transportation and energy committee. (Note: This summary applies to this bill as introduced.) , Read More

In committee Feb 21, 2018 0 co-sponsors
Primary HB 18-1036
In committee · Colorado House · Lead sponsor
Reduce Business Personal Property Taxes

There is currently an exemption from property tax for business personal property that would otherwise be listed on a single personal property schedule that is equal to $7,400 for the current property tax year cycle. The bill raises the exemption to $50,000 commencing in tax year 2018, and continues to adjust it for inflation for subsequent property tax cycles, so that businesses with personal property under $50,000, or the inflation adjusted amount, would not have to file the business personal property tax forms nor pay the corresponding tax. The bill also raises the value of business personal property that qualifies for an exemption for consumable property from $350, which is the value set by the property tax administrator, to $500. (Note: This summary applies to this bill as introduced.) , Read More
In committee Feb 1, 2018 0 co-sponsors
Primary SB 17-009
Passed · Colorado Senate · Lead sponsor
Business Personal Property Tax Exemption

There is an exemption from property tax for business personal property that would otherwise be listed on a single personal property schedule that is equal to $7,300 for the current property tax year cycle. The bill increases the exemption to $10,000 for the next 2 property tax years and adjusts it for inflation for subsequent property tax cycles. (Note: This summary applies to the reengrossed version of this bill as introduced in the second house.)

Passed May 3, 2017 0 co-sponsors
Showing 1 to 10 of 16 bills