

Property Tax Administrative Procedures
Summary
The act makes multiple changes to procedural requirements for the administration of property tax in 2 broad categories: Deadlines and requirements for transmitting information. Modifications to deadlines. The act modifies property tax-related deadlines as follows:Aligns the regular and late application dates for the qualified-senior primary residence real property classification and the property tax exemption for qualifying veterans with disabilities and their spouses with those for the property tax exemption for qualifying seniors and their spouses. The regular application deadline is July 15, and late applications may be accepted until August 15.Increases from $10,000 to $20,000 the current threshold for a board of county commissioners (board) to recommend, or a county assessor with the approval of a board to settle, an abatement or refund of taxes. The threshold for the board being required to submit recommended abatement applications to the property tax administrator (administrator) for review is similarly increased from $10,000 to $20,000. The board is not required to submit an application to the administrator in the case of an abatement or refund caused by a valuation change made to ensure matching values within the same reassessment cycle.Clarifies the timeline for a petitioner to appeal a decision of the board of county equalization to the board of assessment appeals or submit the case to arbitration;Changes the real property protest deadline from June 8 to June 1;Changes the deadline from June 15 to July 15 for a county assessor to send a notice of valuation of personal property and changes the personal property protest deadline from June 30 to July 31 for a county that uses alternate protest and appeal procedures (alternate procedures) to determine objections and protests for taxable property;Clarifies that a county's use of alternate procedures may apply to real or personal property, or both; andAligns the protest deadline for personal property with the date that county assessors must conclude their hearings on such protests so that both the protest and hearing conclusion dates for personal property are June 30, or, for a county that uses alternate procedures, July 31. Modifications to requirements for transmitting information. The act modifies requirements for transmitting property tax information as follows:Clarifies that a county assessor or the board may transmit a required abstract of assessment, certification of taxes levied, or application for a recommended abatement or refund in excess of $20,000 to the administrator in a paper or electronic format;Reduces the number of copies of an application for a recommended abatement or refund in excess of $20,000 that the board must send to the administrator for review to one;Repeals the requirement that the administrator conduct a public hearing on proposed changes to property tax manuals, appraisal procedures, instructions, and guidelines, which are still required to be reviewed by the advisory committee to the administrator;Requires the administrator to prepare and publish standardized forms, including a letter of authorization, for all levels of property tax appeals;Reduces the number of copies of a notice of determination that an assessor must send to a taxpayer who has objected to the valuation of the taxpayer's property to one; andReduces the number of copies of an abstract of assessment that needs to be prepared to one.(Note: This summary applies to this bill as enacted.)
Bill status
signed
all 5 stages cleared
Introduction
Jan 2026
Committee Review
Mar 2026
Senate Passage
Mar 2026
House Passage
Mar 2026
Signed into Law
Mar 2026
Introduced Jan 27, 2026
Signed Mar 26, 2026
Maddy AI version diff · 5 comparisons
What changed between versions
Rerevised
→
Final Act
·
6 edits
·
Mar 13, 2026
MODERATE
This bill updates Colorado property tax procedures by extending deadlines for senior and veteran property classifications, increasing the financial threshold for tax abatements from $10,000 to $20,000, and simplifying paperwork requirements. It also modernizes how tax information is transmitted and standardizes appeal forms to reduce administrative burdens.
Scope change
The bill applies to all Colorado counties regarding property tax administration, abatement thresholds, and appeal procedures.
TIMELINE
Extended the deadline for late applications for senior and veteran property classifications from July 15 to August 15.
Adjusted various protest and notice deadlines for real and personal property to align with new administrative cycles.
REQUIREMENT
Increased the monetary threshold for tax abatements and refunds that require administrator review from $10,000 to $20,000.
Reduced the number of copies required for abatement applications and assessment abstracts from two to one.
Added a new requirement to prepare standardized, non-notarized appeal forms and guidelines for all levels of property tax disputes.
Changed the format for transmitting tax levies and abatement applications to allow either electronic or paper submissions.
Floor votes · House Mar 12, 2026
How they voted
This bill passed the Senate by voice vote (no roll call recorded).
Full legislative history
Actions timeline
Total actions
14
Key actions
7
Committee
2
Mar 26, 2026
Signed into law
Governor Signed
executive
Mar 18, 2026
Lower · Passed
Signed by the Speaker of the House
lower
Mar 17, 2026
Upper · Passed
Signed by the President of the Senate
upper
Mar 12, 2026
Lower · Passed
House Third Reading Passed - No Amendments
lower
Mar 9, 2026
Lower · Passed
House Committee on Finance Refer Unamended to House Committee of the Whole
lower
Feb 26, 2026
Introduced
Introduced In House - Assigned to Finance
lower
Feb 25, 2026
Upper · Passed
Senate Third Reading Passed - No Amendments
upper
Feb 17, 2026
Upper · Passed
Senate Committee on Finance Refer Amended to Senate Committee of the Whole
upper
Jan 27, 2026
Introduced
Introduced In Senate - Assigned to Finance
upper
4 primary · 20 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
Chris Richardson
RRepublican
P
Lisa Frizell
RRepublican
P
Matt Ball
DDemocratic
P
Yara Zokaie
DDemocratic
Co
Barbara Kirkmeyer
RRepublican
Co
Bob Marshall
DDemocratic
Co
Cathy Kipp
DDemocratic
Co
Dylan Roberts
DDemocratic
Co
Iman Jodeh
DDemocratic
Co
James Coleman
DDemocratic
Co
Janice Marchman
DDemocratic
Co
Jeff Bridges
DDemocratic
Co
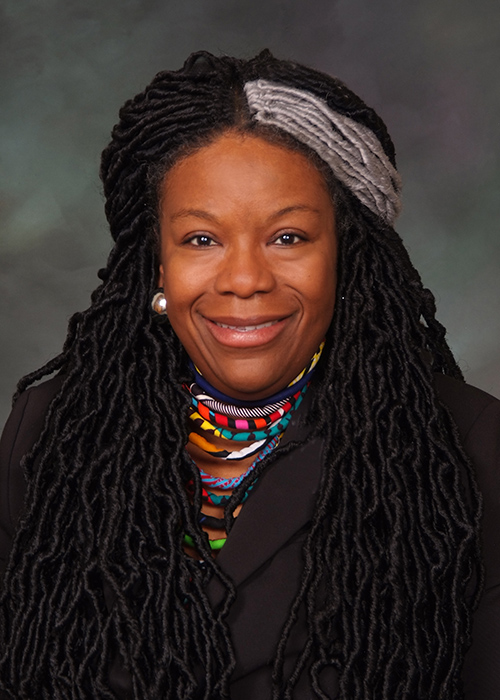
Jennifer Bacon
DDemocratic
Co
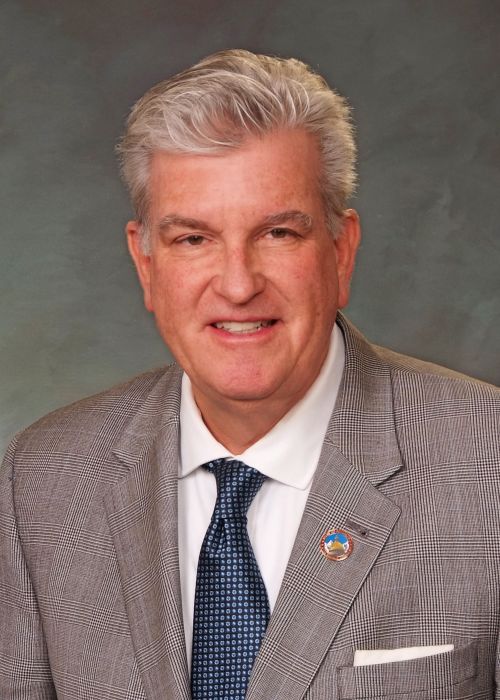
John Carson
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about SB 46
Scope: CO
Hi! I can help you understand SB 46. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline