

Modifying Certain Tax Expenditures
Summary
The act creates and allows taxpayers to claim a refundable tax credit, in addition to the child tax credit and the family affordability tax credit, in an amount determined by the amount and age of the taxpayer's children and the taxpayer's income. The total amount of the new tax credit is adjusted annually based on legislative council staff projections, such that the total amount of the new tax credit claimed in an income tax year is projected to be the same as the amount of revenue raised by the repeal of the downloadable software sales and use tax exemption elsewhere in the act. Beginning January 1, 2027, the act repeals the downloaded software sales and use tax exemption so that all software that is available for repeated sale and license qualifies as tangible property and thus is subject to sales and use tax. The act exempts from sales and use tax downloaded software governed by a negotiable license agreement or developed for use by a particular user. For each July, August, November, and December in 2027 and 2028, the act allows a qualifying retailer in the food or drink industry to deduct from state net taxable sales the lesser of state net taxable sales or $14,000. Currently, 15% of the net revenue collected as sales and use tax is credited to the general fund, less 1.655% (allocation percentage), which is credited to the housing development grant fund. Beginning January 1, 2027, and until December 31, 2028, the act reduces the allocation percentage to 1.629%. Beginning January 1, 2029, the allocation percentage is 1.625%. Beginning July 1, 2026, the act creates a sales and use tax exemption for a retailer selling food or drink (retailer) whose sales of prepared food exceed 25% of the retailer's sales revenue equal to 100% of the price the retailer paid for gas and electricity. A retailer whose sales of prepared food are 25% or less of the retailer's sales revenue is allowed a credit against the sales taxes otherwise due equal to 0.5% of the retailer's prepared food sales revenue. The repeal of the downloadable software sales and use tax exemption applies to the sale, storage, use, and consumption of tangible personal property on or after January 1, 2027. Provisions of the act are contingent upon House Bill No. 26-1221 and House Bill No. 26-1222 not becoming law. For the 2026-27 state fiscal year, the act appropriates $48,326 from the general fund to the department of revenue for tax administration system support and personal services.(Note: This summary applies to this bill as enacted.)
Bill status
signed
all 5 stages cleared
Introduction
Feb 2026
Committee Review
May 2026
House Passage
Jun 2026
Senate Passage
Jun 2026
Signed into Law
Jun 2026
Introduced Feb 17, 2026
Signed Jun 4, 2026
Maddy AI version diff · 5 comparisons
What changed between versions
Rerevised
→
Final Act
·
4 edits
·
Jun 2, 2026
MODERATE
The bill was finalized with minor formatting corrections and the addition of a note confirming it is ready for the Governor's signature. The substantive policy content regarding the new tax credit, eligibility rules, and revenue projections remains unchanged from the previous version.
Scope change
No change in the bill's scope or applicability; the text represents the final version prepared for execution.
TECHNICAL
Added a note at the beginning stating the bill is prepared for signatures and directing readers to official legislative status sheets for the Governor's action.
Corrected the sponsor list to include Representative Duran and Senator Coleman, who were missing in the previous version.
Removed the explanatory note about how to interpret the bill's formatting (e.g., shading and underlining) since this is the final enacted text.
Deleted the summary section describing the new tax credit, as this section is only applicable to the bill as introduced, not the final act.
Floor votes
How they voted
This bill passed the Senate by voice vote (no roll call recorded).
Full legislative history
Actions timeline
Total actions
18
Key actions
8
Committee
4
Amendments
1
Jun 4, 2026
Signed into law
Governor Signed
executive
Jun 3, 2026
Upper · Passed
Signed by the President of the Senate
upper
Jun 3, 2026
Lower · Passed
Signed by the Speaker of the House
lower
May 13, 2026
Upper · Passed
Senate Third Reading Passed - No Amendments
upper
May 13, 2026
Introduced
House Considered Senate Amendments - Result was to Concur - Repass
lower
May 13, 2026
Upper · Passed
Senate Third Reading Passed with Amendments - Floor
upper
May 11, 2026
Upper · Passed
Senate Committee on Appropriations Refer Amended to Senate Committee of the Whole
upper
May 7, 2026
Committee
Senate Committee on Finance Refer Amended to Appropriations
upper
May 4, 2026
Introduced
Introduced In Senate - Assigned to Finance
upper
May 4, 2026
Lower · Passed
House Third Reading Passed - No Amendments
lower
Apr 28, 2026
Lower · Passed
House Committee on Appropriations Refer Unamended to House Committee of the Whole
lower
Mar 9, 2026
Committee
House Committee on Finance Refer Amended to Appropriations
lower
Feb 17, 2026
Introduced
Introduced In House - Assigned to Finance
lower
4 primary · 20 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
Andy Boesenecker
DDemocratic
P
Dylan Roberts
DDemocratic
P
Matt Ball
DDemocratic
P
Steven Woodrow
DDemocratic
Co
Cathy Kipp
DDemocratic
Co
Chad Clifford
DDemocratic
Co
Emily Sirota
DDemocratic
Co
James Coleman
DDemocratic
Co
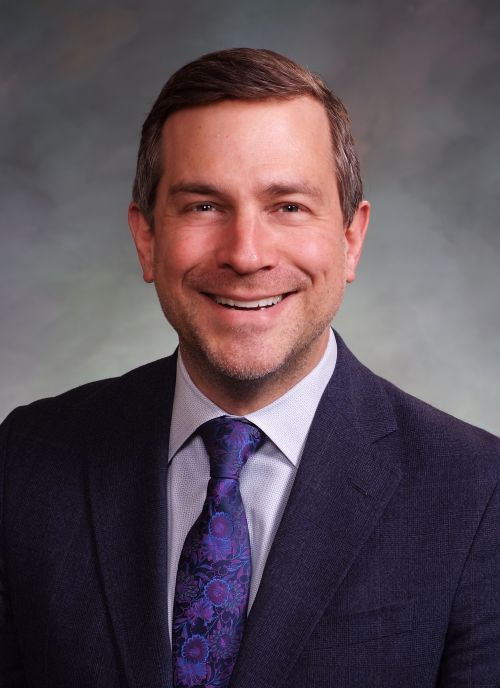
Jeff Bridges
DDemocratic
Co
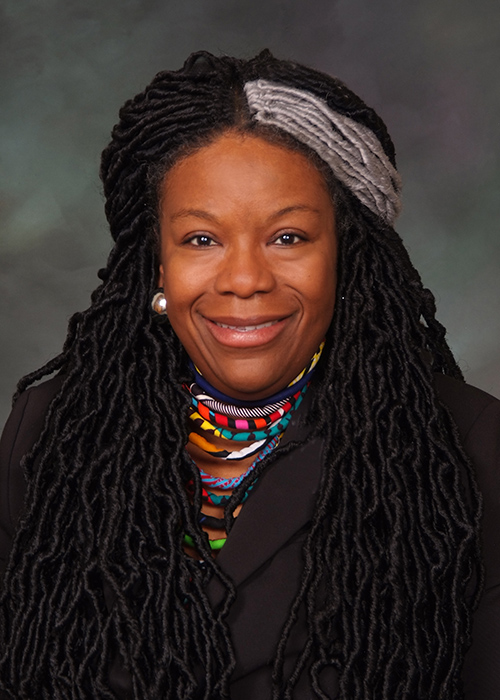
Jennifer Bacon
DDemocratic
Co
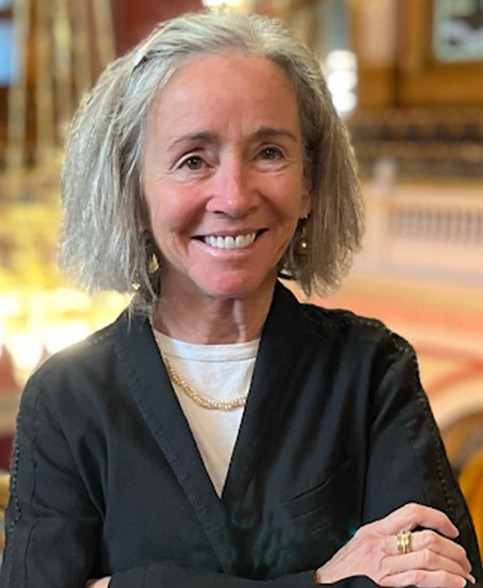
Judy Amabile
DDemocratic
Co
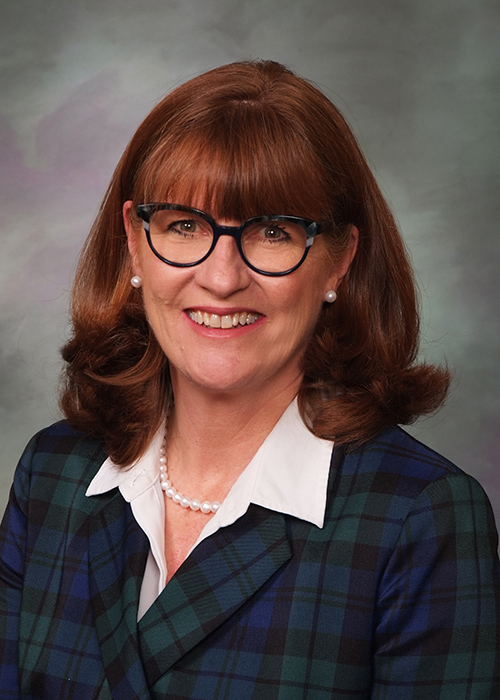
Julie McCluskie
DDemocratic
Co
Karen McCormick
DDemocratic
Co
Kenny Nguyen
DDemocratic
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 1223
Scope: CO
Hi! I can help you understand HB 1223. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline