

Opportunity Now Grants & Tax Credit
Summary
On July 1, 2024, the act requires the state treasurer to transfer $3.8 million from the general fund to the regional talent development initiative grant program fund to address workforce shortages in infrastructure and building trades. Of this amount, the office of economic development (office) is authorized to use not more than 7% for the administrative costs incurred to administer the regional talent development initiative grant program. The regional talent summit grant program (grant program) is created and is administered by the office. The grant program, through a selection committee, will award grants to and contract with a program facilitator to convene and facilitate regional summits across the state. The goals of the program facilitator are to understand workforce development needs in identified regions of the state, generate a landscape analysis for each identified region that includes job projections and an overview of educational pathways, gather insight from employers about critical workforce and training needs, create regional goals for addressing talent needs, and develop comprehensive tactical plans. Beginning January 1, 2026, any modified or new local workforce development plan must incorporate the tactical plans. The workforce development plans must be published in the Colorado talent report. The program facilitator must complete all regional talent summits on or before July 1, 2025, and submit workforce plans as a result of the regional talent summits by December 1, 2025. The grant program, through a selection committee, will also award grants to one or more regional hosts to secure facilities to host regional talent summits, determine community partners to attend the summits, and gather insight from regional employers about critical workforce and training needs. The regional talent summit grant program fund (fund) is created in the state treasury. On July 1, 2024, the state treasurer is required to transfer $200,000 from the general fund to the fund. The money in the fund is continuously appropriated to the office to be used for purposes of the grant program. The act establishes a state income tax credit (tax credit) for the costs of facility improvement and equipment acquisition associated with training programs designed to alleviate workforce shortages beginning January 1, 2026. A qualified taxpayer in a qualified industry may earn a tax credit equal to up to 50% of the costs incurred by the qualified taxpayer to improve its facilities and acquire equipment. The tax credit is refundable and may not be carried forward. To claim the tax credit, a qualified taxpayer must first reserve the tax credit by applying to be in the evaluation pool established by the office. A selection committee will consider the merits of each application to determine which taxpayers are qualified to reserve the tax credit. If a taxpayer is qualified and approved, the taxpayer is required to incur facility improvements and equipment acquisition costs to claim the tax credit. If the applicant submits evidence that the costs were incurred during the income tax year for which the applicant applied, and those costs are certified by a certified public accountant, the applicant may be awarded a tax credit. The aggregate amount of tax credits reserved in one calendar year cannot exceed $15 million and the amount is decreased to $7.5 million if the September revenue forecasts by legislative council or the office of state planning and budgeting project that state revenues will not increase by at least 4% for that fiscal year. A person or organization not subject to tax or a person or organization exempt from taxes is required to make and file a return containing information prescribed by the executive director to claim the tax credit. The workforce development tax credit program cash fund (fund) is created in the state treasury. The fund consists of gifts, grants, donations, and fee revenue credited to the fund and any money the general assembly may appropriate to the fund. The money in the fund is continuously appropriated to the office for the purpose of administering the tax credit. For the 2024-25 state fiscal year, the act appropriates $109,603 from the general fund to the office of the governor for use by economic development programs. The appropriation may be used for opportunity now grant administration. APPROVED by Governor June 7, 2024 EFFECTIVE August 7, 2024(Note: This summary applies to this bill as enacted.)
Bill status
signed
all 5 stages cleared
Introduction
Mar 2024
Committee Review
May 2024
House Passage
Apr 2024
Senate Passage
May 2024
Signed into Law
Jun 2024
Introduced Mar 8, 2024
Signed Jun 7, 2024
Floor votes · Senate May 6, 2024 · House Apr 26, 2024
How they voted
28–4
Passed · 2 other
Total votes 34
May 6, 2024
D
Democratic22
90% Yea
R
Republican12
66% Yea
Vote distribution
All Yea
All Nay
Mixed
No data
Full legislative history
Actions timeline
Total actions
15
Key actions
5
Committee
5
Jun 7, 2024
Signed into law
Governor Signed
executive
May 6, 2024
Upper · Passed
Senate Third Reading Passed - No Amendments
upper
May 4, 2024
Upper · Passed
Senate Committee on Appropriations Refer Unamended - Consent Calendar to Senate Committee of the Whole
upper
May 2, 2024
Committee
Senate Committee on Finance Refer Unamended to Appropriations
upper
Apr 29, 2024
Introduced
Introduced In Senate - Assigned to Finance
upper
Apr 26, 2024
Lower · Passed
House Third Reading Passed - No Amendments
lower
Apr 25, 2024
Lower · Passed
House Committee on Appropriations Refer Amended to House Committee of the Whole
lower
Apr 3, 2024
Committee
House Committee on Finance Refer Amended to Appropriations
lower
Mar 20, 2024
Committee
House Committee on Business Affairs & Labor Refer Amended to Finance
lower
Mar 8, 2024
Introduced
Introduced In House - Assigned to Business Affairs & Labor
lower
4 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
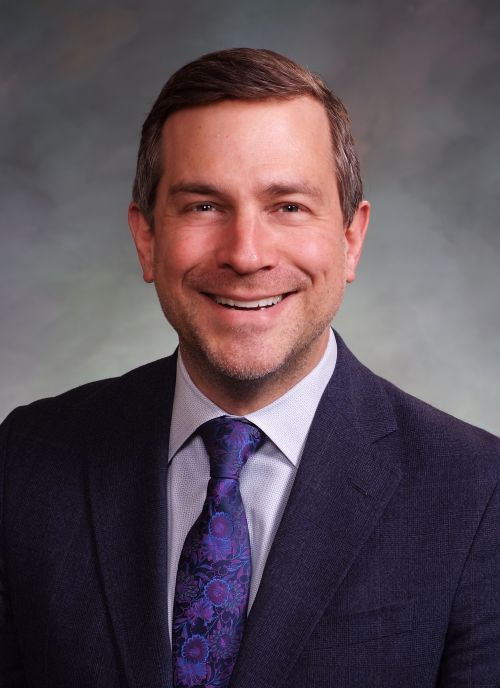
Jeff Bridges
DDemocratic
P
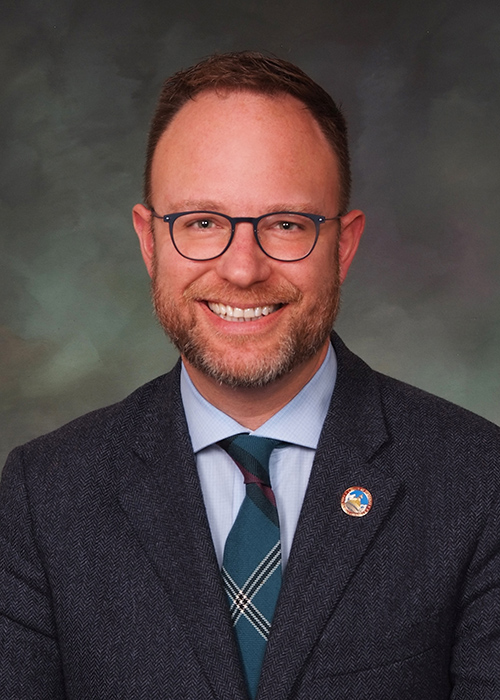
Matt Soper
RRepublican
P
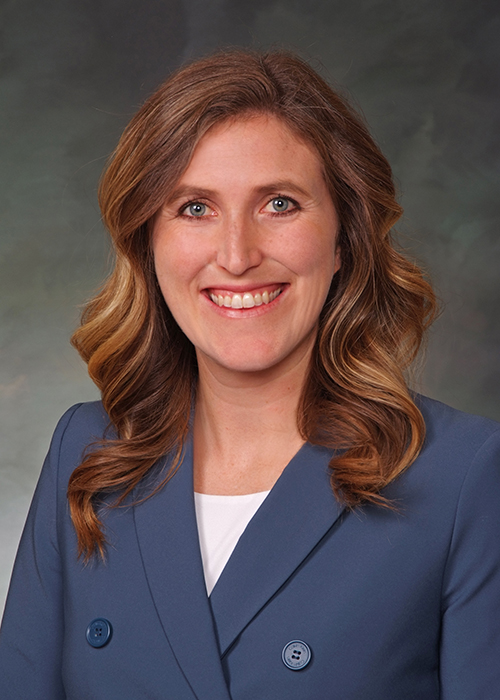
Meghan Lukens
DDemocratic
P
PW
Perry Will
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 24-1365
Scope: CO
Hi! I can help you understand HB 24-1365. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline