Maddy summaryHB 1001 reduces income tax rates for Arkansas residents, including individuals, trusts, estates, and both domestic and foreign corporations. For individuals, the bill establishes a progressive tax structure with rates ranging from 0% to 3.7% for income up to $94,700, while providing a specific tax credit for income between $94,701 and $97,600. Corporations see their tax brackets adjusted starting in 2027, with rates increasing from 1% to 4.1% on net income exceeding $11,000. The legislation also includes provisions for annual adjustments to the individual tax tables to account for inflation or other economic factors.

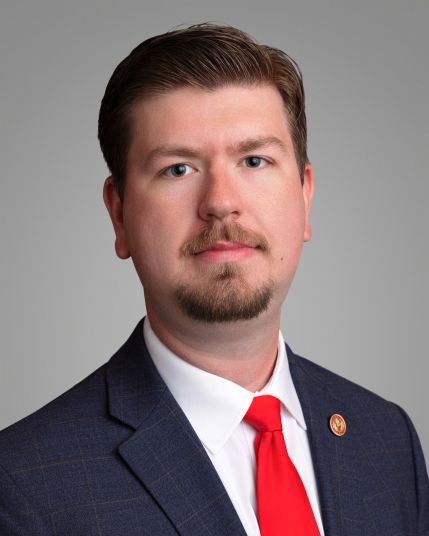
Rep. Wade Andrews
Sponsored bills
Maddy summaryHouse Bill 1534 proposes to increase the existing homestead property tax credit. This bill directly affects homeowners by reducing the amount of property taxes they owe on their primary residence. The key mechanism is an adjustment to the credit amount, providing a larger tax reduction for eligible households.
Maddy summarySenate Bill 473 amends the duties of the Arkansas Fire Protection Services Board. It changes the board's role from providing oversight to advising the Director of the Arkansas Fire Training Academy. This advisory function specifically covers matters related to the training and certification of fire services personnel in Arkansas. The board will also advise on the curriculum and instructional content offered by the Arkansas Fire Training Academy.
Maddy summarySB 526 proposed to prohibit the retail sale of specific disposable vapor products in Arkansas. It defined a "disposable vapor product" as one with a non-detachable battery that cannot be refilled and is designed for disposal after use. The bill would have banned retailers from selling such products if they originated from a "prohibited foreign party." The Director of Arkansas Tobacco Control could seize non-compliant products, with violations being a Class A misdemeanor, although FDA-approved products were exempt. A 90-day grace period was included for businesses to liquidate existing inventory.
Maddy summarySenate Bill 204 proposes to exempt certain financial gains from state gross income for tax purposes. This exemption would apply to taxpayers whose property is acquired by a government or entity under the right of eminent domain or the threat of condemnation. Essentially, any profit a property owner makes from such a forced sale would not be considered taxable income under this bill.
Maddy summarySenate Bill 151 proposes to amend state law regarding retirement benefits for members, retirants, and beneficiaries of public retirement systems. The bill aims to prohibit individuals from collecting these benefits if they have been convicted of certain offenses. An amendment to the bill further specifies that benefits can also be denied if a person is found civilly liable for the unlawful killing of a member or retirant. It also clarifies definitions related to "vested members" and the vesting of rights within a retirement system.
Maddy summaryHouse Bill 1626, as amended, aimed to prohibit the sale of certain disposable vapor products. The bill's central provision was to ban the sale of disposable vapor products that originate from a "prohibited foreign party," a term defined by referencing an existing legal statute (§ 18-11-802). This measure would have directly impacted retailers selling vapor products and consumers who purchase them. The bill did not pass and died in committee.
Maddy summaryHouse Bill 1695 clarifies the foreclosure process for properties subject to municipal liens, directly affecting municipalities, property owners, and other lienholders. The bill allows municipalities to establish priority for unrecorded municipal liens and outlines how proceeds from property sales are distributed based on lien priority. It requires municipalities to name all record lienholders in foreclosure actions where they claim priority; otherwise, the unnamed lienholder's claim remains on the property. Additionally, the bill enables municipalities to petition to set aside the sale of property to certain persons.
Maddy summaryHJR 1015 was a proposed constitutional amendment in Arkansas that aimed to change how judicial candidates appear on the ballot. If approved, it would have required candidates for Supreme Court Justice, Court of Appeals Judge, Circuit Judge, and District Judge to declare their political party affiliation or independent status. This declared affiliation or independent status would then be printed on the ballot for voters to see. The stated purpose of the amendment was to ensure transparency regarding judicial candidates' affiliations. This amendment would have taken effect on January 1, 2027, if passed.
Maddy summaryHB 1065, titled "TO CREATE THE INFLATION REDUCTION ACT OF 2025," died in the House Committee on Revenue & Taxation on May 5, 2025, without becoming law. The provided bill text contains no substantive policy language or specific mechanisms; it only includes a list of supporting legislators and procedural details. No concrete policy changes, affected groups, or key provisions are described in the available text. As a bill that stalled in committee with no enacted provisions, it did not implement any inflation-related measures. The title appears to be a placeholder, as no actual inflation reduction policy was outlined in the submitted bill.