SB 1293 Arizona Senate · 57th Legislature - Second Regular Session

GPLET; abatement; limitation

SB 1293 amends Arizona law to allow cities and towns to temporarily eliminate a tax on government-owned property improvements (like buildings on public land) for up to eight years. To qualify, the improvement must be located in a designated central business district (with strict size and compactness limits) and a blighted area, and must increase property value by at least 100%. For leases entered after May 2010, governing bodies must approve them with a simple majority vote after providing notice and an independent economic analysis showing community benefits outweigh lessee benefits (except for residential rental housing). The tax abatement must be applied for before the first tax payment due after the property is occupied.
Bill status vetoed 4 of 5 stages cleared
Introduction
Jan 2026
Committee Review
Mar 2026
Senate Passage
Feb 2026
House Passage
Apr 2026
Vetoed
Apr 2026
Introduced Jan 26, 2026 Vetoed Apr 13, 2026
Maddy AI version diff · 1 comparison

What changed between versions

Introduced Version Senate Engrossed Version (02/24/2026) · 5 edits · Feb 24, 2026
MODERATE
The bill was reformatted from a standard introduced version to a Senate engrossed version, incorporating significant substantive amendments to the Government Property Lease Excise Tax statute. These changes update the timeline for reviewing slum or blighted areas, clarify exemptions for residential housing, and impose new limits on lease durations and tax abatement amounts.
Scope change
The bill's scope remains focused on government property lease excise tax abatement, but the applicability of slum/blighted area designations and the duration of tax breaks have been modified.
TIMELINE

The automatic termination date for slum or blighted area designations was updated from the tenth anniversary to the tenth anniversary unless renewed, with specific review deadlines set for areas designated before September 30, 2018.

ELIGIBILITY

A new exemption was added for changes in use to residential rental housing, removing the requirement for an independent third-party economic estimate when such changes occur.

REQUIREMENT

A new subsection limits the maximum lease period for abated properties to eight years (including the abatement period) and requires the government lessor to convey title to the lessee within twelve months after the lease expires.

FISCAL

The tax abatement is now limited to the specific revenue amounts designated for counties, cities, and community colleges, explicitly prohibiting the abatement of the proportional tax revenue designated for school districts.

DEFINITION

The definition of a 'central business district' was updated to include specific geometric criteria for 'geographically compact' areas formed on or after January 1, 2018.

Floor votes · House Apr 8, 2026

How they voted

This bill passed the Senate by voice vote (no roll call recorded).
Full legislative history

Actions timeline

Total actions
15
Key actions
6
Committee
1
Amendments
2
Apr 13, 2026
Vetoed
Vetoed by Governor
executive
Apr 8, 2026
Lower · Passed
PASSED
lower
Apr 1, 2026
Lower · Passed
DP
lower
Mar 4, 2026
Lower · Passed
DP
lower
Feb 24, 2026
Upper · Passed
PASSED
upper
Feb 24, 2026
Upper · Passed
DPA
upper
Feb 9, 2026
Upper · Passed
DPA
upper
1 primary · 0 co-sponsors

Sponsors

Role
Legislator
Party
State
District
P
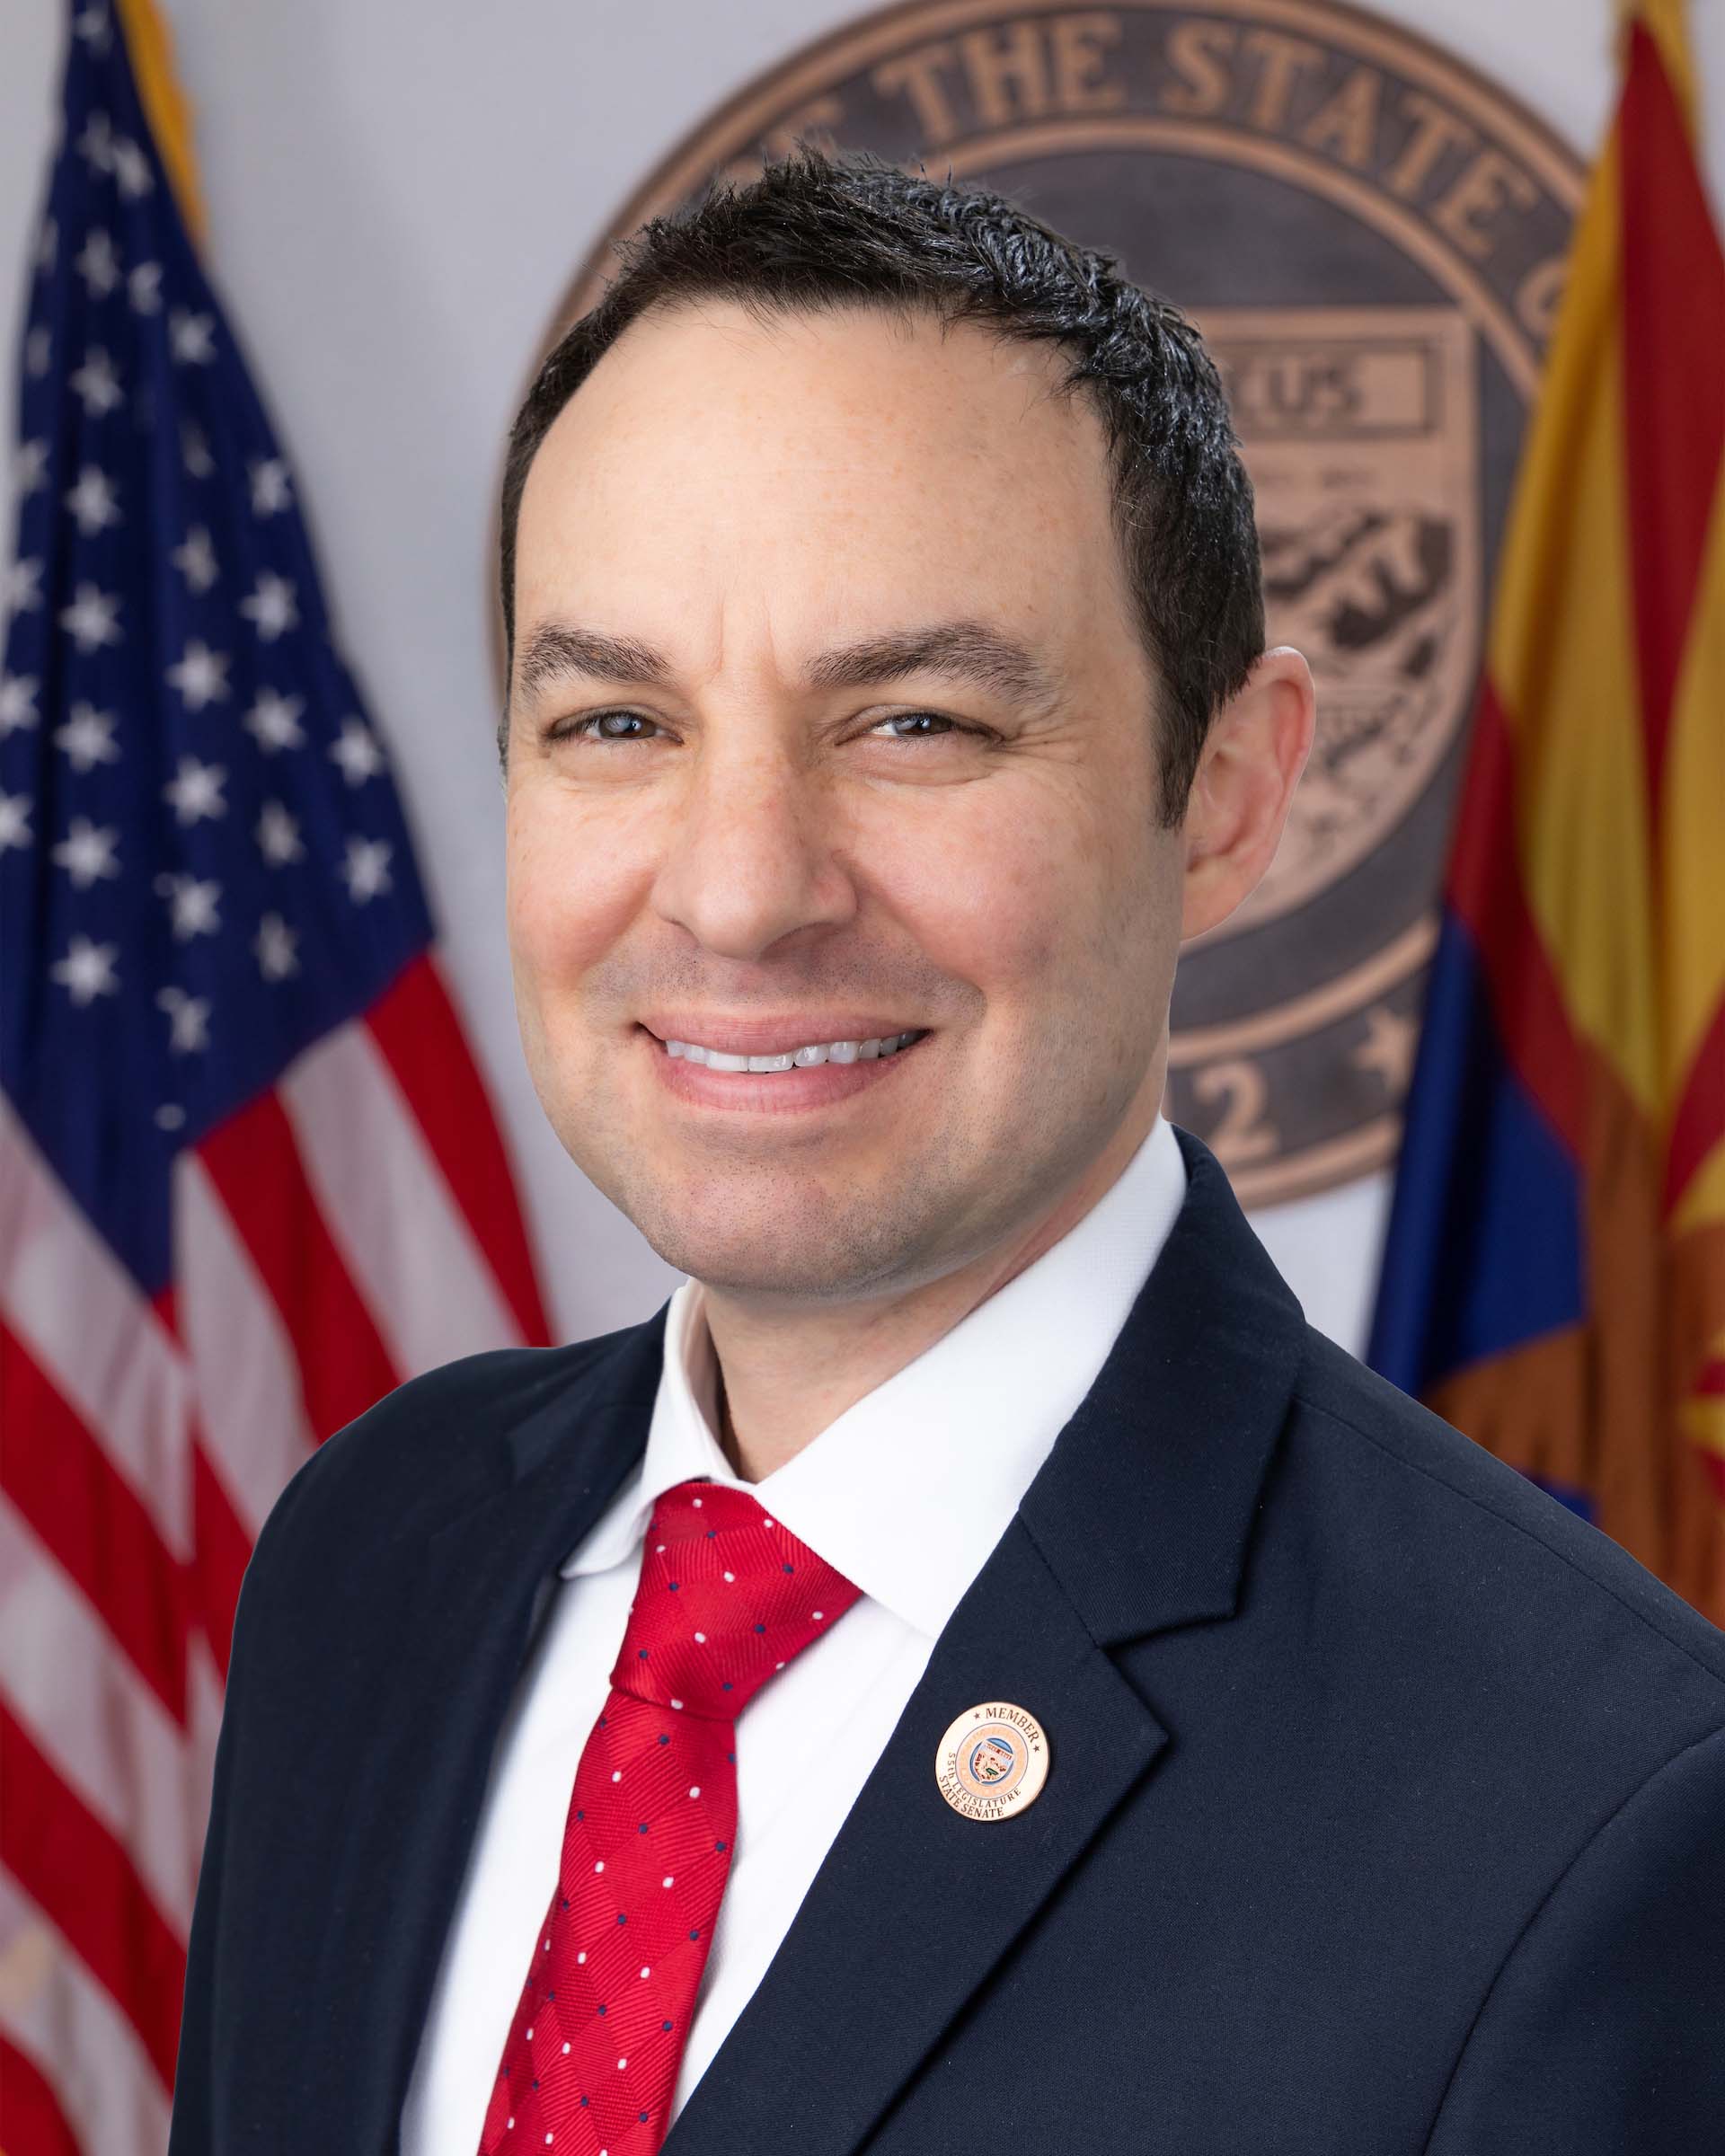
Photo of J.D. Mesnard
J.D. Mesnard
RRepublican
AZ
13