HB 2804 Arizona House · 57th Legislature - Second Regular Session

rural affordable housing; tax credits

Arizona's HB 2804 creates a new tax credit to support rural affordable housing development. It allows taxpayers (primarily developers or investors in qualifying projects) to claim a credit against their state insurance premium tax for projects in counties with under 800,000 residents that also qualify for federal low-income housing tax credits. The credit amount matches the state's allocation for each project, capped at $2 million annually through 2036, and requires an eligibility statement from the Arizona Department of Housing. Taxpayers can offset the credit against premium tax liability, carry forward unused portions for up to five years, and the program includes annual reporting requirements for the department.
Bill status passed 3 of 5 stages cleared
Introduction
Jan 2026
Committee Review
Feb 2026
House Passage
Feb 2026
Senate Passage
Governor
Introduced Jan 22, 2026 Last action Jun 12, 2026
Maddy AI version diff · 1 comparison

What changed between versions

Introduced Version House Engrossed Version (02/23/2026) · 7 edits · Feb 23, 2026
MODERATE
The bill was reformatted from a standard introduction to a final House version, adding a new purpose clause and retroactivity provision while retaining the core tax credit structure. The substantive policy changes include establishing a $2 million annual funding cap for rural housing projects, setting a start date of June 30, 2027 for project eligibility, and creating new administrative requirements for public hearings and annual impact reports.
Scope change
The bill's scope was expanded to explicitly include income tax credits alongside premium tax credits, and it now applies retroactively to taxable years beginning after December 31, 2026.
PURPOSE

Added a specific purpose clause stating the bill aims to support new affordable housing construction in rural areas.

TIMELINE

Added a retroactivity provision allowing the tax credits to be claimed for taxable years beginning after December 31, 2026.

ELIGIBILITY

Clarified that projects must be located in counties with populations under 800,000 and must be placed in service after June 30, 2027.

FISCAL

Established a $2,000,000 annual allocation limit for the tax credits, with unused funds rolling over to the next year.

REQUIREMENT

Mandated that the Department of Housing hold public hearings by July 30 each year to solicit comments on credit allocations.

ENFORCEMENT

Required the Department of Housing to submit an annual report by December 31 analyzing the economic impact and number of affordable housing units created.

DEFINITION

Formally defined 'qualified project' as a low-income building meeting federal Internal Revenue Code standards.

Floor votes · House Feb 23, 2026

How they voted

3522
Passed · 3 other
Total votes 60
Feb 23, 2026
D Democratic27
25 Yea 2
92% Yea
R Republican33
10 Yea 22 Nay 1
66% Nay
Vote distribution
All Yea All Nay Mixed No data
Full legislative history

Actions timeline

Total actions
8
Key actions
3
Committee
2
Feb 23, 2026
Lower · Passed
PASSED
lower
Feb 11, 2026
Lower · Passed
DP
lower
Feb 5, 2026
Lower · Passed
DP
lower
1 primary · 0 co-sponsors

Sponsors

Role
Legislator
Party
State
District
P
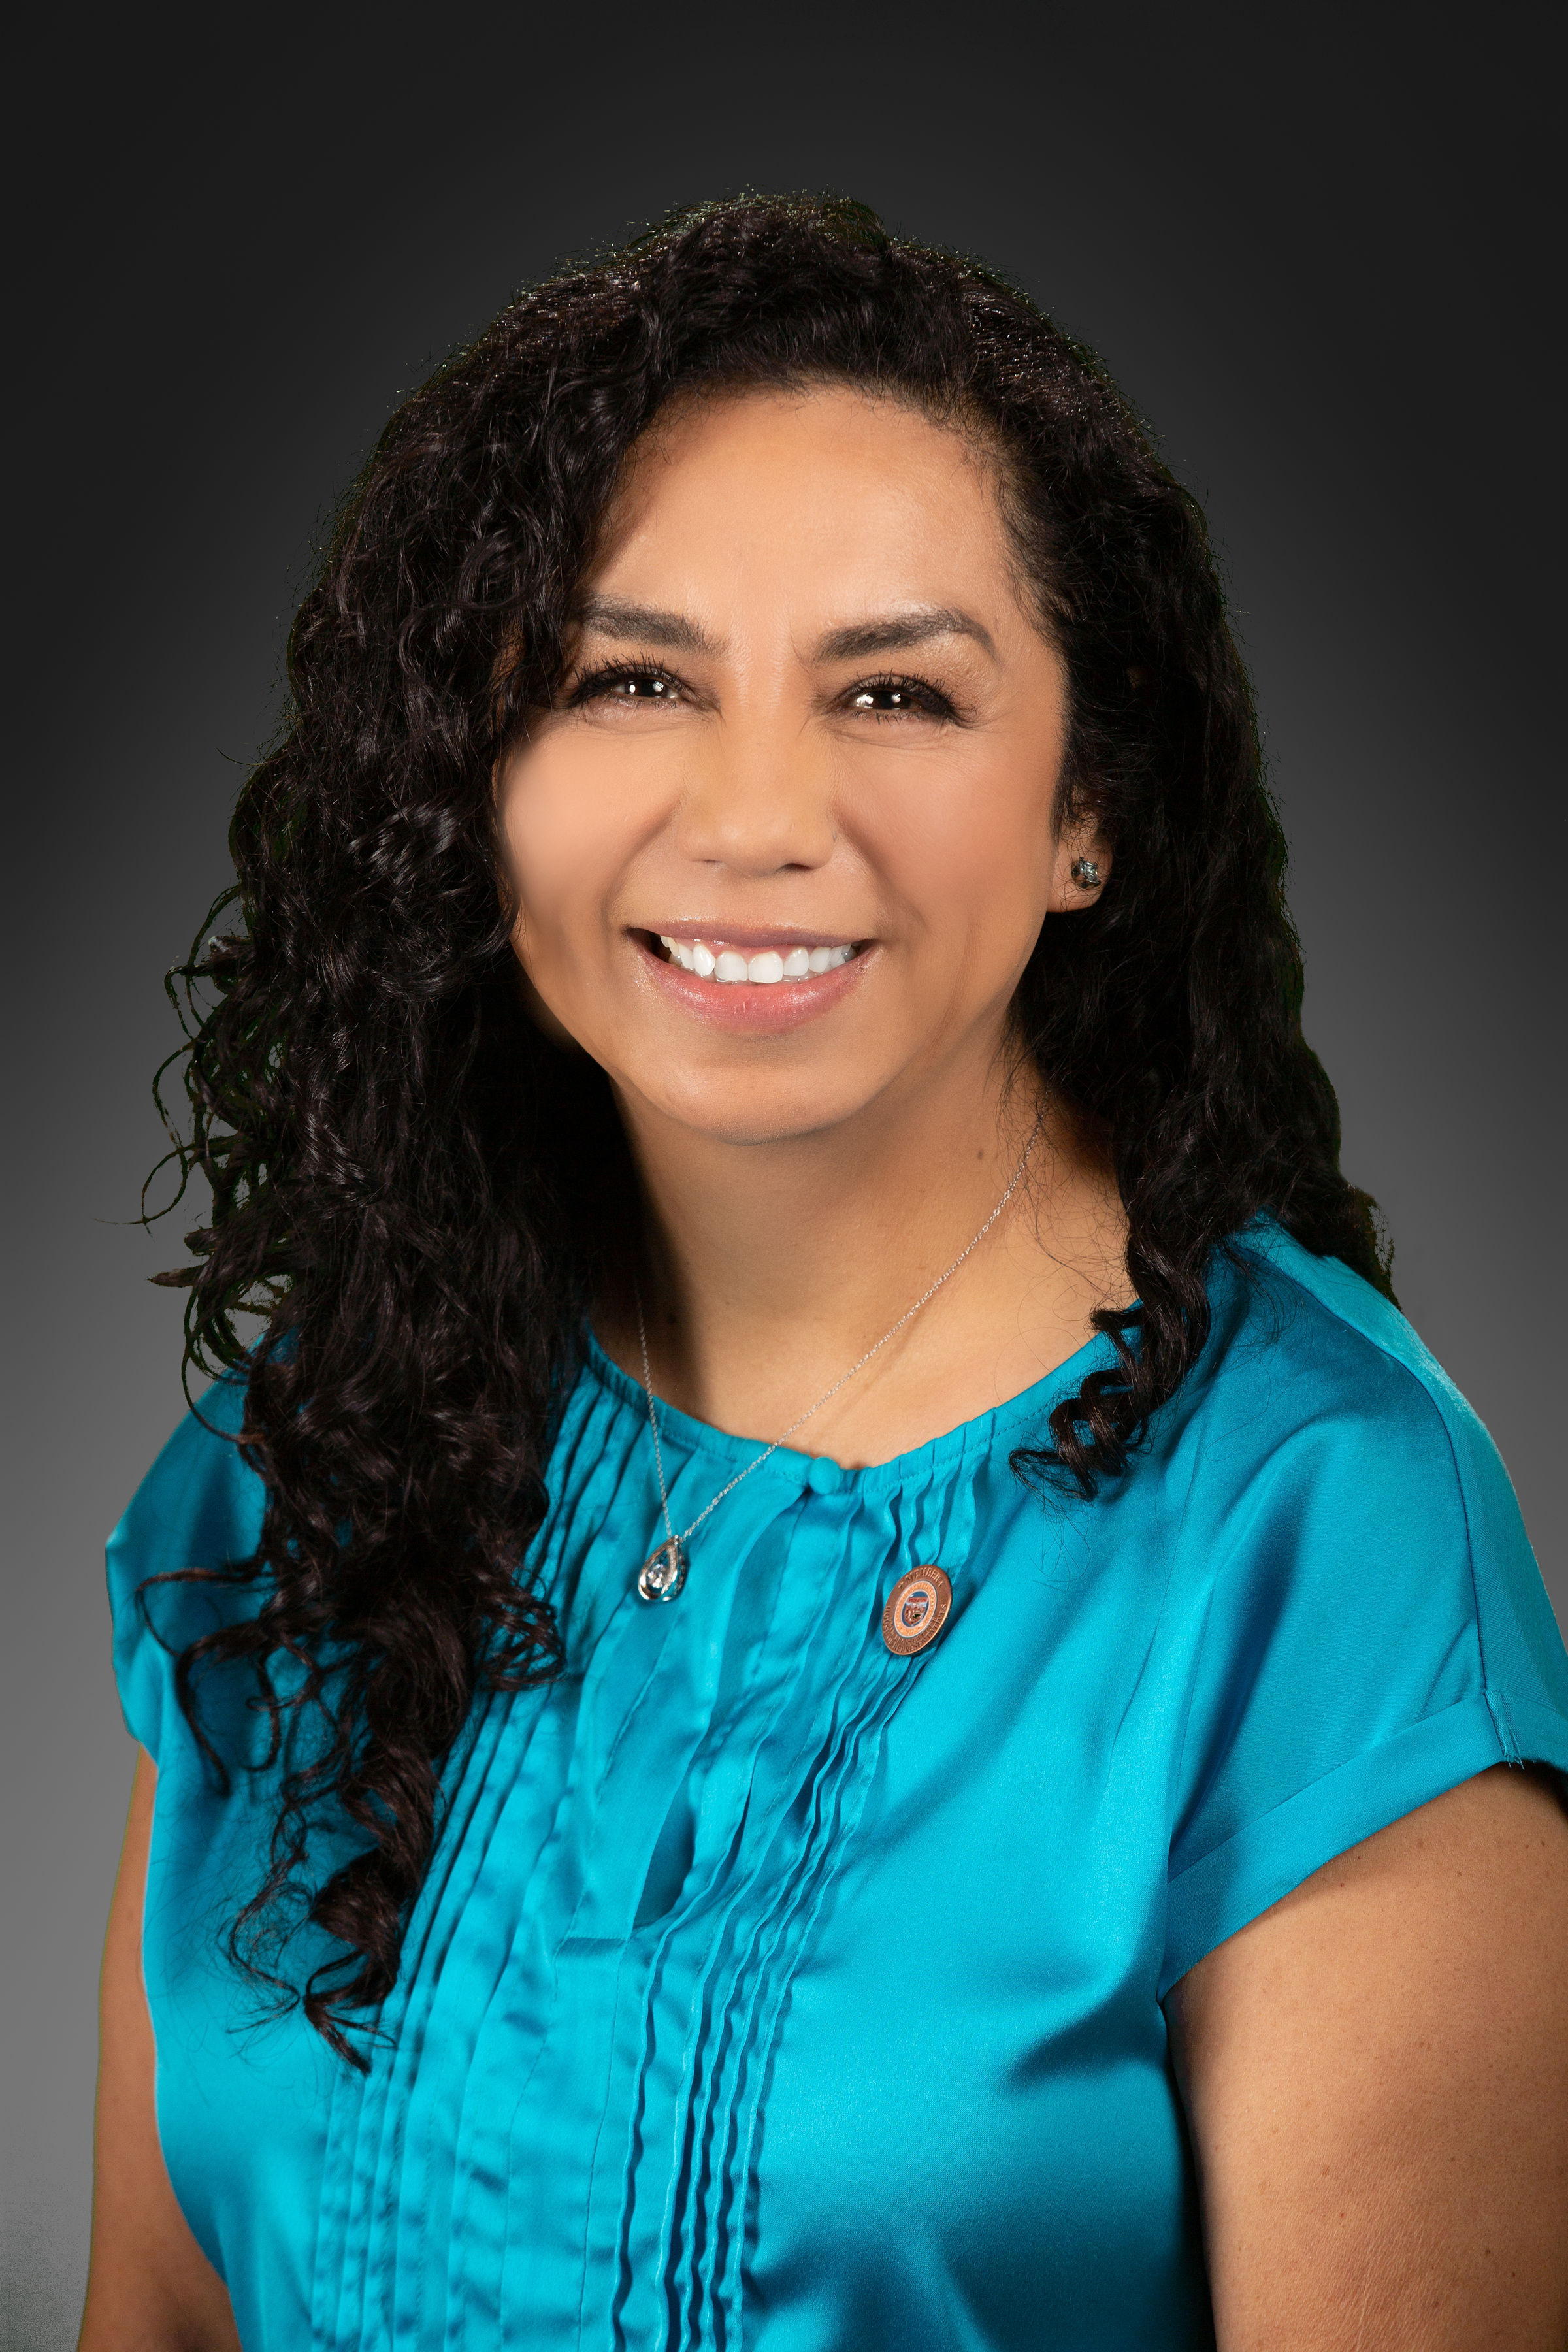
Photo of Teresa Martinez
Teresa Martinez
RRepublican
AZ
16