

Income tax, remote workers exempt under defined circumstances
HB 379 amends state income tax law to create an exemption for certain nonresident workers. It specifies that there will be no state income tax withholding or remittance obligation for wages paid to individuals temporarily in the state. This exemption applies when these nonresidents are performing disaster recovery work following a major disaster officially declared by the U.S. President or the State Governor.
Bill status
signed
all 5 stages cleared
Introduction
Mar 2025
Committee Review
Apr 2025
House Passage
Apr 2025
Senate Passage
May 2025
Signed into Law
May 2025
Introduced Mar 4, 2025
Signed May 14, 2025
Maddy AI version diff · 2 comparisons
What changed between versions
Engrossed
→
Enrolled
·
4 edits
·
May 14, 2025
MODERATE
The bill was finalized as Enrolled, updating its internal tracking number and removing redundant formatting. Substantively, the tax law now includes a new exemption for certain nonresident individuals (like public figures) who work in Alabama for 30 or fewer days, provided their home state offers similar relief. Additionally, the bill clarifies that employers must withhold taxes if an employee works in Alabama for more than 30 days in a year.
Scope change
The bill's scope expanded to explicitly include 'public figures' alongside athletes and entertainers for tax exemption purposes, and it clarified the 30-day threshold rule for when tax withholding becomes mandatory.
DEFINITION
Added a new definition for 'public figure' to include people of prominence paid for speeches or public appearances on a per-event basis.
ELIGIBILITY
Established a tax exemption for nonresident public figures, athletes, and entertainers who work in Alabama for 30 days or fewer in a calendar year.
REQUIREMENT
Clarified that if an employee works in Alabama for more than 30 days, the employer must withhold taxes for every day worked, including the first 30 days.
ENFORCEMENT
Added a provision stating that the tax department cannot penalize employers for withholding errors made in good faith when applying the new 30-day exemption rule.
Floor votes
How they voted
This bill passed the Senate by voice vote (no roll call recorded).
Full legislative history
Actions timeline
Total actions
23
Key actions
8
Committee
4
Amendments
4
May 6, 2025
Upper · Passed
Motion to Read a Third Time and Pass - Adopted Roll Call 966
upper
Apr 30, 2025
Upper · Passed
Reported Out of Committee Second House
upper
Apr 24, 2025
Upper · Passed
Pending Committee Action in Second House (Finance and Taxation Education)
upper
Apr 24, 2025
Lower · Passed
Motion to Read a Third Time and Pass as Amended - Adopted Roll Call 1010
lower
Apr 24, 2025
Lower · Passed
Motion to Adopt - Adopted Roll Call 1009
lower
Apr 24, 2025
Introduced
Garrett 1st Amendment Offered
lower
Apr 24, 2025
Lower · Passed
Motion to Adopt - Adopted Roll Call 1008
lower
Apr 24, 2025
Introduced
Ways and Means Education Engrossed Substitute Offered (Ways and Means Education)
lower
Apr 16, 2025
Lower · Passed
Reported Out of Committee House of Origin (Ways and Means Education)
lower
Apr 16, 2025
Introduced
Ways and Means Education 2nd Amendment (Ways and Means Education)
lower
Apr 16, 2025
Introduced
Ways and Means Education 1st Amendment (Ways and Means Education)
lower
Mar 4, 2025
Lower · Passed
Pending Committee Action in House of Origin (Ways and Means Education)
lower
1 primary · 0 co-sponsors
Sponsors
Role
Legislator
Party
State
District
P
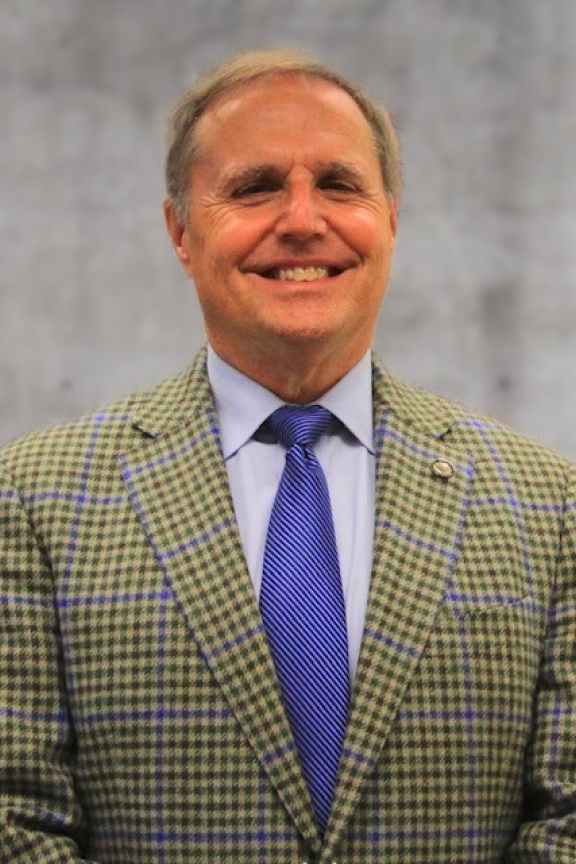
Danny Garrett
RRepublican
Ask Maddy
·
AI policy assistant
Ask Maddy about HB 379
Scope: AL
Hi! I can help you understand HB 379. What would you like to know?
Try one of these
i
Maddy answers using official bill text and legislative records. Always verify before sharing.
Sources cited inline